

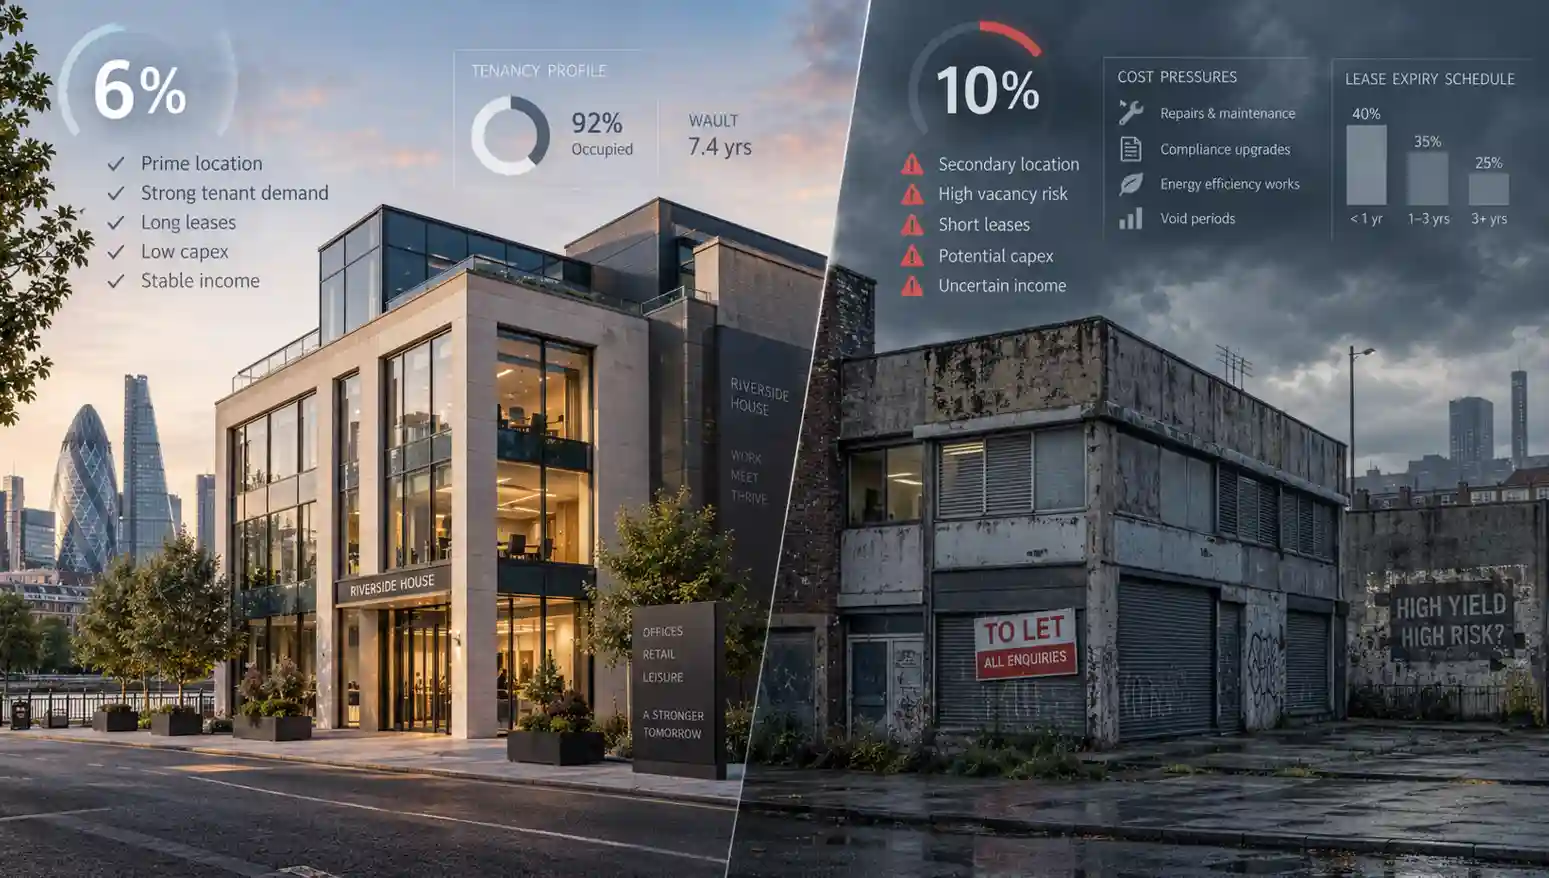
At the simplest level, the comparison looks irresistible. £100,000 of annual rent against a £1 million price produces a 10% income-to-price ratio; the same £100,000 against roughly £1.67 million produces about 6%. One building appears to give the buyer substantially more income for the same amount of capital.
But those extra four percentage points are not free money.
The price is telling you that buyers currently require considerably more compensation to own one income stream than the other. That may turn out to be an opportunity because the market has overestimated a problem, because it has underestimated future growth, or because a particular purchaser is better equipped than competing buyers to manage the risk. It may equally be an accurate price for weak income, an unsustainable rent, looming expenditure, poor growth prospects, difficult reletting or an asset that will be just as hard to sell in five years as it is today.
The useful question is therefore not “why is this property so cheap?” It is “what assumptions about risk, income growth and future value are embedded in this price, and do I have a good reason to disagree with them?”
That distinction matters in the current UK market. CBRE’s Q2 2026 commercial property index recorded rental values rising during the quarter while capital values still slipped slightly as yields moved outward in parts of the market. Income, rental growth and capital pricing can move in different directions, which is precisely why a headline yield cannot be interpreted on its own.
Before comparing 10% with 6%, make sure the two yields mean the same thing
For a professional investor, “the yield” is not sufficiently precise. A simple rent-divided-by-price calculation is useful for illustrating the relationship between income and capital value, but the market uses different yield measures depending on what is being analysed. Net initial yield, equivalent yield and reversionary yield are not interchangeable, and none of them is automatically the investor’s eventual IRR or total return.
RICS guidance on investment valuation makes the distinction particularly relevant where the passing rent differs materially from market rent. An under-rented or over-rented building can have a future cash flow that looks very different from the income implied by today’s initial yield.
The first discipline in any 10%-versus-6% comparison is therefore simply to establish that the percentages are measuring comparable things, on a consistent treatment of income and purchaser’s costs. A 10% net initial yield and a 6% equivalent yield are not meaningful competitors merely because both numbers carry a percentage sign.
Once the basis is consistent, however, the analysis should move quickly beyond the yield itself. A property can provide strong income on day one and still deliver a poor total outcome if rent falls, growth disappoints, the tenant leaves, substantial capital expenditure is required or the eventual exit value deteriorates. Where those future cash flows matter materially, RICS’s DCF guidance captures the underlying discipline: make the expected receipts and expenditure explicit rather than relying on one capitalisation rate to tell the whole story.
Yield is the symptom; the diagnosis sits in the income underneath it
Once the yield basis is understood, the next task is to identify why buyers are demanding it.
Tenant covenant is part of that analysis, but reducing covenant strength to “good tenant” or “bad tenant” misses much of what actually determines investment risk. The question is whether this particular occupier can continue meeting this particular rental obligation for the period being underwritten. Current accounts, profitability, cash generation, group structure, guarantees and other security may all matter more than the familiarity of the name above the door.
The property itself then has to be separated from the tenant occupying it today. A financially strong tenant can make a highly specialised or poorly located building look secure while the lease is running, but the investor ultimately owns the real estate as well as the covenant. If the occupier leaves, the relettability of that building becomes the problem.
Rent sustainability is where the two issues meet. A tenant may be financially sound while paying materially more than the market would support on a new letting. That can make an asset look particularly attractive on a passing-yield basis because the numerator in the calculation is temporarily high.
Over-renting is therefore one of the easiest ways for an apparently attractive yield to conceal a future income problem. If a building produces £500,000 a year today but comparable space would currently let for £400,000, the investor cannot assume the additional £100,000 continues indefinitely simply because it exists on completion day. At the relevant lease event, the value of that top slice depends on the lease mechanics and the probability of it surviving.
The reverse is also important. A lower-yielding property may not simply be “safer”; it may be under-rented in a market where buyers expect the income to rise towards a stronger rental level over the hold period. Yield differences therefore reflect not only downside risk but also different expectations for rental growth, reversion and future capital value. A 6% asset priced off defensible rental growth can offer a very different prospective return from a 10% asset whose passing rent is expected to fall.
This is why lease length cannot be assessed independently from rent and covenant. A long lease to a secure tenant at a sustainable rent can be extremely valuable. A long lease to a vulnerable business at a materially over-rented level is a different proposition entirely.
Break clauses deserve the same treatment. A ten-year contractual term with a tenant break in year five does not automatically provide ten years of certain income. The term certain runs to the break date, while the investor then has to form a view on whether the tenant is likely to exercise it and what the property looks like economically if they do. That probability belongs in the underwriting rather than being disguised by the headline lease expiry date.
The useful comparison is therefore not “10% property versus 6% property”. It is the durability, growth potential and future shape of the cash flow supporting each yield.
The building can make apparently strong income expensive to preserve
A yield calculated from today’s passing income can say very little about what the owner will need to spend to keep that asset competitive.
A building approaching substantial roof, plant, façade, lift or services expenditure does not become a better investment merely because the current rent produces a double-digit initial yield. If substantial expenditure will be required during the hold period, that cash has to be recognised in the return even though the headline yield does not show it.
The same applies to functional and environmental obsolescence. A building may remain fully occupied today while already falling behind what future tenants require in terms of specification, energy performance, loading, power, accessibility or workplace quality. Passing rent can therefore create an impression of stability that the next letting event exposes.
Reletting risk is where those latent costs tend to arrive together. Once an occupier leaves, the owner may face a void period, refurbishment or fit-out works, incentives for the incoming tenant, professional fees and other holding costs before income resumes. Non-domestic property taxes can also become part of the void cost after applicable reliefs, with the precise rules differing across the UK.
None of this means a secondary property with substantial capital requirements is automatically a poor investment. A purchaser with a genuine refurbishment advantage, access to cheaper works, stronger leasing capability or conviction that the market is improving may be able to buy exactly the problem other investors are avoiding.
But the comparison should then be honest. The buyer is not purchasing a clean 10% income return. They are purchasing today’s income plus a future capital and leasing obligation, and the investment case needs to price both.
Sometimes the yield is compensating for the capital market as much as the property
A higher yield can also reflect the difficulty of financing or eventually selling the asset.
Some properties appeal to a broad range of institutions, funds, private investors and lenders. Others have a much narrower buyer pool because of lot size, location, specialist use, tenant quality, short income, physical condition or financing constraints. Even where the current tenant continues paying exactly as expected, that difference in liquidity can justify materially different pricing.
This matters because an investor does not realise an exit yield in a spreadsheet; they eventually need another buyer willing and able to complete the transaction. A property acquired at 10% because only a small group of purchasers wants it today may still face that same buyer-pool problem when it is sold, particularly if none of the characteristics that produced the original discount has changed.
Lender appetite can reinforce the effect. An asset that attracts limited or expensive debt does not merely affect leveraged returns for the current purchaser; it can reduce the number of future buyers capable of financing the acquisition at all. The equity investor should therefore distinguish between property-level risk and capital-market liquidity risk, even though both can appear in the same headline yield.
Leverage should not then be allowed to make an unattractive asset look attractive. Debt may improve an equity return when the property performs as expected, but it can magnify the consequences of voids, capex or falling value just as effectively. The quality of the underlying property cash flow needs to make sense before financing is allowed to improve the headline return.
Two properties can offer different yields because they are offering different investments
Consider two simplified acquisitions being marketed at headline net initial yields of approximately 6% and 10%.
Property A is a modern building in a location with established occupier demand. The tenant is financially sound, the passing rent sits reasonably close to current market evidence and there is a meaningful pool of alternative occupiers for the space. The building is unlikely to require major near-term capital expenditure, while the local rental market offers a credible prospect of at least maintaining — and potentially improving — the income over time. The investor can also see a reasonably broad market of potential buyers at exit.
Property B is older and sits in a weaker secondary location. Most or all of the income depends on one tenant whose covenant requires closer examination, while the passing rent is materially above the level being achieved on recent comparable lettings. The building would require meaningful expenditure to compete for another occupier, there are fewer obvious buyers for the investment in its current form, and the current yield partly reflects the possibility that the rent will fall rather than grow when the lease event arrives.
The 10% yield on Property B does not make Property A the automatic better acquisition. An investor with specific expertise in that location, evidence that the market rent is stronger than consensus suggests, a credible refurbishment plan or an ability to reconfigure the asset may conclude that the market has over-discounted the risk. In that case, the high yield can be the entry point into genuine value creation.
But that conclusion has to come from the underwriting, not from the size of the percentage.
A useful test is to normalise both investments rather than compare today’s income alone. Rebase rents where necessary to defensible market levels at the relevant lease events, model realistic growth or decline, allow for the consequences of any tenant break or expiry, include the capex and leasing expenditure needed to keep the building competitive, recognise periods without income and consider what yield a future purchaser might reasonably apply when the asset is sold.
The question then becomes harder but much more useful: after all of that, is Property B still sufficiently cheaper to compensate for what needs to go right?
If it is, the 10% property may genuinely offer the better risk-adjusted opportunity. If it is not, the extra four percentage points were never an advantage; they were simply the price the market required to transfer the problem.
What the extra yield actually needs to pay you for
A high yield should trigger investigation rather than excitement or suspicion by default.
The investor needs to understand what proportion of the yield premium reflects covenant risk, unsustainable rent, weak rental growth, lease-event uncertainty, capital expenditure, reletting, physical obsolescence, financing constraints or eventual exit liquidity. In practice those factors frequently overlap, which is why comparing one yield with another can create false precision.
The critical judgement is whether those risks and growth assumptions are merely different from the prime market or genuinely mispriced.
That is the dividing line between a cheap commercial property and a value trap. A value investor does not need an asset to be low-risk; they need the price to compensate adequately for the risks that remain after they have been understood properly, while leaving enough upside if their view of rent, reversion or asset improvement proves more accurate than the market’s. Conversely, a high yield offers little protection where the purchaser has underestimated the probability, timing or cost of the problem behind it.
A 10% yield can absolutely be a better investment than 6%, but the four percentage points themselves are not the reason. The reason has to be that, after normalising the income, modelling growth and lease events, funding the building and considering the eventual exit, the price still pays the investor enough for the uncertainty being accepted.
This article provides general commercial-property market and investment information, not valuation, financial, tax, legal or investment advice for individual circumstances. Yields, rental values, tenant covenant, lease terms, financing, capital expenditure and exit assumptions vary materially between properties and should be independently investigated and professionally appraised before an acquisition decision.

