

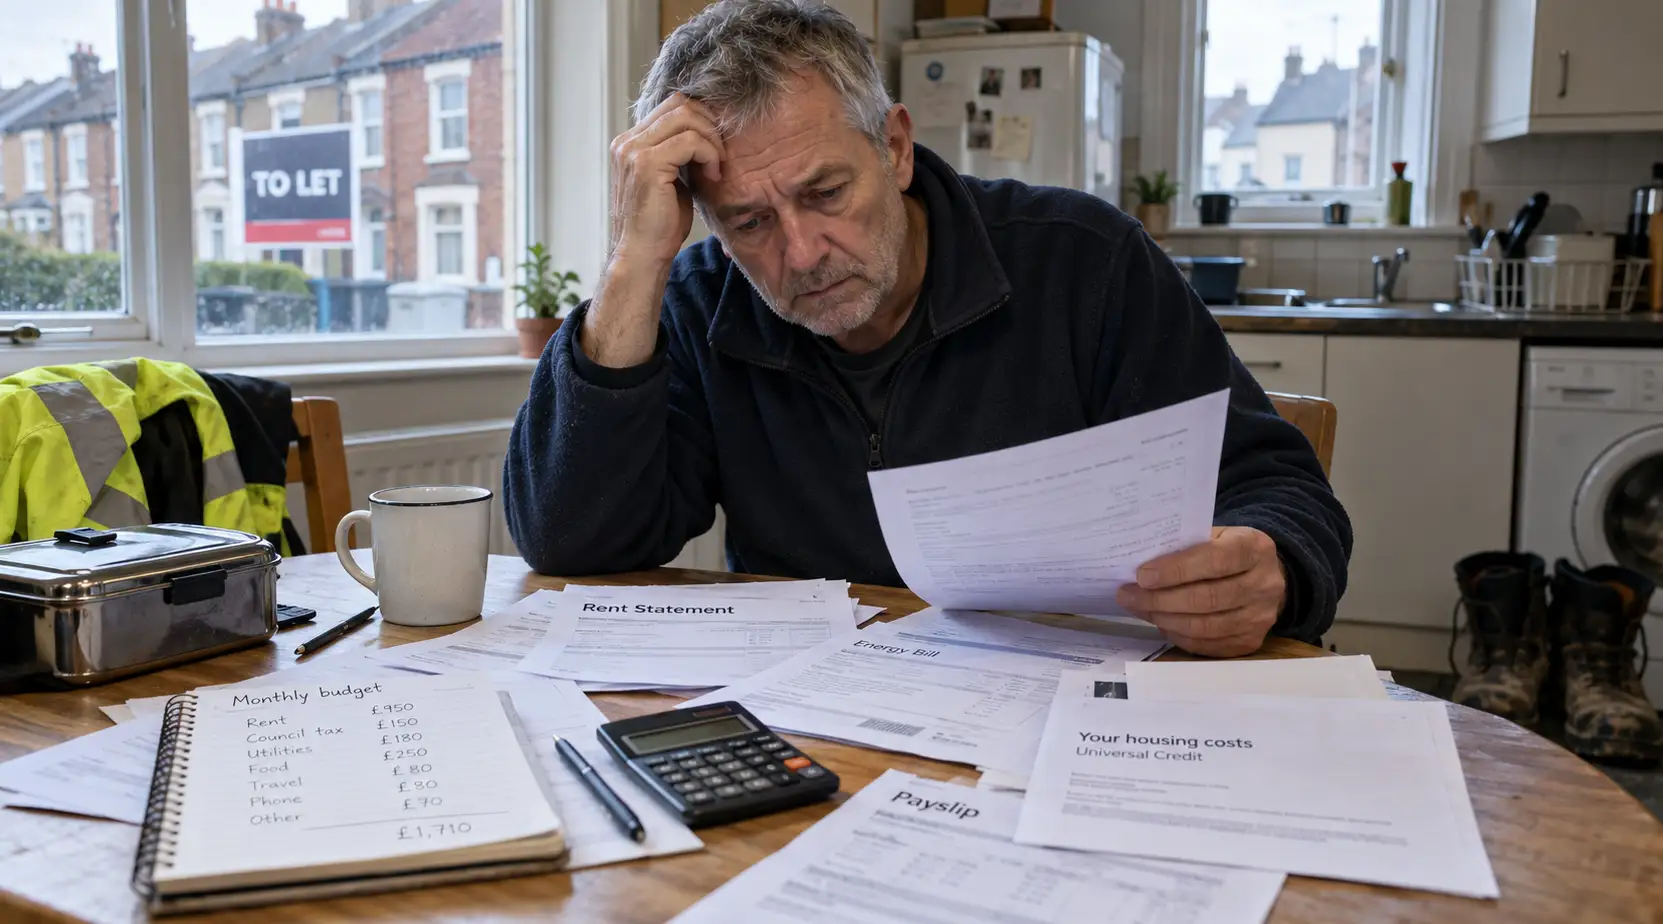
Help with housing costs is meant to give low-income households a stable base from which to work, look for work or work more hours. New research from Citizens Advice suggests that, for a growing number of private renters, the opposite may be happening: a gap between their housing support and their rent is squeezing the very things that make working possible, from childcare to the bus fare.
The charity’s briefing, Exploring the links between frozen Local Housing Allowance and employment, published on 19 October, estimates that around 985,000 households in Great Britain — 58% of privately renting households receiving the housing element of Universal Credit — face a shortfall between their housing support and their rent.
Crucially, half of households receiving Local Housing Allowance are already in employment. The problem is therefore not simply about getting people off benefits and into jobs. It is also about whether those already working can afford to keep working, or increase their hours, when housing costs absorb so much of their income.
The publication is a piece of research and a call for policy change, not an announcement of one. But it arrives just over a week before the Budget on 28 October and raises a question with consequences well beyond the welfare system: could freezing housing support actually make it harder for some people to work?
How the gap opens
Local Housing Allowance is not a separate benefit. It determines the maximum amount of help most private tenants can receive towards their rent through Universal Credit or Housing Benefit, with rates varying according to local rental markets and the size of accommodation a household qualifies for. The amount someone actually receives can also depend on their circumstances and other benefit rules.
The system was designed around the 30th percentile of local rents, broadly the level intended to make the cheapest 30% of suitable rental properties affordable. Rates were restored to that benchmark in April 2024, using rental evidence collected up to September 2023, but have remained frozen since. The government’s published 2026/27 rates confirm that allowances have not increased with subsequent rents.
That matters because rents have continued rising. The Resolution Foundation’s September research found that, across England, the 30th-percentile rent for a two-bedroom property was, on average, £158 a month above the corresponding frozen LHA rate. That is equivalent to £1,896 over a year. It is a comparison between market rents and benefit limits, rather than the average actual shortfall experienced by claimants, but it demonstrates how far the original affordability benchmark has moved.
Our recent reporting on record rents and Britain’s increasingly uneven rental market also illustrates why a slower rate of rent growth does not necessarily make housing affordable again. A household that was already struggling may find little relief if its rent continues to increase, even more slowly, while the amount of support remains unchanged.
For households with little disposable income, the gap has to be met by cutting other expenditure. Some of that expenditure, however, is essential to maintaining employment. A parent cannot necessarily work an additional shift without paying for childcare, and somebody travelling to a job interview may need money before there is any prospect of earning it back.
What the research found
Citizens Advice draws on government information, its own advice and debt data, interviews with frontline staff and survey research. These different sources help explain the scale of the problem and how it affects households, although they do not all measure the same thing.
Its March 2026 Cost of Living Tracker surveyed a representative sample of 5,559 UK adults, with additional sampling of groups including Universal Credit recipients and renters. Among private renters receiving Universal Credit, one in five reported that difficulty affording essentials had affected their ability to find work or increase their working hours.
Childcare provides one of the clearest examples of how the pressure operates. Among the surveyed private renters on Universal Credit who had cut back or stopped spending on paid childcare, 53% said they had reduced their hours or stopped working as a result. The percentage refers to that particular subgroup, not to all private renters on Universal Credit, and the research does not establish that the LHA freeze was the sole cause.
There is an important distinction here between reporting a problem and proving its cause. Families struggling with childcare may also face health problems, irregular working hours, limited local employment or caring responsibilities. The survey identifies an association between financial difficulty and reduced employment, but cannot isolate how much of that reduction is specifically attributable to frozen housing support.
The charity’s debt-advice evidence gives a different indication of the pressure households face. Private renters receiving Universal Credit who sought its debt advice had an average monthly budget deficit of £69.97, meaning their essential expenditure exceeded their income. That was more than 20 times the average deficit among social renters receiving Universal Credit who sought comparable advice.
These figures describe households already experiencing significant financial difficulties, rather than private renters generally. They also reflect overall household budgets, not simply the difference between rent and LHA. Nevertheless, they show how little room some families have to absorb additional costs.
Nor does Universal Credit necessarily remove the difficulty of paying for childcare. Eligible working parents can receive support covering up to 85% of approved childcare costs, subject to limits, but reimbursement arrangements may require parents to pay first. Additional help with upfront costs can be available when someone starts work or increases their hours, although it does not eliminate every financial or practical obstacle.
The government’s childcare guidance explains those arrangements, which are particularly relevant to parents who might otherwise turn down work because they cannot fund the childcare needed to take it.
Taken together, the Citizens Advice evidence supports a credible argument: inadequate housing support can contribute to financial pressures that make employment more difficult. What it does not yet establish is how much additional employment would result if LHA rates were increased.
The geography of a hard choice
The same housing shortfall can have very different consequences depending on where someone lives.
In an expensive city with plentiful jobs, finding work may be easier than finding accommodation within the LHA rate. Moving further away could lower the rent, but increase travel costs, lengthen the working day and make childcare arrangements harder to manage. In a cheaper area with limited public transport, a household may find an affordable property but discover that getting to work requires a car it cannot afford.
Citizens Advice describes households caught between somewhere they can afford and somewhere close enough to employment, schools and family support. Its frontline research shows how those choices can become particularly difficult for people working early shifts, parents relying on relatives for childcare or households living in areas with few suitable rental properties.
The geographical evidence is also revealing. The charity found that areas with particularly high proportions of LHA shortfalls often have relatively low employment among households receiving housing support, notably in Wales and parts of northern England. Six of the 20 rental market areas with the highest prevalence of shortfalls were also among the 20 with the highest proportions of supported households not in employment.
But the relationship across rental market areas is weak, and it does not establish causation. Places with fewer jobs, lower earnings or greater levels of ill health may experience both housing affordability problems and lower employment for reasons that overlap without being identical. The research itself acknowledges those limitations.
There is also a wider housing-market problem. Households cannot necessarily solve a rent shortfall by moving somewhere cheaper if the right kind of accommodation is unavailable. A single person may struggle to find a suitably priced room or small flat, while a family may need to remain near schools and childcare. Moving to a less expensive area can also mean sacrificing the informal support that makes employment possible.
For tenants whose finances deteriorate, the consequences may eventually extend to rent arrears and the loss of their home. Our guide to when councils should help tenants facing eviction explains the importance of seeking assistance before a tenancy reaches that point.
Housing insecurity can itself become an obstacle to maintaining employment. Someone forced to move away from their workplace, or temporarily accommodated somewhere with poor transport connections, may find that retaining a job becomes more difficult just when a stable income is most needed.
Who gains if rates rise — and who pays
Citizens Advice wants the government to restore LHA to the 30th percentile of local rents and maintain that link permanently. The immediate beneficiaries would be tenants whose housing shortfalls would shrink, giving them more money for other essentials and potentially making employment easier to sustain.
Landlords and letting agents could also benefit from tenants being better able to pay their rent, reducing the risk of arrears and failed tenancies. Councils might face fewer households requiring homelessness assistance or temporary accommodation, while employers could benefit where staff become better able to afford transport and childcare. These are plausible consequences, rather than benefits the research has established would occur in every case.
The strongest objection is the cost to public finances and the possibility that landlords would capture some of the additional support through higher rents.
There is now useful independent evidence on that question. The Resolution Foundation’s September study examined changes following the April 2024 LHA increase and estimated that around 10p of every additional £1 of support was reflected in higher rents at the lower end of the market.
That estimate is based on rental-market data rather than directly measuring the experience of every claimant. The researchers acknowledge statistical uncertainty, but their findings do not support the assumption that most additional housing support is automatically captured by landlords. The evidence instead suggests that the majority of the previous increase benefited tenants.
The financial commitment would still be considerable. The Resolution Foundation estimates that restoring the link from April 2027 and maintaining it would cost around £2 billion annually by 2029/30 compared with continuing to freeze rates. That is an estimate for a particular policy, not a confirmed Budget decision or an assessment of the net cost after any wider economic effects.
There is an important employment trade-off in how such an increase might be funded. One option suggested by the Resolution Foundation is to raise the Universal Credit earnings taper from 55% to 58%. That would mean some recipients losing an additional three pence of Universal Credit for every extra pound of earnings subject to the taper.
Such a change might improve housing affordability while reducing the immediate financial reward from working additional hours. It illustrates why the design and funding of a housing-support increase matter, particularly when the stated objective includes helping people remain in or enter employment.
The alternative of leaving rates frozen also has potential costs. Tenants struggling with arrears may become homeless, councils may have to provide temporary accommodation, and some households may find their ability to work reduced. But those effects have not been quantified sufficiently to conclude that increasing LHA would pay for itself.
The government therefore faces more than a simple choice between spending money and saving it. It must weigh the direct cost of housing support against the possible consequences of leaving low-income renters with increasingly unaffordable homes, while recognising that neither approach will resolve shortages of suitable rental accommodation.
What tenants can check now
For tenants already facing a shortfall, any possible Budget change remains uncertain. The current LHA rates are fixed for 2026/27, and an announcement on 28 October would not automatically increase an existing Universal Credit award.
There may be other help available in the meantime. In England, Discretionary Housing Payments were replaced in April 2026 by Housing Payments under the Crisis and Resilience Fund. Wales and Scotland continue to operate Discretionary Housing Payments. These schemes can assist eligible households with housing costs, but awards are discretionary and depend on individual circumstances.
Tenants should also check that their Universal Credit information reflects their current circumstances, including changes to employment, earnings and eligible childcare costs. Independent advice may help identify assistance that has been overlooked.
The evidence that would settle it
The argument Citizens Advice is making is an important one: a housing-support freeze intended to control public spending may carry wider costs if it leaves people less able to find work, remain employed or increase their earnings.
Its research shows substantial housing shortfalls and gives credible examples of how financial hardship can interfere with employment. Independent evidence also suggests that increasing LHA is more likely to benefit tenants than to be absorbed entirely through higher rents. But neither finding establishes the precise employment gain that would result from a new uprating.
That would require stronger evidence tracking how people’s employment, hours and earnings change as housing support and rental costs change, while accounting for the many other influences on their working lives. A fuller fiscal assessment would also need to examine any measurable effects on tax receipts, Universal Credit expenditure, homelessness services and temporary accommodation.
The Budget will reveal whether ministers are prepared to restore the link between housing support and rents. The more demanding test will come afterwards: whether households become better able to maintain their homes, whether working renters can afford to remain in employment, and whether the benefits justify the public expenditure.
Until then, the freeze is a decision taken on the cost of one side of the ledger.
This article reflects housing-support rules and published research available on 20 October 2026. It concerns Great Britain; Northern Ireland operates different social-security arrangements. Universal Credit, Housing Benefit and discretionary housing assistance depend on individual circumstances and applicable national rules. This article provides general information, not individual welfare-benefits, financial or legal advice.

