

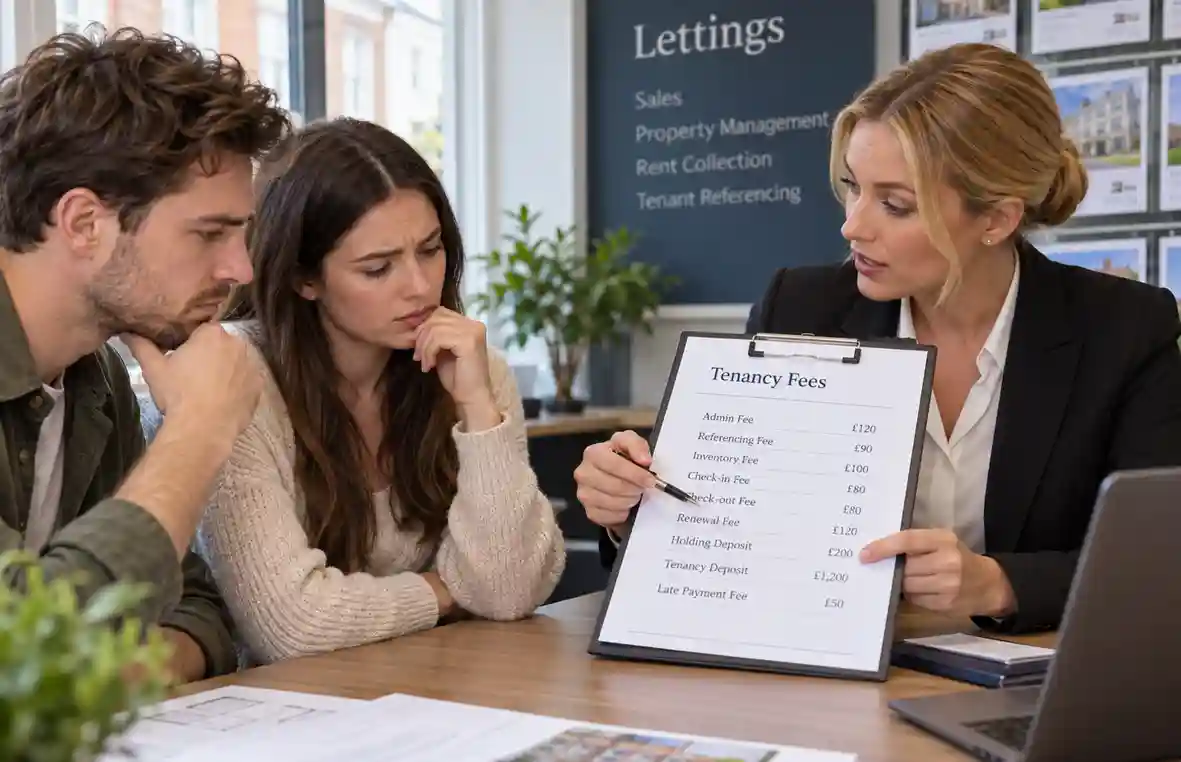
An invoice arrives asking for an “administration fee”, or a “check-out charge”, or a “contract renewal fee”, and the honest first question isn’t whether it feels reasonable — it’s whether it’s actually allowed. The answer depends heavily on where the property is, and treating “extra fees are generally banned now” as a UK-wide rule is exactly the assumption that can leave some renters paying a charge they never had to pay, and others challenging one under rules that don’t actually apply where they live.
The wording on the invoice isn’t decisive either. A payment doesn’t become lawful because it has been called a “service charge”, “processing fee” or “tenant contribution”. What matters is what the money is actually for, who is benefiting from the service being charged for, and whether the law governing that tenancy allows the tenant to be required to pay it.
England and Wales: the same principle, but not the same rulebook
In England, the Tenant Fees Act 2019 starts from a deliberately restrictive position: a landlord or letting agent can require rent and a defined list of permitted payments, and anything outside those categories is prohibited. That basic structure remains in place after the major private-renting reforms that took effect on 1 May 2026, although some of the detail around rent in advance and tenants leaving without sufficient notice has changed. The current GOV.UK Tenant Fees Act guidance for tenants reflects the post-reform position.
A refundable holding deposit is capped at one week’s rent, while the ordinary tenancy deposit is generally capped at five weeks’ rent where annual rent is below £50,000 and six weeks where annual rent falls between £50,000 and £100,000. The 2026 rules also changed how rent can be demanded before a tenancy begins: a tenant should not be required to pay rent before the tenancy agreement has been signed and, once it has, the landlord can normally require no more than one month’s rent before the tenancy starts. That is technically a rent rule rather than a fee rule, but to a tenant being asked for several thousand pounds before collecting the keys, the distinction is considerably less important than whether the demand is lawful.
Default charges are narrower than many old tenancy agreements and historic agency fee sheets make them appear. Interest on late rent cannot be charged until the rent has been outstanding for at least two weeks, and the annual rate is capped at 3% above the Bank of England base rate. A landlord can recover the reasonable cost of replacing a key, fob or other security device that the tenant has actually lost, but the cost has to be evidenced. Where the tenant asks for a change to the tenancy — adding or removing somebody, for example — the normal maximum charge is £50 unless the landlord can demonstrate that a higher reasonable cost was genuinely incurred.
The position where a tenant leaves without giving the required notice also needs separating from the old idea of an arbitrary “early termination fee”. Under England’s current assured-tenancy system, the landlord can require a payment where insufficient notice is given, but it cannot exceed the rent that would have fallen due during the minimum notice period. What the legislation still does not permit is the kind of routine charging that once appeared almost automatically on agency fee sheets: administration fees, referencing and credit-check charges, tenancy set-up costs, inventory fees, check-in and check-out charges and renewal fees.
Professional cleaning shows why looking at the substance rather than the label matters. A landlord is entitled to expect the property to be returned to an appropriate standard, allowing for fair wear and tear, and may pursue genuine cleaning costs where a tenant has left it in a worse condition. What the landlord or agent cannot do is simply impose a standard professional-cleaning fee or insist that the tenant buys a particular cleaning service as a condition of the tenancy. If an English tenant has already paid a prohibited fee, they can ask for it back, preserve the invoice and correspondence, report the matter to the local authority and, where necessary, seek repayment through the First-tier Tribunal.
Wales starts from a similar principle, but the detail should not be borrowed from England. Under the current Welsh Government guidance on letting fees, administration fees, contract-signing charges, renewal fees, inventory charges, accompanied-viewing fees, check-in and check-out charges and end-of-tenancy inspection fees are among the payments that cannot be required. Rent, security deposits, holding deposits and certain prescribed default and household payments remain permitted.
A holding deposit in Wales is also capped at one week’s rent, but Wales does not currently have England’s five-or-six-week statutory ceiling on an ordinary security deposit. The late-rent rules differ as well: Welsh regulations prevent a late-payment charge during the first seven days after rent falls due, after which interest can be charged up to the prescribed limit of 3% above the Bank of England base rate. England’s corresponding trigger is two weeks. The broad idea — that routine tenant fees have been banned — may therefore look similar on either side of the border, but some of the rules underneath it are genuinely different.
Scotland: a much simpler starting point
Scotland approaches the issue differently and, in many respects, more strictly. The long-standing prohibition on premiums means a landlord or letting agent cannot generally require an additional payment as the price of granting, renewing or continuing a tenancy. In practical terms, the starting point is unusually straightforward: other than rent, a landlord may ask for a refundable tenancy deposit of no more than two months’ rent. The Scottish Government explains the position in its guidance on rent and other charges.
That catches many of the familiar charges seen elsewhere. Referencing fees, credit checks, administration costs, inventory preparation and contract-renewal fees cannot simply be passed across to the tenant because an agent incurred them while arranging or managing the letting. Scotland also does not operate England’s regulated one-week holding-deposit model, so a demand for additional money merely to secure the property needs particular scrutiny rather than being assumed to be an ordinary part of the application process.
The deposit limit is an important reminder of why UK-wide rules can mislead in both directions. Scotland permits a refundable deposit of up to two months’ rent, so a Scottish deposit that would exceed England’s five-or-six-week ceiling may still be lawful. At the same time, a smaller additional “administration” or “holding” payment may be prohibited even if it looks much less significant. If an unlawful premium has been taken, the tenant may be entitled to recover it, and demanding prohibited charges can amount to an offence.
For a Scottish renter, then, the useful question is particularly direct: if this payment is neither rent nor the lawful refundable deposit, what exactly is the legal basis for requiring it?
Northern Ireland: not a free-for-all, and not an England-style ban either
Northern Ireland is where the shorthand “tenant fees are banned” becomes least reliable. It does not currently have England or Wales’s comprehensive permitted-payments system, nor Scotland’s near-total premium prohibition, but the opposite conclusion — that an agent can charge whatever it likes provided the fee was disclosed — is also wrong.
The important question is what the tenant is actually being asked to pay for. That became particularly clear in Loughran v Piney Rentals Limited & F5 Property Limited, where the Belfast County Court ordered an administration fee to be returned after concluding that the tenant had effectively been made to contribute towards remuneration for work carried out in connection with the landlord’s letting. The Judiciary NI summary of the decision remains particularly useful because it shows why merely putting an amount on an application form does not settle the question.
The case did not establish that every imaginable payment by a Northern Ireland tenant to an agent is automatically unlawful. It did establish something more useful: an agent cannot simply shift the cost of work it is performing for the landlord onto the tenant and assume the payment is valid because it has been called an administration fee. Current nidirect guidance on renting privately reflects that more qualified position, explaining that some fees may be charged while tenants may be entitled to recover payments relating to services carried out for the landlord.
That makes an invoice in Northern Ireland less straightforward to analyse than one in England, but not less worth challenging. If an “administration fee” appears to cover processing the landlord’s letting, preparing the landlord’s documentation or work the landlord commissioned the agent to perform, the purpose of the payment matters far more than the heading at the top of the invoice.
Northern Ireland has separately tightened the rules around deposits, with tenancy deposits capped at one month’s rent and subject to statutory protection requirements. That affects the total amount a tenant can lawfully be asked for before moving in, but it should not be mistaken for a comprehensive ban on every other tenant payment.
Reading a real charge, wherever you are
When a demand lands in front of you, asking whether £75 or £150 “sounds excessive” is rarely the best place to start. A modest prohibited fee remains prohibited, while a much larger payment may be entirely lawful if it is genuinely rent, a lawful deposit or reimbursement of a cost the legislation allows the landlord to recover.
The better starting point is to ask what the payment is for. A £150 “tenant onboarding fee” in England does not escape the Tenant Fees Act merely because the word “administration” has disappeared. A Welsh inventory fee cannot be rescued by renaming it a “property preparation charge”. In Scotland, describing an additional premium as refundable does not necessarily make it lawful. In Northern Ireland, the decisive question may be whether the tenant is being asked to pay for work the agent was really carrying out for the landlord.
There is also a meaningful distinction between a genuine cost caused by a particular tenant and a routine fee imposed on everyone. If a tenant actually loses a key, the reasonable cost of replacing it is very different from every new tenant being charged a standard “key administration fee”. Recovering an evidenced loss is not the same thing as attaching a fixed tariff to something regardless of whether that cost was ever incurred.
If a charge looks questionable, ask for it in writing and ask what, specifically, it covers. Keep the advert, fee schedule, tenancy or occupation contract, emails, invoices and proof of payment. A vague demand becomes much easier to test once the landlord or agent has had to explain what the money is actually buying.
A paid product is not automatically outside the fee rules
Guarantor services, deposit-replacement schemes, insurance and other third-party products can make this area look more complicated because the money may be paid to somebody other than the landlord or letting agent. That does not automatically take the arrangement outside the rules.
In England, current government guidance draws an important distinction between a product the tenant chooses and one they are required to buy. A tenant can voluntarily use products such as a professional guarantor service, contents insurance, a deposit-replacement product or an inventory service, but the landlord or agent cannot require the tenant to take out a loan, buy insurance or enter into a service contract simply as the price of being granted the tenancy.
The difference between “you may use this” and “you must buy this if you want the property” is substantial. A landlord may reasonably require an acceptable guarantor in appropriate circumstances, but that does not automatically give the landlord or agent the right to insist that the tenant buys one particular commercial guarantor product. A deposit-replacement scheme offered as a genuine alternative is likewise different from making that scheme the only route into the property.
Wales takes a similar approach to compulsory service contracts under its own fee legislation. More generally, these products deserve to be looked at on their financial merits even where the choice is genuinely voluntary. A monthly or annual non-refundable product may ultimately cost more than a conventional refundable deposit, so “not technically a landlord fee” should never be confused with “good value for the tenant”.
What this changes about how you read an invoice
A fee demand is not self-certifying just because it is itemised, appears in a tenancy agreement or comes from a professional letting agency. The first question is which country’s law governs the property; the second is what the payment is actually for. Only once those two questions are answered does the amount itself become the interesting part.
For tenants, that changes “this doesn’t seem fair” into a much more useful question: “what is the legal basis for requiring me to pay this?” For landlords and letting agents, the same principle works in reverse. A charge does not become compliant because it has been collected for years, because another agency charges it, or because the paperwork has given it a respectable-sounding name.
Across all four nations, the label is the least interesting part of the invoice. The substance of the payment is what matters.
This article provides general property information, not legal, financial, surveying or other professional advice for your individual circumstances. Property disputes and regulatory issues can depend on the facts, documents, location and applicable law. If significant money, property or legal rights are at risk, or you are considering an irreversible course of action, take appropriate professional advice before proceeding.

