

“How much do I actually need before I can move in?” is a simple question with a slightly less simple answer, because the money involved isn’t one payment — it’s several, each with a different purpose, a different legal status and, crucially, a different point in the process at which it can be paid.
There’s another distinction worth making at the start. The amount of cash you need available is not the same as the amount moving into the tenancy actually costs you. Your first rent payment is spent. A tenancy deposit is normally refundable. A holding deposit should either be returned or, if the tenancy goes ahead and you agree, credited towards another payment.
The three payments most renters need to budget for
A holding deposit reserves the property while referencing and other pre-tenancy checks are carried out. In England, it is capped at one week’s rent.
The normal deadline for reaching an agreement is 15 days after the holding deposit is received, although landlord and applicant can agree a different period in writing.
If the tenancy goes ahead, the holding deposit should be returned. With your agreement, that can happen by putting it towards your first rent payment or tenancy deposit instead of physically returning the money first.
A landlord or agent can keep it in certain defined circumstances — for example, if you decide not to proceed, fail a Right to Rent check, fail to take reasonable steps to enter the tenancy, or provide false or misleading information that materially affects your suitability.
If the holding deposit is being returned, it should normally be repaid within seven days. If it is being kept, the landlord or agent must explain why in writing.
GOV.UK’s Tenant Fees Act guidance for tenants explains the holding-deposit rules and permitted payments.
A tenancy deposit is different. This is refundable security against things such as unpaid rent or damage rather than a reservation payment.
In England, the maximum is generally:
- five weeks’ rent where annual rent is below £50,000; or
- six weeks’ rent where annual rent is between £50,000 and £100,000.
Where a deposit is taken for an assured periodic tenancy, it must be protected in a government-approved tenancy deposit scheme.
The important budgeting point is that this money leaves your account but is not supposed to become the landlord’s money merely because you moved in. Subject to legitimate deductions at the end of the tenancy, it should come back to you.
GOV.UK explains tenancy deposit limits and protection.
Your first rent payment is the money that actually pays for your first period in the property.
This changed significantly on 1 May 2026. A landlord or letting agent must not ask for, encourage or accept rent before both sides have signed the tenancy agreement.
After the agreement has been signed but before the tenancy starts, a tenant paying monthly can usually be required to pay no more than one month’s rent. Where rent is payable more frequently than monthly, the usual maximum is 28 days’ rent.
Once the tenancy has started, rent falls due according to the normal payment schedule in the agreement. The old practice of making an ordinary applicant produce three, six or twelve months’ rent upfront as a condition of getting the tenancy is therefore no longer generally available.
There are limited exceptions, including some accommodation arranged by councils to meet homelessness duties and certain social or supported housing.
GOV.UK’s rent-in-advance guidance sets out the current rules.
What this looks like in practice
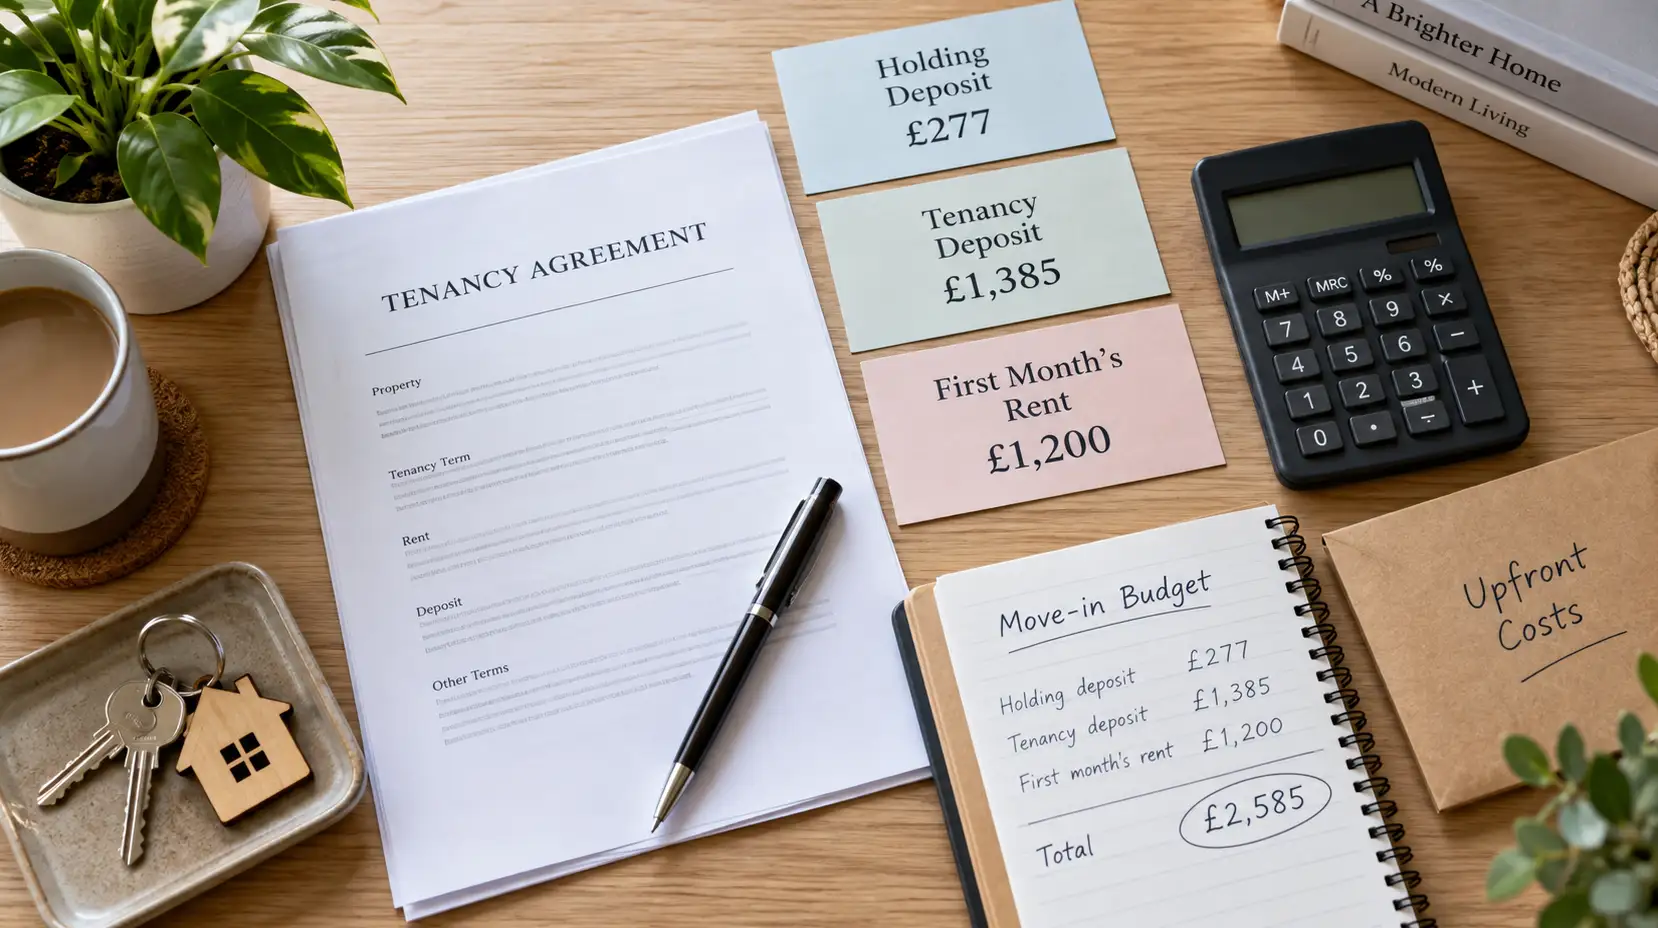
Take a hypothetical property at £1,200 a month, purely to show how the pieces fit together.
To calculate one week’s rent from a monthly figure:
£1,200 × 12 ÷ 52 = about £277
So the maximum common figures would be:
- Holding deposit: about £277
- Five-week tenancy deposit: about £1,385
- First month’s rent: £1,200
Simply adding all three produces roughly £2,862.
But that is misleading if the tenancy goes ahead and the £277 holding deposit is then credited towards the tenancy deposit or first rent payment.
In that situation, the total amount of your own money committed from reserving the property through to moving in is roughly £2,585.
Of that £2,585:
- £1,200 is your first month’s rent;
- approximately £1,385 is a refundable tenancy deposit.
That distinction matters. You need enough cash to fund both, but they are not both costs in the same sense.
A quick way to estimate what you’ll need
For a typical England tenancy below £50,000 annual rent where the landlord takes the maximum five-week deposit, a useful rough calculation is:
monthly rent × 2.15
That gets you very close to one month’s rent plus five weeks’ deposit.
So:
- £900 rent → roughly £1,940
- £1,200 rent → roughly £2,585
- £1,500 rent → roughly £3,230
The holding deposit affects when some of that money leaves your account, but if the tenancy proceeds and it is properly credited, it does not increase the final amount.
This is a budgeting shortcut, not a statutory formula. A landlord can take a smaller deposit — or no deposit at all — and the six-week cap applies at higher annual rents.
What can be taken before you sign?
This is where the 2026 rules are particularly easy to misunderstand.
Before the tenancy agreement is signed, an English landlord or agent can ask for:
- a lawful holding deposit; and
- a lawful tenancy or security deposit.
What they cannot ask for, encourage or accept at that stage is rent.
That means “pay six months now and then we’ll sign the tenancy” is no longer simply an aggressive referencing condition. For an ordinary assured tenancy covered by the new rules, taking rent before the tenancy agreement has been signed is prohibited.
Once both sides have signed, the normal first rent payment can be requested during the period before move-in.
What a landlord or agent can and can’t charge for
The Tenant Fees Act works on a fairly simple principle: if a payment connected with the tenancy is not permitted, the landlord or agent cannot make it lawful simply by inventing another name for it.
Permitted payments include:
- rent;
- a refundable tenancy deposit;
- a refundable holding deposit;
- certain payments where the tenant asks for the tenancy to be changed;
- certain payments where the tenant leaves without giving the required notice;
- relevant utilities, communications and Council Tax arrangements; and
- tightly controlled default fees for late rent and replacement keys or security devices.
If you ask for a change to the tenancy — perhaps adding or removing somebody — the normal permitted charge is up to £50, although a landlord can charge more if they can evidence genuinely higher reasonable costs.
Late-payment charges are restricted too. Rent must be at least two weeks overdue before interest can be charged, and the rate is capped at three percentage points above the Bank of England base rate.
A charge for replacing a lost key, fob or security device must reflect the reasonable replacement cost and the landlord must be able to evidence it.
What landlords and agents cannot generally charge tenants for includes familiar old-style fees such as:
- administration fees;
- reference or credit-check fees;
- viewing fees;
- check-in or check-out charges; and
- compulsory paid services that are not on the permitted list.
That includes requiring a tenant to buy a particular insurance, loan, inventory service or other third-party product as a condition of the tenancy.
Professional cleaning is a useful example. A landlord can expect the property to be returned to an appropriate standard and can pursue legitimate cleaning costs where the tenant leaves it worse than required. What they cannot do is simply impose a compulsory professional-cleaning fee as another routine tenancy charge.
If a requested payment does not clearly fit one of the permitted categories, asking “What permitted payment under the Tenant Fees Act is this?” is a perfectly reasonable question before handing over the money.
The wider cost of moving, briefly
Everything above is about the money directly involved in securing and starting the tenancy.
It is not the full cost of moving home.
Removals, furniture for an unfurnished property, utility balances, broadband installation, parking permits, contents insurance and the inevitable smaller purchases involved in setting up a new home all sit outside this calculation.
Those wider expenses belong properly in our Moving Home section. Here, the useful number is what you need to get from application to keys without confusing refundable security money with money that has actually been spent.
The rules are different elsewhere in the UK
The figures above are England-specific.
In Scotland, a private landlord can generally require a refundable deposit of up to two months’ rent. Scottish law also prohibits premiums charged in addition to rent and a lawful refundable deposit, so the fee structure is materially different from England’s.
In Wales, holding deposits are permitted and capped at one week’s rent under the Welsh letting-fees regime. Many of the old-style administration, viewing, check-in and check-out fees are prohibited there too, but Welsh occupation contracts operate under their own legislation rather than England’s Tenant Fees Act framework.
In Northern Ireland, a tenancy deposit cannot exceed one month’s rent and must normally be protected in an approved Tenancy Deposit Scheme within 28 days of being received.
So a renter moving between UK nations should not assume that England’s five-week deposit cap, holding-deposit rules or 2026 rent-in-advance restrictions automatically travel with them.
What should make you pause before paying
You do not need to know the legislation by heart. A handful of situations are enough to justify stopping and asking for an explanation.
Be cautious if you are:
- asked to pay any rent before the tenancy agreement has been signed;
- asked for a holding deposit above one week’s rent;
- asked for a tenancy deposit above the applicable statutory cap;
- charged an administration, referencing, viewing or check-in fee;
- required to buy a particular commercial product or service as a condition of renting; or
- pressured to transfer money without a clear written explanation of what it is for.
None of that means every unusual payment request is necessarily fraudulent. But a legitimate landlord or letting agent should be able to tell you clearly, in writing, what you are paying, why it is permitted and what happens to the money if the tenancy does not proceed.
And before transferring substantial money, make sure you know who you are paying and that the property and letting arrangement are genuine.
This article provides general information about upfront tenancy payments in England as they stood in September 2026 and does not constitute legal or financial advice. Different rules can apply to particular tenancy and accommodation types. If you are asked for a payment you believe may be prohibited, consider checking with Citizens Advice, Shelter or your local council before paying it.

