

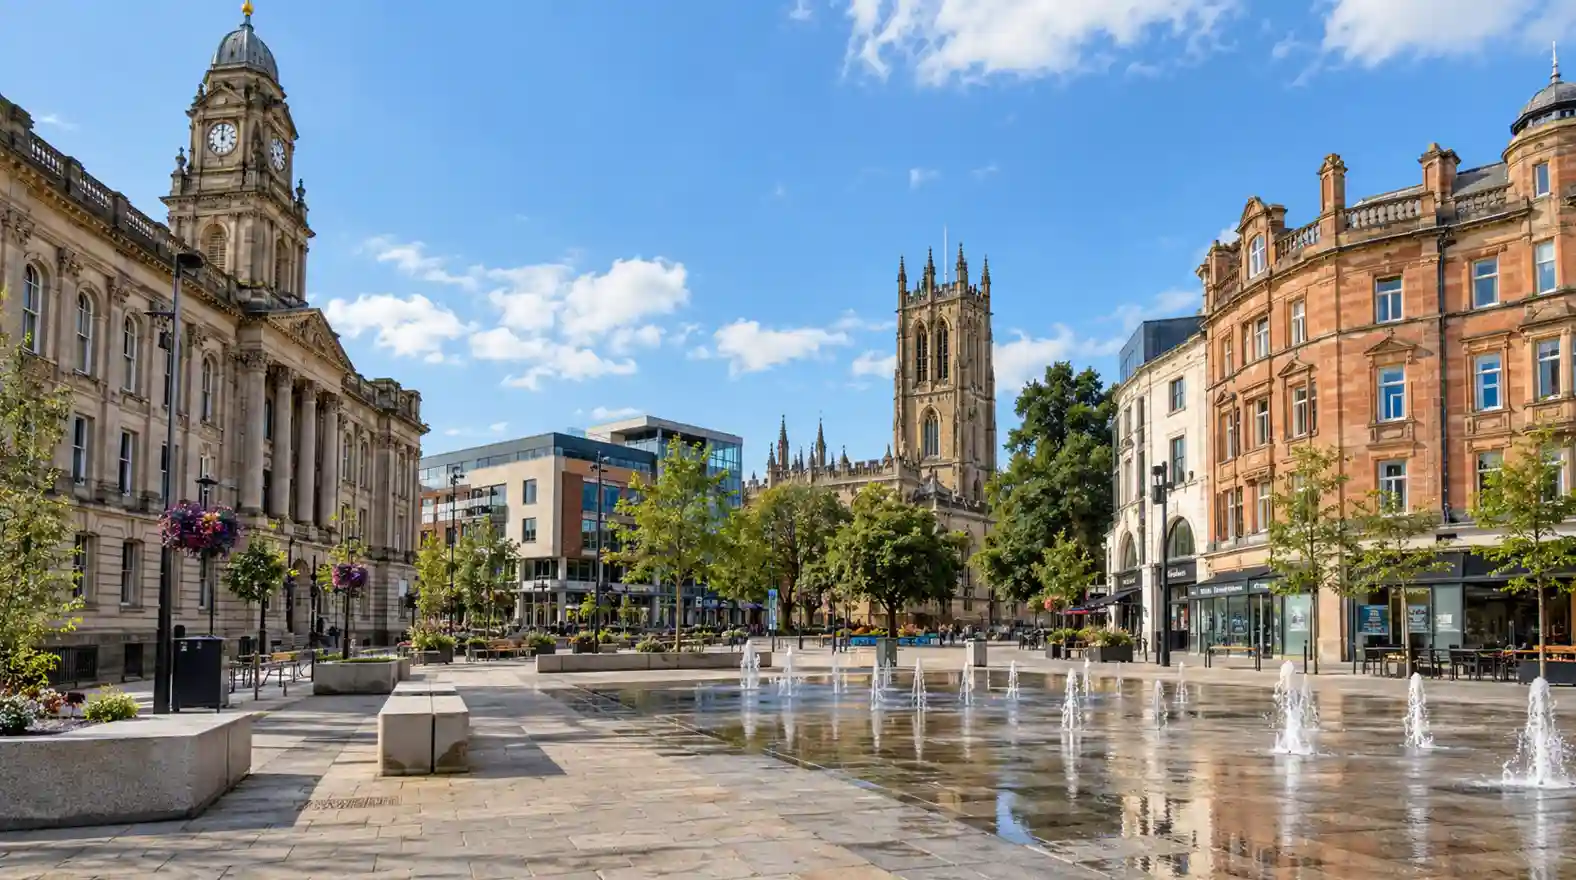
Great British Railways’ headquarters is heading for a new office at Becketwell. A government-backed occupier could solve one of regional development’s biggest problems. It does not, on its own, make the building financially viable.
Regional office development outside the biggest cities has a familiar chicken-and-egg problem. Occupiers want new, efficient Grade A space; developers and lenders are reluctant to build it without a tenant; and tenants can be reluctant to commit to a building that does not yet exist. Many towns and cities have seen little speculative office development because the anticipated rents struggle to justify the cost and risk of construction.
Derby now has a named prospective occupier. On 15 October, the Department for Transport confirmed Becketwell, a brownfield regeneration site in the city centre, as the location for Great British Railways’ headquarters. The plan is for a new office building, 3 Springwell Square, on the site of the former Duckworth Square shopping precinct, accommodating up to 450 GBR staff.
Derby itself was selected as the headquarters city in 2023. The new announcement settles the intended site, following consideration of an alternative location near the railway station.
For the commercial property market, the important question is not whether this is welcome news for Derby. It is what kind of risk the announcement removes, what remains unresolved and whether bringing a major public-sector occupier into one development can encourage private investors to commit money elsewhere in the city.
What has been confirmed, and what has not
The announcements from the public bodies involved line up on the core facts but differ in emphasis, and the differences matter.
Derby City Council describes the building as approximately 106,000 sq ft of Grade A offices, an eight-storey development fronting a public square. Its earlier planning announcement on 6 October gives a more precise figure of 106,544 sq ft and confirms that an application had been submitted for the development.
The proposal forms part of the wider £200 million Becketwell regeneration scheme. That figure describes the broader regeneration programme, not a confirmed construction budget for the new office building.
The East Midlands Combined County Authority describes Becketwell as the Transport Secretary’s preferred headquarters location, whereas the Department for Transport and city council present the site selection as confirmed. The practical position is that Becketwell has been publicly selected, while the detailed arrangements required to deliver and occupy the building remain to be completed.
The council also makes clear that the funding structure is not settled. It says the public sector has a crucial role in securing the money needed to unlock the scheme, and that it is working with the combined authority on the most appropriate partnership arrangement. The developers are St James Securities and Peveril Securities.
Nor are the occupational terms publicly established. No signed agreement for lease, rent, lease length or break provisions have been disclosed in the material reviewed.
That distinction matters because a confirmed intention to occupy is not identical to a legally enforceable commitment to pay rent. The latter is what lenders and investors would ordinarily examine when deciding how much income is secure and on what terms they can finance the development.
There is another question hidden in the building’s size. The government says the site will accommodate up to 450 GBR staff, while the earlier planning announcement describes a building potentially supporting up to 1,000 jobs when fully operational.
Those figures are not necessarily contradictory. One concerns GBR’s announced staffing capacity; the other concerns the potential capacity of the proposed office development. They do, however, leave unanswered how much accommodation GBR will actually require and whether the scheme is intended to accommodate other occupiers.
A building with a prominent headquarters tenant is not necessarily a building with every floor let. Until its occupational arrangements are disclosed, the extent to which GBR will underpin the entire development remains uncertain.
What an anchor occupier actually de-risks
For anyone financing a speculative office, one of the biggest risks is letting: how long the building will sit empty, what rent it can achieve, and what incentives will be needed to attract occupiers.
A firm long-term commitment from a credible government-backed organisation can transform that calculation. Instead of depending entirely on finding tenants after construction, a developer may be able to demonstrate future contracted income before committing to the full cost of the project.
That matters to both lenders and investors. A completed building supported by an enforceable lease can be valued with reference to its income, the tenant’s financial strength and the security of that income. A development without a committed tenant depends much more heavily on assumptions about the future market.
In principle, GBR therefore offers something valuable: the prospect of turning at least part of a speculative development into a pre-let office scheme.
But the details determine how much risk disappears.
A lender would need to know which legal entity is taking the lease, what rent it has agreed to pay, how long the obligation lasts, whether there are break options and what conditions must be satisfied before the tenant becomes bound. Rent-free periods, contributions towards fitting out the offices and other incentives could also affect the financial calculation.
The involvement of a public-sector organisation may make the covenant more attractive, but it is not a substitute for examining the actual contractual obligation. GBR is still being established as part of the government’s railway reforms, and the eventual leasing arrangements have not been published.
The announcement therefore improves the scheme’s prospects without establishing the value of a completed investment or proving that the proposed accommodation is fully let.
What a pre-commitment also cannot do is make construction costs viable if the rent and other funding do not support them. Regional office developments face a difficult equation: occupiers may want buildings with the same modern specifications and environmental performance as those in larger markets, but achievable rents do not necessarily rise in proportion to construction costs.
That gap is one reason public participation can become important in regeneration projects. It is also why the council’s acknowledgement that funding still needs to be structured deserves as much attention as the government’s announcement of the occupier.
Where the risk sits now
The interesting commercial question is who will end up carrying the remaining risks: planning, construction costs, delays, the building’s long-term value and any accommodation not committed to GBR.
The answer depends on the funding and ownership structure eventually agreed.
If the public partners provide capital through a grant, they may improve the development’s viability without owning the finished property. The developer would then have less capital to recover through rent or disposal proceeds, but public money would have been committed to making the scheme happen.
If a public body funds and owns the building, it could retain the value of a well-let commercial asset and potentially receive rental income. It would also take on responsibilities and risks associated with ownership, including future maintenance, reletting and changes in the building’s value.
Alternatively, a privately owned and funded scheme might rely on a sufficiently strong pre-let to support development lending. Public expenditure could then be directed towards infrastructure or other enabling works rather than the building itself.
These are possible structures, not confirmed proposals for Becketwell. No published agreement establishes which will be adopted or the share of risk each party will bear.
For local taxpayers, the distinction is significant. An office building may be a worthwhile public investment, especially if it helps bring activity back to a neglected city-centre site. But the strength of the proposed tenant does not remove the need to demonstrate value for money or explain how construction overruns and future ownership liabilities would be managed.
The eventual financing arrangements will also matter to private investors. Public funding that closes a genuine viability gap can help deliver a building the market would otherwise struggle to provide. Whether it encourages further investment will depend partly on the rents achieved, the quality of the completed scheme and the extent to which nearby developments can succeed without equivalent support.
There is a further risk particular to a new public-sector organisation: policy and organisational change. GBR’s eventual workforce, accommodation requirements and working patterns could evolve as the railway reforms progress.
A suitably drafted long-term lease could protect an investor’s income despite changes in the occupier’s use of the building. It would not guarantee that the offices remain fully occupied or that the surrounding businesses receive the level of daily activity originally anticipated.
That distinction between income security and actual occupation is important to the regeneration argument.
The city-centre effect, and its limits
The wider case for Becketwell rests on more than office rental income. Bringing hundreds of staff into the city centre could support cafés, shops, transport services and other businesses while reinforcing an area that already includes the Condor build-to-rent apartments, Springwell Square and the Vaillant Live events venue.
The government estimates that locating the headquarters at Becketwell could generate £151 million in regional economic benefits.
That figure has a research background. An economic impact assessment prepared by CBRE, reported by Marketing Derby in May, estimated that the Becketwell option could generate between £107 million and £151 million in gross value added during construction and operation. It also modelled a wider employment impact, rather than simply counting GBR staff.
These figures are forecasts, not money already secured for Derby or cash income that the council can spend. They incorporate assumptions about the activity created by development and occupation, and those assumptions will matter when assessing the results.
A separate figure of up to £100 million for Derby itself appears in the council’s planning announcement. That is not necessarily a contradiction with a larger regional estimate, but the published summaries do not provide enough consistent methodological detail to treat the figures as directly comparable.
There is also the question of how much activity will be genuinely additional.
Employees relocating from offices elsewhere in Derby may increase spending around Becketwell while reducing it near their previous workplaces. Others could represent newly created positions or work moving into the city from elsewhere. Those outcomes have different implications for the local economy.
The new offices could also operate below their stated staffing capacity on a typical working day. Flexible working arrangements, the eventual size of the organisation and the distribution of employees across locations will influence the number of people actually travelling to Becketwell.
For surrounding businesses, 450 staff on an organisational plan is therefore not the same thing as 450 additional customers arriving in the city centre every weekday.
The related announcement of up to 600 rail foundation apprenticeship places is welcome for skills development, but it should not be added to the headquarters employment figure. The programme will operate nationally over four years, with its first cohort based in Derby. Those places are not 600 permanent jobs at 3 Springwell Square.
None of these qualifications removes the potential value of a major public-sector headquarters. They establish the distinction between an encouraging investment announcement and the additional economic activity that must eventually materialise if the regeneration claims are to be realised.
What it means for Derby’s existing offices
A new Grade A building with a prominent occupier could change Derby’s office market, but not necessarily in the straightforward way suggested by some of the regeneration commentary.
It would establish a visible new benchmark for office quality, environmental performance and city-centre accommodation. That may help local agents demonstrate what modern space can offer and could encourage other occupiers to reconsider the city centre.
Yet Derby’s existing office market is not uniformly weak.
Research published by commercial property agency Innes England in February 2026 reported that Derby recorded its highest office take-up for 12 years during 2025. Around 81% of that take-up was in Grade B accommodation.
That is an important counterpoint. The city was already recording substantial occupational activity before the Becketwell decision, and much of it involved existing, rather than newly developed, offices.
The figures do not prove that Derby has sufficient modern Grade A accommodation. Equally, they do not establish that every older building faces obsolescence or that demand for a single prestigious headquarters will translate into demand for several more new office developments.
For commercial landlords, the consequences could move in different directions.
A successful new headquarters may strengthen perceptions of Derby as a business location, support surrounding amenities and draw attention to the quality of accommodation available in the city. Existing landlords could benefit from greater interest in nearby offices, particularly where their buildings offer a different price point or type of space.
But if occupiers move from older offices into newer accommodation without an equivalent increase in demand, vacancies could simply shift elsewhere. Owners of dated stock might then face greater pressure to invest in refurbishment, improve energy performance, adjust rents or consider alternative uses where planning and commercial conditions permit.
The effect is likely to be different for a modern office requiring modest refurbishment and a building whose layout, operating costs or physical condition make upgrading difficult.
For agents and valuers, the most useful indicators will be actual rents, incentives, occupation levels and subsequent transactions. A government-backed headquarters may create confidence, but it does not by itself establish the rental values or investor yields that other buildings in Derby can achieve.
The real test of regeneration is whether the new development improves the market around it rather than merely concentrating occupiers and investment in one building.
What to watch next
There are several decisions still to come before the project becomes a completed commercial property investment.
The planning application submitted in October will need to be determined. The public partners must settle the funding and delivery arrangements, including how the development will be paid for and who will own it. The occupational agreement will also be important, particularly the amount of space GBR takes, the contractual rent and the duration and conditions of its commitment.
The construction timetable remains a target. The government’s 15 October announcement anticipates work beginning in early 2027, while the earlier planning announcement referred to summer 2027. Both identify spring 2029 as the intended completion period. That difference does not establish a delay, but it underlines why the programme should not be treated as a fixed contractual schedule.
For developers, investors and commercial agents in Derby and the wider East Midlands, subsequent private investment will be at least as revealing as the progress of 3 Springwell Square itself.
Do other businesses commit to the city centre? Does demand increase for new or refurbished offices? Can further development proceed on viable terms, and will existing premises continue attracting occupiers rather than being left behind?
Those outcomes would provide better evidence of a successful regeneration effect than the announcement of an intended headquarters alone.
For other regional cities facing similar office-development challenges, Derby’s experience offers a lesson worth following. A credible anchor occupier can change the economics of a scheme by reducing uncertainty over future demand and, once appropriate contracts are in place, providing the income against which investors and lenders can assess it.
But the development costs, funding requirements and remaining occupational risks still have to add up.
Derby has secured the prospect of a substantial public-sector anchor. Whether that becomes a catalyst for private regeneration will depend on what is built, what it costs, who pays for it and what follows.
This article provides general commercial property news and analysis based on information available as at 16 October 2026. The proposed development remains subject to planning, financing, contractual and construction arrangements. Economic benefits, staffing levels, building capacity and completion dates are announced estimates or intentions rather than guaranteed outcomes. Nothing in this article constitutes investment, valuation, legal or financial advice.

