

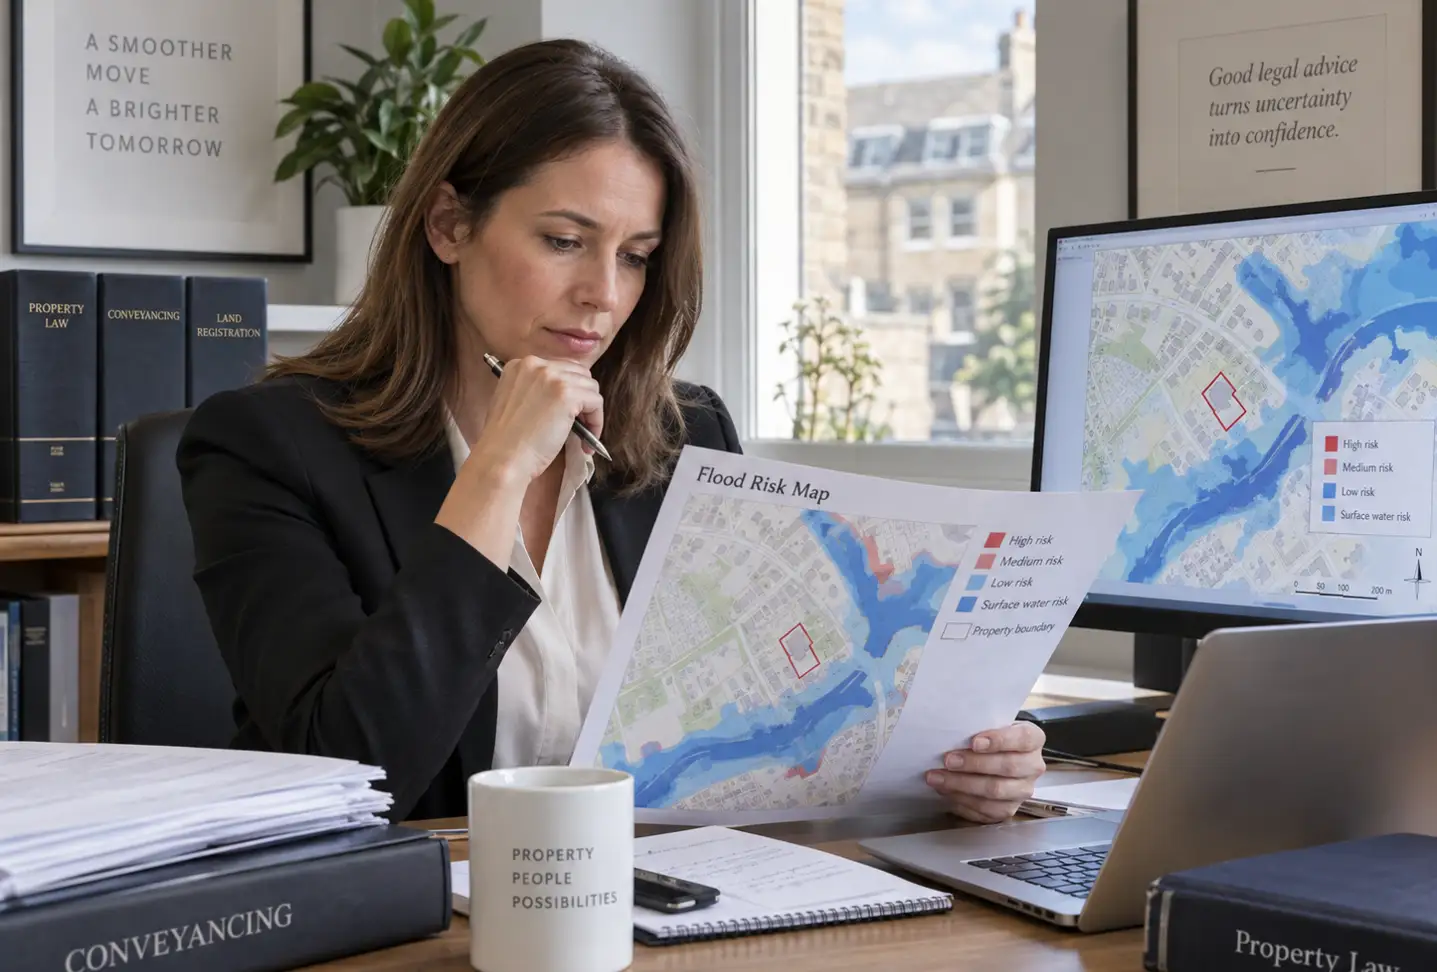
A conveyancing search comes back, or you check an online flood map out of curiosity, and there it is: some form of flood risk attached to a house you were otherwise ready to buy.
The honest answer isn’t “never buy a flood-risk property,” and it isn’t “if it’s never flooded before, don’t worry about it” either. A flood-risk flag is information that needs interpreting, not an automatic verdict.
The important question is what the risk actually means for this house — physically, financially and eventually when you come to sell it again.
Not all flood risk is the same risk
The first thing worth establishing is what kind of flooding is actually being flagged, because the practical implications differ meaningfully between them.
River flooding happens when a river or other watercourse exceeds its capacity. It is often comparatively well mapped and, in many locations, supported by warning systems.
Coastal flooding involves the sea and tidal conditions and brings its own long-term considerations, particularly where changing sea levels and coastal processes affect future risk.
Surface-water flooding occurs when intense rainfall cannot drain or soak away quickly enough and instead flows or collects across the ground. It can affect houses nowhere near a river, which is precisely why buyers sometimes find it surprising.
The Environment Agency’s latest national assessment identifies around 4.6 million properties in England in areas at risk of surface-water flooding, including roughly 1.1 million in areas classed as high risk. That’s substantially more than earlier assessments identified, but the increase shouldn’t be read as though millions of homes suddenly became physically riskier overnight: improved data, modelling and understanding are part of the change too. The Environment Agency also expects climate change to increase the number of properties exposed to surface-water risk over coming decades.
The Environment Agency’s national flood-risk assessment explains the current figures.
Groundwater flooding occurs when groundwater levels rise sufficiently to affect the surface or structures below it. The risk depends heavily on local geology and groundwater conditions and can be particularly relevant to basements, cellars and low-lying construction. Unlike a fast-moving surface-water event, groundwater can sometimes remain elevated for a prolonged period.
Reservoir flooding is mapped separately and describes areas potentially affected in the unlikely event of reservoir failure. It should therefore be interpreted differently from an ordinary annual river or surface-water probability.
The point isn’t to become a hydrologist before buying a house. It’s to establish what mechanism the search is actually warning you about, because a medium surface-water flag, a history of repeated internal river flooding and land shown within a reservoir-failure extent are three very different propositions.
Don’t confuse a flood map with a diagnosis of the house
This is one of the most useful things to understand before reacting to a colour on a screen.
Government flood maps and many environmental searches are fundamentally screening tools. They model the risk to an area or piece of land; they don’t necessarily tell you the probability that water will cross the threshold of one particular house.
England’s official long-term flood-risk service says this explicitly: it provides the long-term risk for an area, not the likelihood that an individual property will flood.
That distinction matters because two neighbouring houses can have quite different practical exposure. One may sit slightly higher. One may have a raised finished floor level. Water may naturally flow along one side of a plot. A wall, slope or drainage feature may change the route it takes. An extension may sit lower than the original house.
There is another source of confusion in England: a planning Flood Zone isn’t necessarily the same thing as the long-term flood-risk classification you see on the Environment Agency’s public risk service. Planning Flood Zones have a particular planning purpose and primarily concern river and sea flooding; the long-term risk service considers other sources as well and, for rivers and the sea, takes existing flood defences into account.
So a buyer seeing “Flood Zone 2”, “medium risk” and “surface-water risk” in different documents shouldn’t assume those three phrases are interchangeable descriptions of the same thing.
The question is always what the particular dataset is measuring.
Is it the house, or the plot?
A search result flagging risk doesn’t automatically mean the living accommodation is expected to flood.
It may relate primarily to the bottom of the garden. It may follow a shallow surface-water route across the driveway. It may affect the garage rather than the house. Or the building itself may sit directly within the modelled pathway.
Access matters too.
A house can remain physically dry while the only road leading to it becomes impassable. That can still affect everyday practicality, emergency access, insurance perceptions and ultimately how attractive the property is to a future buyer.
This is why the map needs to be looked at alongside the actual site rather than reduced to a single risk word.
Where the flood flag is significant, ask the surveyor to look specifically at the relationship between the building and the surrounding ground: floor levels, external falls, low points, basement construction, drainage, air bricks, thresholds and any visible flood-resistance measures.
A normal home survey is still a visual building-condition inspection rather than a specialist hydrological assessment, but telling the surveyor about the flood concern before the visit makes it much more likely that relevant physical clues receive proper attention.
Current risk, and how it might change
Flood risk isn’t static.
England’s latest national modelling now provides climate-change information alongside present-day risk, and similar long-term thinking increasingly forms part of flood management elsewhere in the UK.
That doesn’t mean a model showing increased risk several decades from now predicts that a particular house will flood in a particular year. It means the conditions behind the existing probability are expected to change.
That matters to a buyer because you’re not purchasing the property for the afternoon on which you read the search. You may own it for ten or twenty years, insure it repeatedly during that period and eventually sell it into a market using more sophisticated flood-risk information than buyers use today.
A low or manageable present-day risk is therefore reassuring, but it shouldn’t make clearly worsening future risk irrelevant.
Equally, a climate projection shouldn’t be treated as certainty. It belongs in the judgement alongside current exposure, flood history, defences, resilience, insurance and price.
What “it’s never flooded” actually tells you
A clean flood history is genuinely useful evidence. It just isn’t the same thing as proof that flooding cannot happen.
In England and Wales, the current Law Society TA6 Property Information Form specifically deals with flooding. The seller’s answers are useful because buyers can rely on information supplied through the conveyancing process, but sellers can only report what they actually know. They may not know what happened before they owned the property.
The Law Society’s current TA6 explanatory notes expressly tell buyers to consider flood history and, where appropriate, obtain further risk assessment.
So don’t stop with “the seller says it’s never flooded”.
Look for consistency between the seller’s answers, the search, any available insurance history, what neighbours know, physical evidence at the property and historical records.
In England, the Environment Agency can also provide available flood-history information for the area around an address, although its records aren’t complete for every location. Lead Local Flood Authorities may have their own records or published investigations of significant local flooding.
An absence of recorded flooding still matters. But it means there is no known history in the evidence you’ve found, not that the modelled event cannot occur.
The insurance question deserves real attention before you commit
This is one of the most practically important parts of the decision.
Don’t rely on somebody saying “insurance should be fine” because the current owner has a policy.
Obtain actual quotations for the exact address, ideally from more than one insurer, before you become contractually committed to buying.
Look beyond the annual premium. A policy can appear affordable while carrying a very high flood excess or restrictive flood terms. Check whether flood is covered, what the flood excess is, whether alternative accommodation is included and whether any property-level flood-resilience measures have to be maintained as a condition of cover.
If several mainstream insurers quote normally, that’s useful evidence about the current insurance market’s view of the property. If quotations repeatedly come back with unusually large excesses, exclusions or refusals, that tells you something important too — even if you’ve personally decided you’re comfortable with the physical flood risk.
For eligible homes, Flood Re can make a substantial difference. The scheme operates behind insurers to support the availability and affordability of flood cover for qualifying residential properties.
But “built before 2009” is only one of several eligibility conditions, not a blanket guarantee that a property qualifies. Among other requirements, qualifying homes must satisfy the scheme’s residential, occupancy, Council Tax and policy criteria. Flood Re’s current eligibility criteria are worth checking rather than assuming the scheme will solve an insurance problem after you’ve bought.
Newer homes completed from 1 January 2009 generally aren’t eligible for Flood Re, which makes testing the real insurance market particularly important where a newer property carries significant flood risk.
Will a lender actually mortgage it?
A flood-risk flag doesn’t automatically make a property unmortgageable.
Mortgage lenders usually require buildings insurance to be in place, and flood risk can become a lending issue where appropriate cover is difficult to obtain or where the lender’s valuer considers the risk materially affects the property.
RICS specifically warns buyers that flood risk can affect insurance, property value and mortgageability.
Different lenders can also have different appetites for the same property, which is one reason a single lender’s reaction shouldn’t always be mistaken for a universal market judgement.
But there’s an important difference between one lender declining for its own policy reasons and a property for which insurance and mainstream lending are consistently difficult across the market.
The latter deserves much more caution.
Where there is a meaningful flood flag, tell your mortgage broker or proposed lender early rather than allowing it to emerge for the first time during valuation or underwriting. If the purchase only works with a particular specialist lender, unusually high insurance excess or narrow set of insurers, that constraint belongs in your buying decision and eventually in your thinking about resale.
How this might look to the next buyer
Even if you’re comfortable with the risk, the next buyer may not be.
That matters because future purchasers will probably see broadly the same flood information you can see today — potentially with newer modelling layered on top.
Flood risk can affect value, but there isn’t a responsible national rule saying a flood-risk house should simply be discounted by 5%, 10% or 15%.
RICS guidance on flooding says the effect on value can range from very small to significant, depending on the property’s location and construction, its history, local and property-level defences, insurance and the nature of the risk.
That’s a much more useful way to think about it.
A house that sits within a broad low-level mapped area, has never flooded, remains straightforward to insure and mortgage and has good resilience may suffer very little market penalty.
A property with repeated internal flooding, expensive insurance, a large flood excess and buyers regularly walking away from it is an entirely different proposition.
The right question therefore isn’t “what percentage should I knock off because the map is blue?”
It’s whether the price compensates you appropriately for the specific disadvantages this particular risk creates.
Resilience measures help, but don’t erase the underlying risk
Existing flood-resistance and resilience measures are a positive, provided they’re the right measures for the actual source of flooding.
Flood doors and barriers, automatic or protected air bricks, non-return valves, raised sockets and resilient internal finishes can all reduce either the chance of water entering or the scale of the damage if it does.
But their mere presence doesn’t prove the problem has been solved.
Ask why they were fitted. Were they installed after a previous flood? Is there documentation? Who designed them? Are removable barriers still present and serviceable? Have non-return valves been maintained? Do measures around doors simply divert water towards another vulnerable opening?
A well-designed property flood-resilience scheme is very different from a few visible flood products installed without a coherent understanding of the water route.
And resilience changes the consequence of flooding much more readily than it changes the underlying probability shown by the wider flood model.
When it’s worth paying for more investigation
Not every search flag justifies commissioning another specialist report.
If the risk is very low, clearly relates to land remote from the house, there’s no flood history, insurance is straightforward and the ordinary survey raises nothing concerning, further specialist work may add little.
The equation changes where the risk classification is significant, the property has flooded before, the search and physical site appear inconsistent, insurance terms are problematic, the house has a basement or unusually vulnerable construction, or you’re simply contemplating spending enough money that the uncertainty itself is uncomfortable.
RICS is explicit that flood maps provide a general indication rather than property-specific certainty and that a suitably experienced chartered surveyor can provide a more detailed pre-purchase flood assessment.
A specialist assessment can examine the property rather than merely the postcode: topography, likely flow routes, threshold and floor levels, flood depths, local drainage, historic events, existing protection and the consequences if flooding actually occurs.
That’s much closer to the information you’re trying to buy.
And don’t expect an ordinary Level 2 or Level 3 Home Survey to replace it. A home survey can identify visible defects, risk factors and evidence requiring further investigation, but a specialist flood-risk assessment answers a different question.
A genuine decision framework
By this stage, the search itself should no longer be the thing making the decision. The fuller evidence should be.
A useful way of looking at the position is:
| The evidence looks more like this… | What it means for the decision |
|---|---|
| Risk mostly affects land rather than the building; no known internal flood history; insurance and mainstream mortgage readily available; manageable future risk | Potentially manageable — the flood flag alone needn’t stop the purchase |
| Meaningful risk to the building or access; unclear history; conflicting information; insurance available but expensive or with a high excess | Investigate further — this is where specialist assessment can change the decision |
| Repeated internal flooding; significant or worsening exposure; difficult or restricted insurance; lender concerns; no convincing mitigation; price doesn’t reflect any of it | A serious reason to reconsider or renegotiate substantially |
That isn’t a mechanical scoring system. A house doesn’t become “safe to buy” because it has two reassuring boxes and only one worrying one.
What it does is put the search flag back where it belongs: as the start of a judgement rather than the judgement itself.
The central questions remain the ones that matter in real life. Is the building itself likely to be affected? Has it actually flooded? What happens to access? Is the risk getting worse? Can you insure it on terms you’re comfortable carrying every year? Will a mainstream lender accept it? What measures are already in place? And will another buyer be asking all these same questions when it’s your turn to sell?
A property that answers those questions reasonably well can still be an entirely rational purchase, and occasionally an attractive one precisely because a flood-risk flag frightens away buyers who never investigate beyond the map.
But a discount isn’t automatically a bargain.
If the only reason the price looks attractive is that you’re accepting difficult insurance, restricted lending, repeated disruption and a smaller future buyer pool, the lower purchase price may simply be the market correctly pricing the problem.
The right purchase isn’t therefore the house with no flood-risk colour on a map. It’s the one where you’ve established what the risk actually means, decided that you can live with it, and are paying a price that reflects it.
This article provides general property information, not advice on a specific purchase. Official flood mapping, conveyancing practice, insurance and property law differ across England, Wales, Scotland and Northern Ireland, and lender and insurer criteria change over time. Verify the current risk and insurance position for the individual property before becoming contractually committed, and obtain specialist flood-risk, surveying, legal or mortgage advice where the evidence warrants it.

