

Every bid on a development site is, whether the bidder frames it this way or not, a bet on a set of assumptions that haven’t happened yet.
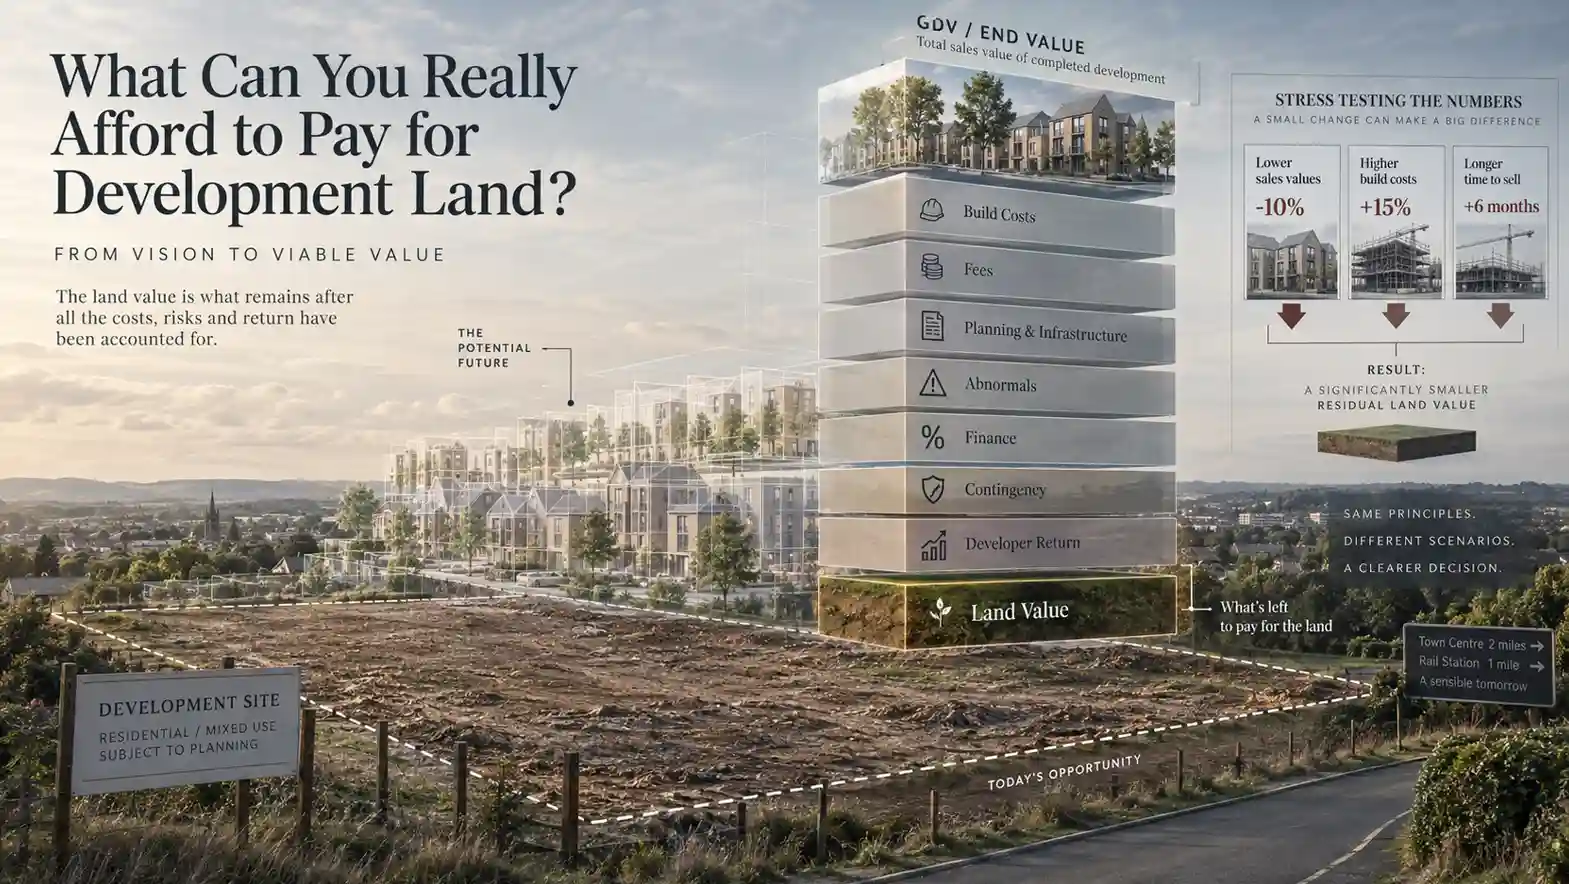
The base appraisal says the site supports a land value of £X. What that number rarely reveals — and what separates a robust acquisition decision from one built around a narrow base case — is how quickly that £X changes when sales values soften, build costs move or delivery slips by a year.
Land sits at the residual end of the development equation. While the acquisition price is still being determined, that is precisely why relatively modest changes elsewhere in the appraisal can produce disproportionately large changes in what the site can support. Once the land has actually been bought at a fixed price, however, the economics change: the land price no longer moves to absorb the shock. Developer return, capital exposure or ultimately the viability of the scheme does.
That is why the downside belongs in the appraisal before the bid, not after it.
The residual sits last, which is exactly the problem
The mechanics are familiar to anyone bidding on land: completed development value, less construction, professional fees, infrastructure, planning obligations, abnormal costs, finance, sales or letting costs, contingency and the required developer return leaves whatever residual amount remains for the land.
RICS describes the same underlying residual principle: gross development value less total development costs, including finance and developer’s profit, produces the residual land value. It also cautions that the result can be highly sensitive to comparatively small movements in the assumptions.
RICS — Valuation of development property
What matters here isn’t restating the formula. It’s recognising what its structure implies. If a £15 million scheme loses £750,000 of GDV, that is only a 5% movement in development value. If the original residual available for land was £1.5 million, however, the same £750,000 represents half of that residual before any other assumption has changed. That is the leverage built into residual land value.
There is also an important distinction between a valuation of development land and a developer’s acquisition appraisal. A valuation is an opinion of value produced for a defined valuation purpose. A bidder is asking a different question: what can this business afford to pay given its finance, required return, delivery strategy, tax position, risk appetite and alternative uses of capital? Those numbers may not be identical.
RICS also recommends cross-checking a residual result against appropriate comparable land evidence where possible. If an appraisal produces a land figure materially above or below what comparable sites are transacting for, that does not automatically make the appraisal wrong — but the difference should be explainable rather than ignored.
Current conditions are already demonstrating this
This is not a theoretical sensitivity.
Knight Frank’s Q2 2026 Residential Development Land Index, which tracks residential development land in England, recorded greenfield land values falling 5.5% during the quarter and 3% over the year, while urban brownfield values fell 2.5% in the quarter and 5% annually. Its research attributes the pressure to weaker sales rates, elevated build costs and continuing uncertainty around scheme viability, with developers becoming increasingly selective about the sites they pursue.
Knight Frank — Residential Development Land Index Q2 2026
Construction pressure has moderated substantially from the exceptional inflation seen earlier in the decade, but it has not disappeared. BCIS’s Private Housing Construction Price Index recorded annual housebuilding cost inflation of 2.3% in the first quarter of 2026.
BCIS — Private Housing Construction Price Index
Neither figure establishes what an individual development site is worth. They demonstrate something more useful for a bidder: the assumptions driving development economics can move independently, and land value can react much more sharply than the percentage movement in any single input might suggest.
The residential market provides a particularly clear illustration because land-value indices are available, but the residual mechanism is not confined to housebuilding. Commercial and mixed-use schemes are exposed to their own combinations of construction cost, programme, finance and value risk, with rents, letting periods, incentives, stabilised income and exit yields potentially carrying far more weight than residential sales values.
Sensitivity is not a formality — it’s the core of the exercise
A base appraisal that clears the required return tells you relatively little on its own. What matters is how far the assumptions can move before the acquisition no longer produces an acceptable outcome, and which assumptions the site is most exposed to.
The stress should be credible rather than theatrical. Sales values or rents need testing against a downside supported by the market the scheme will actually enter. For income-producing development, yield movement may be just as important. Build-cost scenarios should reflect the procurement route, programme and current evidence rather than a percentage copied from somebody else’s appraisal. Finance needs testing not simply through a different interest rate but through the amount and duration of borrowing.
Programme deserves particular attention because time affects several lines at once. A six- or twelve-month delay can postpone receipts, extend finance, hold capital for longer and potentially move the project into a different sales, rental or construction market. A proper appraisal therefore needs to be time-phased where timing is material. A simple static residual can explain the basic relationship between value, costs, profit and land, but it cannot properly capture the economics of a multi-year scheme in which expenditure and receipts occur at different points.
Planning and infrastructure assumptions need the same discipline. Affordable housing, infrastructure contributions and other policy requirements should reflect the adopted and relevant emerging policy position, with credible alternative scenarios where genuine uncertainty remains. In England, government viability guidance emphasises that planning policy requirements should be reflected in land value rather than treated as an afterthought to the price already paid.
Section 106 and CIL are familiar inputs in England and Wales where applicable, but planning-obligation and infrastructure-funding regimes differ across the UK. A UK-wide land appraisal cannot simply import an English planning-cost assumption into a Scottish or Northern Irish site.
Then there are the site-specific risks: remediation, utilities, drainage, ecology, ground conditions, access works, demolition, archaeological requirements or other abnormal expenditure that may be only partially understood when the initial bid is made. The useful exercise is not to move each assumption up or down mechanically. It is to identify which combination of credible downside events breaks this particular deal.
A site that clears the required return comfortably in the base case but falls apart when two plausible risks occur together is not necessarily a bad site. It is a site whose acquisition price needs to recognise how little room for error the appraisal contains.
Bid discipline: separating the number you can pay from the number you want to pay
A disciplined bidder needs more than one land number. There is the base-case appraisal output — what the scheme appears able to support if the central assumptions occur; the preferred acquisition price — where the business is prepared to buy while retaining the margin of safety it actually wants; and the walk-away price — the point beyond which the expected return no longer compensates for the risks, capital commitment and opportunity cost being taken.
Those figures do not have to be the same, and just as importantly the bidder should understand what drives the gap between them.
In most development appraisals, not every input carries equal risk. A scheme with difficult remediation may be unusually exposed to abnormal costs. A high-density urban scheme may be far more sensitive to build cost, programme and sales rate. A large housing site may be highly sensitive to absorption and infrastructure phasing. An income-producing commercial scheme can move sharply with rent, letting period or exit yield. Knowing which variables dominate the downside is considerably more useful than producing a sensitivity table filled with dozens of coloured cells and treating every assumption as equally important.
One further caution matters here: there is no universal developer-return percentage that automatically tells every bidder what land is affordable. For English plan-making viability, government guidance says an assumption of 15–20% of GDV may be suitable when testing plan policies, subject to evidence and the type, scale and risk of development. That is not the same thing as prescribing the acquisition hurdle rate for an individual developer buying a particular site.
Different businesses measure return differently — profit on cost, profit on GDV, return on capital, IRR and other metrics — and required returns change with risk, programme, leverage and corporate strategy. A sophisticated bid appraisal should therefore reflect the bidder’s actual investment criteria, not a margin copied from a planning viability report simply because it looks familiar.
Why the highest bid isn’t always the strongest appraisal
Competitive bidding creates an awkward information problem: the losing bidder sees the winning number, but not the assumptions behind it.
A higher offer can reflect stronger evidence — better sales comparables, a genuine construction advantage, cheaper finance, a different delivery model, greater density that the bidder has good reason to expect, or a strategic value that the site has to that particular business. But it can also reflect assumptions that are simply more aggressive.
GDV may lean heavily on the strongest recent comparable rather than the evidence as a whole. Build costs may not fully reflect the intended specification or programme. Infrastructure and abnormal costs may be underdeveloped at bid stage. A strategic need to replenish the land pipeline can alter the return a business is willing to accept, while planning upside may be given more weight by one bidder than another.
None of that means the highest bidder is necessarily behaving irrationally, and the losing bidder should not assume that the winner has made a mistake. It means price alone does not reveal appraisal quality. Two rational developers can arrive at materially different bids because they have different costs, funding, delivery capability, return requirements and views of risk.
The discipline is not matching somebody else’s bid. It is understanding exactly what would have to be true for their price to make sense for you.
Hope value: real, but not a licence to bid on it
Where a site carries genuine future planning potential beyond its current position — allocation prospects, an emerging local plan, a credible increase in density or another realistic planning outcome — that upside can legitimately influence what a bidder is prepared to pay. What it cannot sensibly do is enter the appraisal as though the more valuable planning outcome were already certain.
For acquisition purposes, the better approach is to separate the current deliverable case from the upside case, then reflect the probability, time, cost and risk of achieving the latter. A £5 million uplift that has a material risk of never being realised is not worth £5 million today, and timing matters as much as probability: even where the planning outcome is ultimately achieved, several years of promotion, professional costs, holding costs and capital exposure can sit between today’s bid and the future value.
Sometimes the better answer is not merely to reduce the price but to structure the transaction differently — through conditionality, deferred consideration, overage or another mechanism that shares some of the planning risk between buyer and seller. The precise structure requires appropriate legal, tax and valuation advice, but the commercial principle is straightforward: do not pay the full value of tomorrow’s successful outcome today while carrying all of the risk that tomorrow never arrives.
A worked appraisal — labelled clearly as illustrative
Take a hypothetical residential site with capacity for 50 homes and an assumed blended GDV of approximately £15 million based on evidence for that particular location. Residential development is being used here because it gives the residual mechanism an easily understood set of numbers. The same principle applies to commercial and mixed-use schemes, although the variables being stressed may differ materially — rent, letting period, tenant incentives, stabilised income and exit yield may matter more than house-sale values.
The appraisal includes construction, professional fees, infrastructure and planning costs, abnormal costs, finance, sales costs and contingency, together with the developer return required by the hypothetical bidder. The amount left after those assumptions produces the base-case residual available for the land.
Now stress it. Assume, purely for illustration, that GDV is 5% below the base case, removing £750,000 from a £15 million scheme before any cost has changed. Then assume construction expenditure is 3% above the appraisal assumption and delivery is pushed back by six months, altering not only the completion date but potentially the timing of expenditure, receipts and finance as well.
None of those illustrative movements is intended as a benchmark for a real development. On some sites a 5% value movement would be excessively severe; on others it would be nowhere near enough. A 3% construction movement could likewise be inappropriate in either direction depending on procurement stage and technical risk.
The point is the mechanism. If the original land residual is only a relatively small proportion of GDV, movements that look modest when expressed as percentages of total scheme value or construction cost can consume a very large proportion of the amount available for land. Once the bid has been paid, the same downside no longer reduces the historic land price; it reduces the developer’s return. That is why the stress test belongs before exchange.
What should actually make a bidder walk away
Not “always do your research” — every serious bidder already knows that.
The sharper question is this: at what price does the site’s expected risk-adjusted return stop justifying the capital, management resource and opportunity cost involved compared with the other places that money could be deployed? That question needs answering before the competitive process starts exerting its own pressure.
If a site only achieves the required return because the appraisal assumes the strongest sales values, the smoothest programme, no material abnormal surprise and the planning upside arriving exactly as hoped, the problem is not that any one of those assumptions is impossible. It is that too many of them may need to be right at the same time.
There will always be sites that another bidder can justify at a higher price. Sometimes they have a genuine advantage; sometimes they are willing to accept a lower return; sometimes their view of the opportunity is simply different. The acquisition discipline is knowing the price at which your appraisal stops compensating your business for the risks it is taking — and being prepared to let somebody else own the site beyond it.
Winning the land is not the objective.
Buying it on terms from which a viable development and an acceptable return can still be delivered is.
This article provides general development-land, appraisal and market information, not valuation, financial, planning, legal, tax or investment advice for individual circumstances. Land values, development costs, finance, planning requirements, developer returns and viability vary materially by site, jurisdiction, scheme and purchaser. A development site should be independently investigated and appropriately appraised before any binding acquisition commitment is made.

