

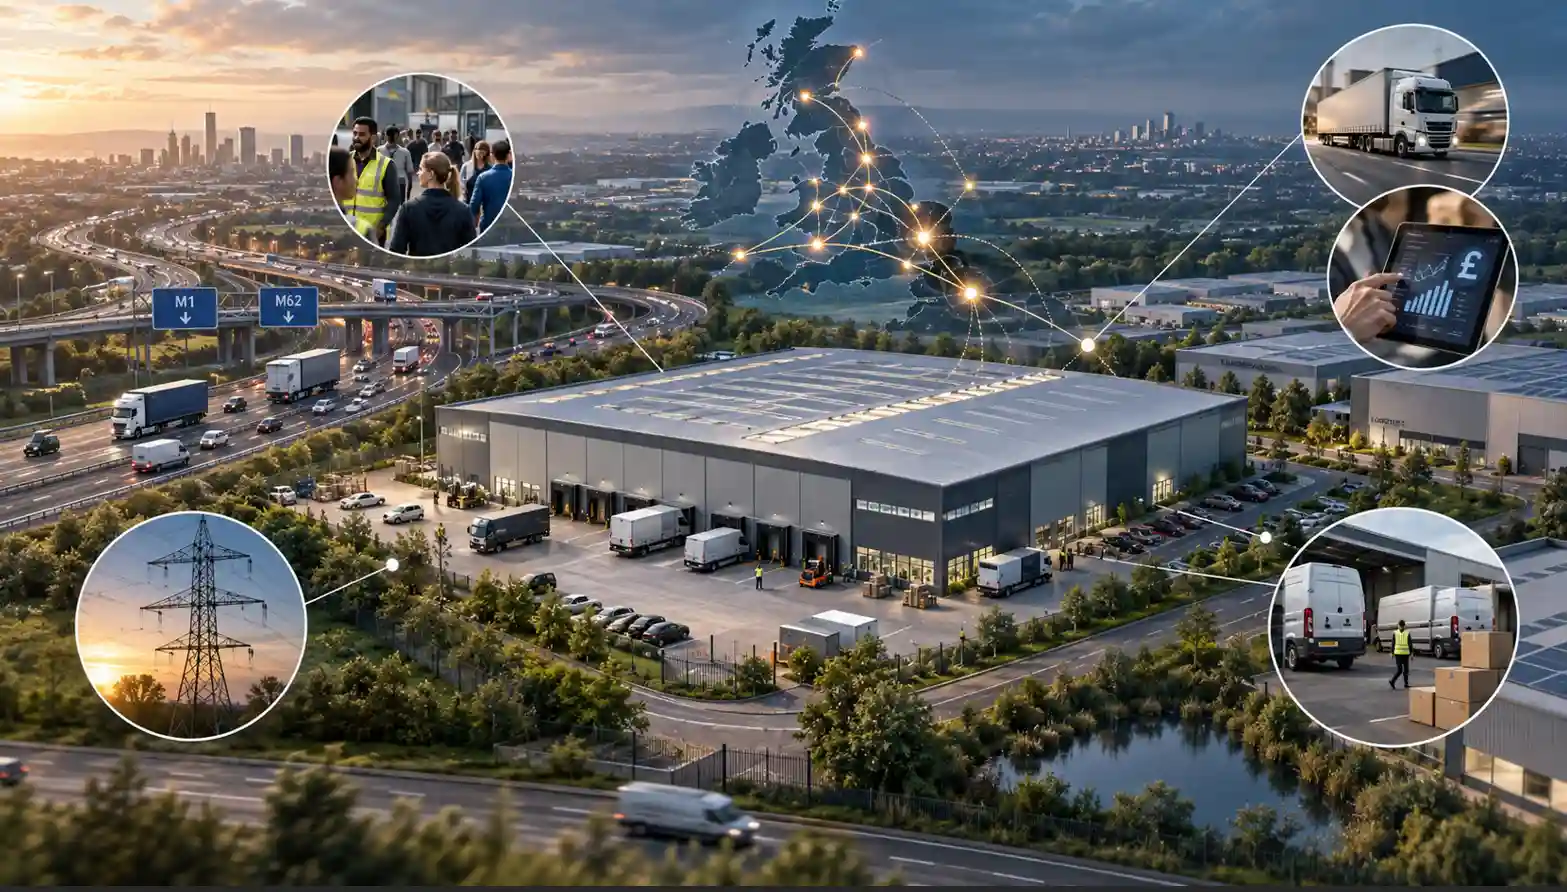
A unit twenty-five miles further from the motorway network, going for £2 less per square foot, looks like an easy saving on the rent line. It may not be once the whole business is accounted for. Extra miles can mean extra fuel, extra driver hours, extra vehicle wear, later delivery windows and — depending on the business — missed carrier cut-off times that push next-day deliveries into two-day ones.
The cheaper unit can end up costing considerably more to run than the expensive one, and the only way to know which is true for a specific business is to do the sum properly rather than stopping at the rent comparison.
This isn’t a list of “best places in Britain for warehouses.” Location performance depends entirely on what a specific business needs from its site. The right question is how to work that out, not which postcode wins a generic ranking.
Map the operating geography first
Different operating models need fundamentally different proximity to customers.
A last-mile delivery operation needs to be genuinely close to the population it serves because delivery time and cost are repeatedly influenced by the distance travelled on every route. A regional distributor needs a sensible position relative to a defined territory, not necessarily close to any one customer. A trade-counter business depends on customers physically visiting, which makes local accessibility and visibility much more important than it would be for a closed distribution facility.
A manufacturer may care as much about suppliers, skills and infrastructure as about proximity to the eventual customer. A national fulfilment centre, by contrast, may be positioned to balance access across a much wider geography rather than favouring any one market.
That helps explain the long-standing importance of the Midlands logistics “Golden Triangle”. Definitions vary, but Knight Frank describes the area broadly around Nottingham, Birmingham and Northampton as offering access to around 90% of the UK population within a four-hour drive, alongside the M1, M6 and M42 corridors.
Knight Frank — Households and their Logistics Needs
That does not make the Midlands automatically right for a national distribution operation. It explains why it became attractive in the first place. The customer and order data still need to lead the decision.
Good strategic-road access can materially affect travel time, driver hours, fuel consumption and delivery reliability for an operation running significant vehicle mileage, but the scale of that effect depends on how much of the business actually relies on those movements. For a distribution-heavy operation making multiple vehicle journeys every day, the difference between being close to a strategic junction and repeatedly travelling across slower local roads can accumulate into a significant annual operating cost. For a manufacturer dispatching comparatively infrequent full loads, exactly the same difference may matter much less.
Distance on the map is not enough either. The useful test is the actual route the fleet will use: junction layout, congestion at working hours, local road restrictions, reliability and the time taken from the site gate to the strategic network. A warehouse advertised as “five miles from the M1” may perform worse operationally than one ten miles away if those five miles regularly take half an hour.
The same principle applies to ports, airports and rail freight. For businesses genuinely dependent on import or export flows, proximity and journey reliability to the relevant gateway can be decisive. Rail freight and intermodal terminals matter where the volumes, commodity, container flows and network connections make rail a practical alternative or complement to road. For many domestic distribution and manufacturing businesses, however, none of these will be primary location criteria. They belong in the decision only where the supply chain actually depends on them.
Manufacturers in particular can also have as much to gain from proximity to important suppliers as from proximity to end customers. Shorter and more reliable inbound journeys can reduce transport cost and lead times, make collaboration on specification or quality problems easier and, in the right operating model, reduce the amount of stock required to protect the business against long or unreliable replenishment.
That does not mean every manufacturer should cluster beside its suppliers. Supplier concentration, dependency risk, inbound frequency, the value and bulk of materials and the stability of the supply base all change the calculation. But where a substantial proportion of the operation’s inputs arrive repeatedly from the same geography, looking only at outbound customer deliveries produces an incomplete location model.
The useful starting point is therefore not the property search itself. It is understanding where the business’s important flows actually run: customers, suppliers, goods, vehicles and carriers, how frequently they move and which of those movements are commercially expensive when the distance or journey time increases.
Labour and power can veto an otherwise good location
Labour deserves serious attention because it can easily be underweighted against the much more visible cost of rent.
The relevant question is not simply the average warehouse wage in a region. It is whether sufficient people can realistically be recruited and retained for the roles, shifts and skills the operation requires.
A large fulfilment centre may compete directly with several neighbouring occupiers for the same pool of warehouse operatives, drivers, engineers and supervisors. A location that looks inexpensive on a property schedule can become considerably less attractive if recruitment requires a sustained wage premium, agency dependence or high staff turnover.
Shift patterns matter as well. A workforce that can reach a site at 9am may not be able to reach it for a 5am start or leave conveniently after a late shift, particularly where the estate has weak public-transport links. Specialist industrial operations can have an even narrower labour requirement, in which case access to the relevant skills base may outweigh a relatively modest difference in rent.
Property availability tells you where a business can occupy space. The labour market helps determine where it can actually operate it.
Power can impose a similarly hard constraint.
A location that scores well on every other measure can still fail if the electrical capacity required by the operation cannot be provided on the necessary terms or timescale. For an ordinary storage operation this may not be decisive. For highly automated warehousing, refrigeration, production machinery, significant EV fleet charging or other power-intensive activity, it can be.
The issue has become more prominent as demand for electricity connections has grown. In Great Britain, Ofgem said in June 2026 that the demand-connections queue was large and growing, and that some well-progressed projects were unable to connect quickly because of the time required for network or generation build as well as congestion created by non-viable projects.
Ofgem — Demand connections reform update
That should not be read as meaning every industrial property faces a connection problem, nor that a whole region can simply be labelled “power constrained”. Capacity and reinforcement requirements can be highly site-specific.
For an occupier with meaningful electrical demand, the relevant questions are what capacity is available at the actual property, what connection or upgrade would be required, who controls that process, what it is likely to cost and — critically — when it can realistically be delivered.
Labour and power therefore have something important in common: both can turn an apparently attractive property location into an operationally poor one even when the rent, transport links and building itself look right.
The centre of this whole article: rent is not the same as cost
This is the calculation many location decisions fail to make, and it is the one that determines whether a “cheaper” unit really is cheaper.
A property further from customers, suppliers or the strategic road network can create additional cost in several places simultaneously: extra mileage, additional vehicle and driver hours, more fuel, lower route productivity, less reliable customer delivery and, for operations dependent on carrier collections, a greater risk of missing commercially important cut-off times.
None of those costs appears on the lease.
That is why comparing locations primarily through quoted rent per square foot can be so misleading.
The correct comparison is not simply annual rent at Site A versus annual rent at Site B. It is the property cost plus the operating consequences of putting the business there.
That calculation will look different for every occupier. A relatively small rental saving can disappear quickly in a transport-intensive business. For an operation where vehicle movements are comparatively unimportant, the rent difference may remain decisive.
The point is not that the more accessible warehouse always wins. It is that access has a value, and that value should be calculated rather than assumed.
Different operations weight location differently
Last-mile logistics makes that trade-off particularly visible.
For an operation serving dense urban demand, locating closer to customers can reduce route mileage, improve vehicle utilisation and support tighter delivery windows. The property itself may cost considerably more, but those additional property costs are being traded against transport and service economics on every delivery round.
It still does not follow that an urban site automatically produces the lowest total cost. Route density, vehicle type, congestion, clean-air or access restrictions, customer geography and the delivery proposition all affect the result. But for a genuinely last-mile-dependent business, paying more for property can rationally produce a lower total cost-to-serve.
Manufacturers typically weight the same location factors differently from pure distribution operations. Labour availability and specialist skills, electrical capacity, proximity to suppliers, inbound and outbound transport, availability of an appropriate building or development site and planning or environmental constraints associated with the proposed activity can all carry considerable weight.
The ranking between them depends on the process. A labour-intensive manufacturer may place access to skills above motorway proximity. An energy-intensive process may be constrained principally by power. A bulky, low-value product can make transport cost unusually important. A supplier-dependent operation may prioritise its inbound network.
Ecommerce and fulfilment operations create another weighting again because the location model increasingly intersects with the parcel-carrier network.
Collection times matter. So does the journey from the warehouse to the relevant carrier hub, the service levels available from that location and whether the business can still meet its customer promise when orders arrive late in the trading day.
Labour remains important because many fulfilment operations are workforce-intensive even where automation is increasing. Customer geography matters because national next-day coverage, metropolitan same-day delivery and specialist bulky-goods delivery each produce different network requirements.
A cheap warehouse that compromises carrier cut-offs or requires a disproportionately expensive labour model can therefore lose much of its apparent property saving.
The best location is not determined by one universally dominant factor. It is determined by which factors matter most to the particular operating model.
Resilience: worth a mention, not a full treatment
It is worth asking whether concentrating an entire operation in one location creates a transport, flooding, utilities or infrastructure dependency that the business has never consciously priced.
The answer does not automatically require a second warehouse. Many businesses quite reasonably operate from one site.
But the consequences of that site’s temporary loss or impaired access should at least be understood. A location served by one vulnerable access route, dependent on one critical piece of infrastructure or exposed to a material flood risk presents a different operational profile from one without those dependencies.
This is not intended as a full business-continuity exercise — that is a substantial subject in its own right. It is simply another reason why location should be evaluated as part of the operating system rather than as a rent quotation.
Regional patterns worth knowing, not treating as a ranking
The current UK market reinforces why regional headline figures need to be used carefully.
Knight Frank recorded UK logistics vacancy of 8.0% at the end of Q2 2026, with total availability having increased during the first half of the year. But Grade A vacancy was only 4.4%, and 57% of take-up during H1 was for new or refurbished Grade A space.
Knight Frank — UK occupier market overview, Q2 2026
That distinction matters to anyone making a location decision.
A region can appear to have plenty of warehouse availability while offering very little stock with the power, height, yard, loading, energy performance or automation capability a particular operation requires. Conversely, a market that looks tight on the headline figures may still contain the right second-hand building for a less specification-sensitive occupier.
CBRE’s 2026 UK logistics outlook makes a similar broader point about occupier preference for higher-quality modern stock, reinforcing the danger of reading total availability as though every available square foot were interchangeable.
CBRE — UK Real Estate Market Outlook 2026: Logistics
That is more useful than compiling a league table of regions.
Regional market data can tell a business where competition for certain types of stock is stronger, where more choice may exist and where particular occupier clusters are developing.
It cannot tell that business where its warehouse should be.
A worked comparison
Take two options for the same regional distribution operation.
Warehouse A sits twenty-five miles from the nearest useful motorway access and further from the bulk of the customer base. Its quoted rent per square foot is meaningfully lower than comparable space closer in.
Warehouse B is much better positioned for the strategic road network and most customer deliveries, but carries the higher rent.
Modelled purely on property cost, A wins comfortably.
Now model the actual operation.
How many additional vehicle miles does A create each day? How much extra driving time does that represent across the fleet? Does it require more vehicles or driver hours to complete the same work? What happens to fuel, maintenance and route productivity? Does the additional journey time interfere with carrier collections or customer delivery windows? Does either site have a materially stronger labour pool? Is the required electrical capacity available at both on an acceptable timetable?
The answers may still show that Warehouse A is the better choice.
But the rental saving now has to survive contact with the rest of the business.
Depending on the volume of movements, distance differential, labour requirement and service model, the higher-rent Warehouse B can emerge as the lower-total-cost site. In another operation with fewer vehicle movements, A may remain comfortably cheaper.
That is why a worked location model should use the occupier’s own movements, people, power requirements and service standards rather than a generic cost-per-mile assumption borrowed from somebody else’s network.
The question this location decision actually turns on
Not “which unit has the lowest rent?” but “which location gives the lowest total operational friction and cost once transport, labour, power and service reliability are properly accounted for?”
The answer will not always be the unit closest to the motorway, the biggest labour market, the cheapest region or the most established logistics location.
A business with the wrong customer geography can be badly located in the middle of the Golden Triangle. A manufacturer can be in an excellent distribution location and still struggle because its skills or electrical requirement cannot be met. A last-mile operator can rationally pay an apparently extraordinary rent because proximity saves more elsewhere in the operation.
Location is valuable only in relation to what the business actually needs the property to do.
A cheaper unit that quietly adds cost or operational friction elsewhere is not necessarily the cheaper choice.
It may simply be the one whose true cost has not yet been calculated.
This article provides general commercial property and logistics information, not financial, transport, planning, energy or other professional advice for individual circumstances. Property, transport, labour, power and infrastructure conditions vary significantly by location and operation. Businesses should investigate individual sites and model material location costs and constraints using their own requirements before making a substantial property commitment.

