

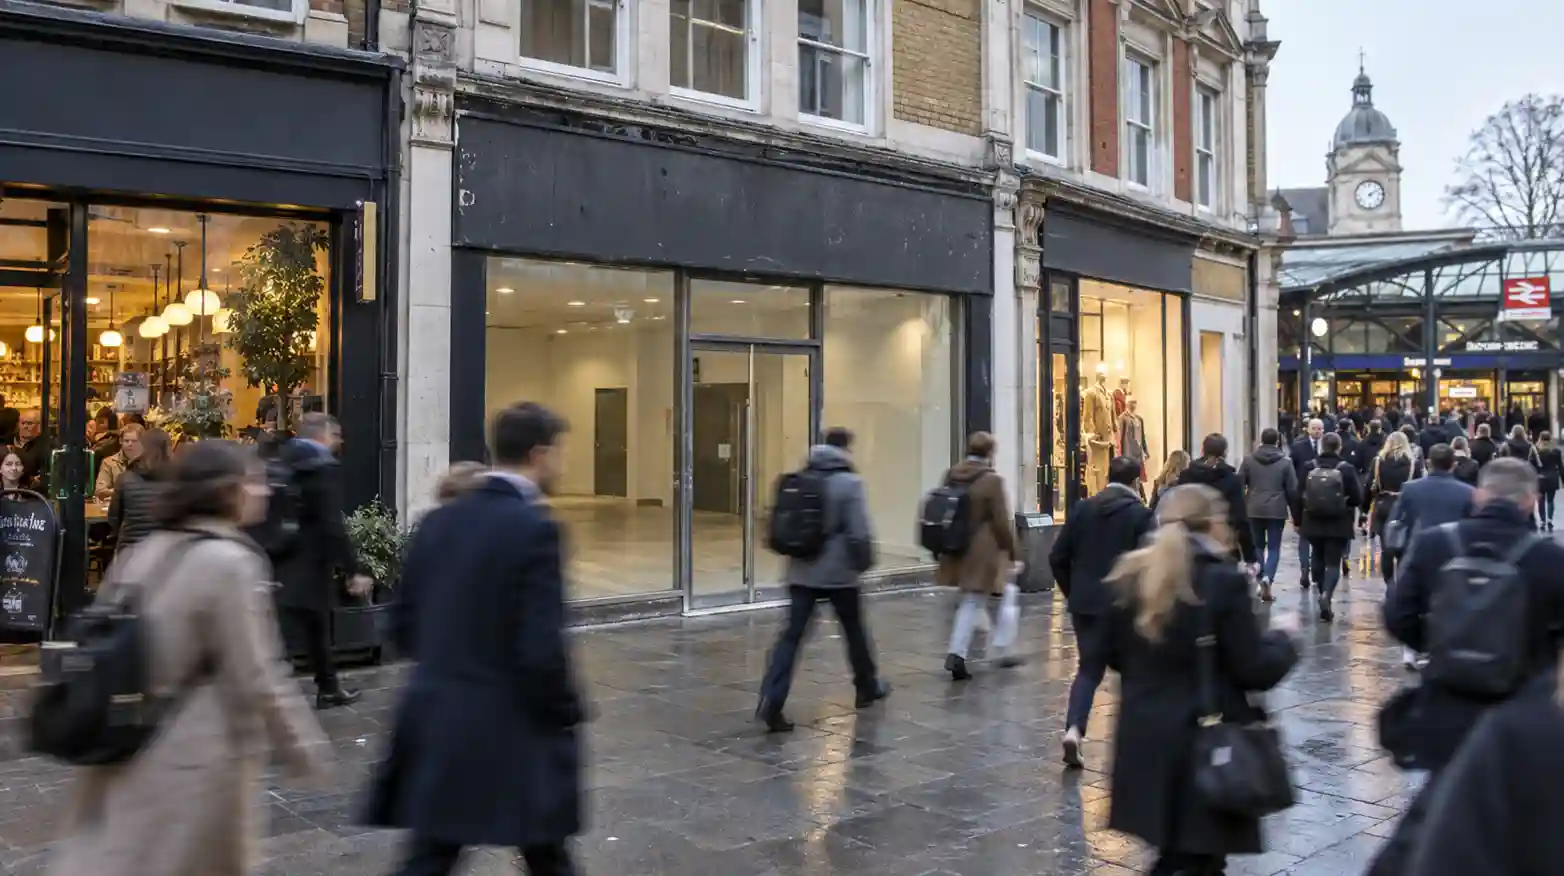
An agent describing a unit as having “excellent footfall” is telling you almost nothing. Ten thousand people a day might walk past a shop front on their way to a station, phones out, headphones in, minds on the train they’re about to miss — yet generate far fewer sales than the headline number suggests. A few hundred people a day who live in the three streets behind a neighbourhood café, walk past it regularly and have nowhere closer to buy a decent coffee can be worth considerably more.
Footfall is a number. Whether it’s the right number, made up of the right people, at the right times, is the question that actually determines whether a location works.
Treat this the way you would treat any investment decision: as something to test with evidence, not something to feel your way into because the unit looks right and the rent seems fair.
Footfall is a headcount, not a forecast
The first thing to establish about any raw footfall figure is who those people are and why they’re there. A pedestrian count taken outside a unit tells you volume; it tells you nothing about intent.
Commuters moving at pace between a station and an office district are a completely different audience from shoppers browsing on a Saturday, parents on the school run or tourists working through a city-centre itinerary. Before treating a footfall number as meaningful, ask: are these people potential customers of this specific business, or are they simply passing through on their way to somewhere else?
There is a more useful way to approach the number: work backwards from what the business actually needs.
If the model requires a certain level of weekly turnover, average transaction value tells you roughly how many transactions are needed to produce it. From there, the location question becomes whether the site can plausibly generate that number of customers from the relevant people passing, living, working or deliberately travelling there.
There is no sensible universal conversion rate to plug into that calculation. A coffee kiosk, destination restaurant, fashion shop, salon and children’s activity venue convert completely different types of demand in completely different ways. The point is not to manufacture a precise forecast from uncertain assumptions. It is to turn “excellent footfall” into a business question: does this location contain enough realistic customer opportunity to produce the transactions the model requires?
That also makes comparisons between locations more useful. A site with lower total footfall can be the stronger option if a much larger proportion of those people resemble the business’s actual customer and are present when the business needs them.
Official data can help establish the wider pattern. The Office for National Statistics publishes weekly and monthly UK retail-footfall data, broken down by broad location type and region. It is useful for understanding whether town-centre, local-centre or retail-park activity is strengthening or weakening, but it is not a substitute for measuring the particular pitch outside the unit you are considering. ONS — UK retail footfall data
That distinction matters. A national or regional footfall trend can tell you something about the market. It cannot tell you whether pedestrians on one side of one particular street are likely to cross the road to buy what you sell.
Daypart changes everything
A location’s usefulness can shift entirely across a single day, and treating footfall as one flat number across opening hours is an easy way to mis-read a site.
A street that’s dead at 8am can be genuinely difficult to walk down at 1pm and quiet again by 4pm, and a business whose trading pattern doesn’t line up with that rhythm will struggle regardless of the overall daily total.
Match the trading pattern to the location’s actual rhythm: a commuter coffee concept needs an early-morning surge, not an all-day average; a lunchtime food business needs a genuine midday spike from nearby workers or students, not general passing trade; an evening restaurant needs the location to remain active — and feel safe and inviting — after 6pm; a weekend leisure business needs Saturday and Sunday demand specifically, which some office-dominated locations simply don’t have.
An appointment-led business such as a salon or clinic is less dependent on passing footfall altogether and more dependent on visibility, convenience and ease of access for people who already intend to visit. That is a different test entirely.
For hospitality and some leisure businesses, there is another constraint: the trading period you observe must actually be available to the business. A street may have excellent late-evening activity, but that is of limited use if the premises cannot lawfully operate the activity or hours the business model requires. Planning, licensing and lease restrictions therefore need checking before observed evening demand is treated as usable demand.
The licensing systems differ across the UK. In England and Wales, for example, selling alcohol and certain entertainment or late-night activities can require a premises licence. Scotland and Northern Ireland operate their own licensing arrangements. GOV.UK — premises licence guidance for England and Wales
Wherever possible, visit and observe the location at the actual times the business would be trading, on both weekdays and weekends, rather than relying on a single daytime viewing or a footfall report averaged across the whole week.
Catchment is not a fixed circle on a map
“Catchment” gets treated too often as a generic radius drawn around a pin, when in practice it is a mix of different populations that varies enormously by business type.
There may be local residents who could visit regularly, office workers present only on weekdays, commuters passing through at specific times, students with term-time patterns, tourists whose numbers are seasonal and destination visitors who will travel specifically for the business regardless of general local footfall.
A business should work out which of those groups it actually depends on and then test whether that particular audience is genuinely present in sufficient numbers — rather than assuming the same fixed-radius model applies equally to a hairdresser, specialist bookshop, restaurant and late-night bar.
Travel time can matter more than straight-line distance. Roads, railway lines, rivers, steep gradients, poor crossings, one-way systems and competing town centres can distort what looks like a perfectly sensible catchment when viewed simply as a circle on a map.
There is useful public data available before paying for specialist catchment analysis. ONS’s High Streets and Retail Areas work includes information on local populations, age profiles, employment and land use around defined retail areas across Great Britain. It will not tell you exactly who will buy from a particular business, but it can test whether assumptions about the surrounding population or employment base are even broadly plausible. ONS — High streets and retail areas in Great Britain
Competition: harmful rivalry or useful clustering?
Seeing a similar business already established nearby is not automatically bad news, and the instinct to avoid any location with a competitor already present can be a mistake.
The more useful distinction is between competition that divides a limited pool of demand and clustering that increases the attraction of the location itself.
A group of restaurants can turn a street into a destination that draws people from further afield specifically because there is choice when they arrive. Several very similar local service businesses on the same short parade, by contrast, may be dividing a relatively fixed pool of customers between them.
The answer cannot be inferred from the number of competitors alone.
Look at how busy those businesses actually appear to be. Check their opening hours, pricing, customer proposition and reviews. Observe whether the area attracts customers specifically for that category or whether each operator appears to be fighting over the same local demand.
A competitor trading strongly can sometimes be better evidence for a location than an empty market with apparently no competition at all.
What sits next door matters as much as what’s opposite
Neighbouring businesses can either feed a new venture’s trade or work against it, and this is worth mapping deliberately rather than noticing by accident.
A cinema surrounded by restaurants creates an obvious before-or-after trip. A gym near healthy food options may benefit from customers already primed for that kind of purchase. An office cluster can support lunchtime retail and food businesses during the week while leaving the same location considerably quieter at weekends. A supermarket or major retail-park anchor can bring customers into a location that smaller complementary businesses can then benefit from.
The question worth asking about any unit is not just “is this a good location?” but “what is already drawing people here, and does our business benefit from that reason, or does it need a different one entirely?”
Also look at change rather than only what is there today. A neighbouring anchor tenant approaching a lease expiry, a large office being redeveloped or a major employer moving out can alter the economics of a pitch surprisingly quickly.
Can people actually see you, and can they actually get in?
Visibility problems are easy to underestimate on a single viewing.
Check signage rights and restrictions, how the frontage reads from normal approach directions, whether trees, bus shelters, parked vehicles, other signage or street furniture obstruct sightlines at the times that matter, whether a supposedly prominent corner unit can actually be seen from the main pedestrian flow and whether the entrance is where a first-time customer would expect to find it.
Upper-floor space needs particularly honest scrutiny. However good the accommodation itself may be, businesses on upper floors depend heavily on street-level presence and wayfinding if customers are expected to discover them from passing trade.
Physical access matters as well. Look at steps, doorways, lifts, gradients and internal routes rather than assuming that because customers can reach the street they can comfortably enter and use the premises. Businesses providing goods or services to the public can also have legal duties around reasonable adjustments for disabled people, so accessibility should be considered before the lease is signed rather than after the fit-out has begun. Equality Act 2010 — Code of Practice on services, public functions and associations
Parking and access aren’t always secondary to footfall
There’s a common assumption that pedestrian footfall automatically outweighs vehicle access, and it doesn’t hold for every type of business.
Parking availability matters disproportionately for destination businesses people will drive to specifically, for bulky or heavy purchases customers will not want to carry, for family trips where public transport may be impractical, for evening trade in areas where public transport becomes thinner later in the day, and for customers for whom convenient accessible parking materially affects whether the premises is usable.
A location can have modest pedestrian footfall and still work extremely well if it has good, obvious and convenient vehicle access for the audience the business actually depends on.
But count usable spaces rather than simply noticing that a car park exists. Check restrictions, tariffs, maximum stays, evening availability and whether the same spaces are already heavily competed for by residents, commuters or neighbouring businesses.
Public transport: check it, don’t assume it
Where public transport genuinely matters to a business’s trade, check service frequency, evening and weekend timetables specifically, and realistic walking time and route quality from the nearest stop or station — not just straight-line distance on a map.
A station 500 metres away across a straightforward pedestrian route can be more useful than one 250 metres away reached through an unpleasant underpass, across a major junction or around a poorly signed route.
Also distinguish between a transport hub that generates passing trade and one that merely moves people through the area. They are not necessarily the same thing.
Deliveries, waste and servicing: the operational test agents rarely mention
A location that scores well on every customer-facing measure can still be operationally unworkable if the back-of-house logistics don’t stack up.
Before committing, check whether deliveries are actually feasible at the times suppliers can realistically make them, whether there is somewhere to load and unload without obstructing the pavement or breaching local restrictions, how refuse and recycling will be stored and collected, whether delivery vehicles can physically reach the unit and whether servicing access is restricted to particular hours that conflict with the trading pattern.
Do not assume a yellow line automatically means loading is impossible, or that the absence of one means deliveries can take place whenever required. Loading controls can be separate from ordinary waiting restrictions and can vary by street and time, so the local highway authority’s signs, restrictions and traffic orders need checking for the individual site.
For restaurants, cafés and other businesses receiving frequent supplies or generating substantial waste, this is not a minor operational detail. A difficult servicing arrangement can create a recurring cost and management problem every trading day.
These points are often better tested by speaking to an existing neighbouring occupier than by relying solely on the marketing particulars.
Why did the last business here fail?
This deserves genuine investigation rather than a quick glance at the shopfront.
Look into who occupied the unit previously, how long they traded, whether there is a pattern of repeated rapid turnover in this particular unit rather than an isolated failure, and what is happening to vacancy in neighbouring units and the wider area.
None of this proves the premises are at fault. Businesses fail because of weak concepts, poor execution, insufficient capital, excessive costs and numerous other reasons that have little to do with location.
But repeated short-lived occupation in the same premises is a signal worth investigating rather than dismissing as coincidence.
Try to establish what has changed as well. A former business may have failed before a new anchor opened nearby, while a once-successful location may now be suffering because offices have emptied, parking has changed, a shopping centre has declined or pedestrian flows have moved to another part of town.
History is useful only when the conditions behind it are understood.
Seasonality: know which kind of business you’re actually running
For businesses in tourist destinations, coastal towns, university areas or locations built around particular events, trading is rarely flat across the year.
A viability assessment based only on peak-season observation can badly overstate what the location supports during quieter months.
Test, or at minimum research, the location during its weakest period rather than only its best one.
That also applies at smaller scales. University holidays, school terms, Christmas trading, summer tourism, major sporting fixtures and office attendance patterns can all create temporary footfall that looks permanent if the site happens to be viewed at the wrong time.
Verify the agent’s claims independently
Commercial agents can be an excellent source of local market knowledge. Nothing here requires treating their information with suspicion.
But phrases such as “excellent footfall”, “prime pitch”, “strong catchment” and “highly visible location” are descriptions, not a substitute for the evidence behind them.
Ask what the claim is based on.
If there is a footfall figure, establish who measured it, when, over what period and exactly where the counter was positioned. If a catchment is quoted, find out how it was defined. If the area is said to be improving, identify what has actually changed.
Then cross-check where possible using your own observations, nearby occupiers, local-authority information, Business Improvement District data where one exists, current vacancy and letting evidence, and national sources such as the ONS footfall and retail-area datasets.
The more significant the lease commitment, the less sensible it is to rely on an adjective.
The discipline this requires
None of the individual checks above is particularly complicated. What makes the difference is doing them systematically and comparing candidate locations on the same basis before becoming emotionally committed to one of them.
But that does not mean every factor should be given a score and added together. A location can perform brilliantly on eight measures and still be unusable because it fails on the ninth one that actually matters to the business.
Identify the handful of location requirements the model cannot realistically operate without and establish the minimum acceptable level for each before viewing competing premises.
For a commuter-led coffee business that might mean sufficient relevant morning footfall and visibility from the dominant pedestrian route. For a destination restaurant it might be evening accessibility, a sufficiently large catchment and the ability to trade the required hours. For a bulky-goods retailer, convenient vehicle access and parking may be essential while passing pedestrian footfall matters very little.
Those are hurdle requirements, not points to compensate for elsewhere. Exceptional footfall does not make an impossible servicing arrangement workable; cheap rent does not create evening demand; excellent parking does not rescue a location that the target customer has no reason to visit.
Once those non-negotiables have been established, the softer advantages — stronger frontage, better neighbouring occupiers, slightly higher footfall, easier public transport — can help distinguish between sites that have already passed the basic viability test.
And keep the location test separate from the financial one. A site can have an excellent customer catchment and still be the wrong premises if rent, business rates, service charges, fit-out costs or staffing requirements mean the sales it can realistically generate will not support the occupation cost.
The two tests do, however, meet at one crucial point. If the business needs a particular level of turnover to carry its occupancy costs and produce an acceptable return, the location must offer a credible route to enough customer transactions to generate it. The assumptions do not need to be artificially precise, but they do need to reconcile.
Location analysis therefore does not answer whether the entire deal works. It answers something more specific and equally important: whether enough of the right customers are likely to use this particular place, at the times and in the way the business model requires.
That is a question worth answering with evidence before signing a multi-year lease.
This article provides general commercial property information, not legal, financial, valuation or professional advice for individual circumstances. Location viability depends on the particular business, premises, lease and local market. Planning, licensing, accessibility and other regulatory requirements vary by activity and across the UK, and should be checked for the specific premises before committing.

