

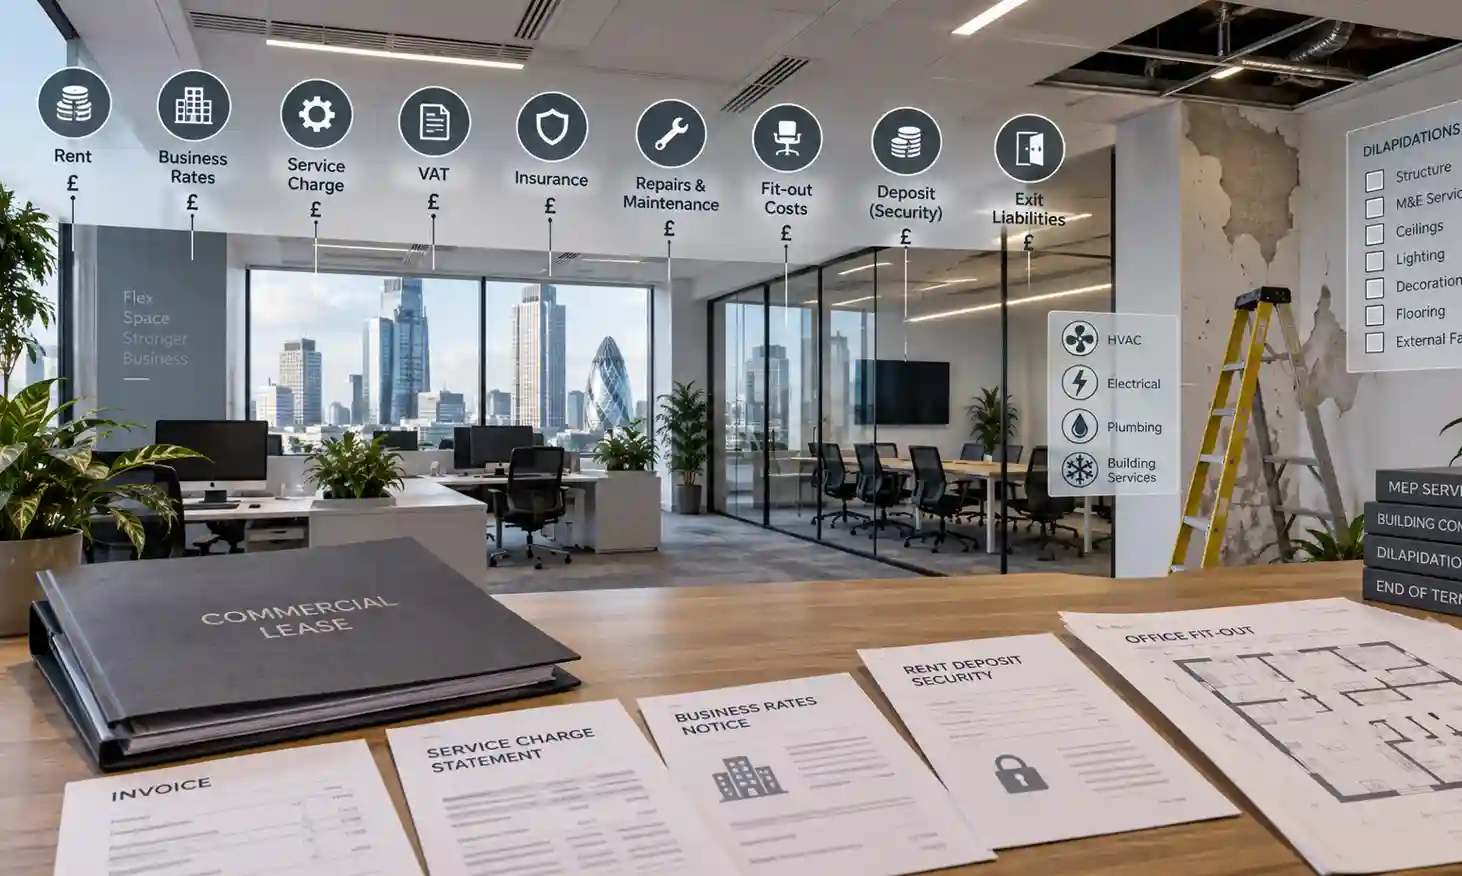
An office advertised at £45 per square foot looks like a single number. For a 3,000 sq ft floor, that reads as £135,000 a year, and a founder or finance director can do that sum in their head before the agent has finished the sentence.
It is very rarely the number that ends up on the bank statement.
Business rates, service charge, insurance, fit-out, professional fees, tax, deposits and repairing obligations all sit underneath the quoted rent. Some hit cashflow before the first desk arrives. Others build over the term or appear at exit, when the business may discover that leaving the office is itself a capital event.
There is another complication: headline rent is not necessarily the best measure of the deal either. Rent-free periods, stepped rents, landlord contributions and other incentives can materially alter the effective economics of one lease against another.
None of this makes the advertised rent misleading. It simply means that headline rent, effective rent and total occupation cost are three different numbers.
The useful question before signing is therefore not just “can we afford the rent?” but “what will this property actually cost us, from taking possession to handing it back — and which parts of that cost can still move?”
The lease discussion below relates principally to business premises in England and Wales. Commercial leasing law, rating and property taxation differ elsewhere in the UK, and the economics of any individual deal ultimately depend on the lease itself.
Headline rent is only the first layer of the deal
Rent quoted per square foot remains the market shorthand for conventional office space, but two apparently similar headline rents can produce very different occupational economics.
Start with the incentives.
A landlord offering a rent-free period or capital contribution towards fit-out may be preserving the headline rent while materially reducing the tenant’s effective cost, particularly during the early years. Conversely, a lower quoted rent accompanied by weak incentives, significant capital expenditure and heavier occupational liabilities may prove more expensive overall.
That distinction matters when businesses compare buildings and when agents compare evidence. The headline figure has value as a market benchmark; it is not, by itself, the number a finance director should put into the whole-term model.
Then come the costs sitting outside it.
Business rates can be one of the largest. Since the 2026 revaluation took effect on 1 April 2026, businesses assessing space in England and Wales should be working from the property’s current assessment rather than an old particulars sheet or historic occupier’s bill. The VOA’s business rates valuation service allows an occupier to check the current rateable value, see how it has been calculated and compare it with similar properties.
Rateable value is not the rates bill. The eventual liability depends on the relevant multiplier, reliefs, transitional arrangements and other adjustments. For an occupier evaluating competing offices, modelling the actual property-specific exposure is considerably more useful than applying a regional or national percentage assumption to the rent.
Service charge is another potentially substantial variable. The important question for an experienced occupier is not simply what this year’s quoted £/sq ft figure is, but what sits behind it.
The current budget, previous expenditure, basis of apportionment, planned major works, reserve or sinking funds, exclusions, caps and treatment of void space can all materially affect the exposure. The RICS professional standard on service charges in commercial property places particular emphasis on transparency, timely budgets and year-end reporting.
An uncapped service charge may not be rent in legal terms, but in the occupation budget it behaves like another variable property cost — and one over which the tenant has limited direct control.
Insurance contributions, utilities and costs within the demise then sit alongside it. Exactly where one category ends and another begins depends on the building and lease.
VAT can alter the cashflow again. Commercial property letting is normally exempt from VAT, but a landlord may have opted to tax the property, in which case relevant property supplies will normally become standard-rated. HMRC’s option-to-tax guidance explains how this operates. Whether that VAT is ultimately a cost to the tenant depends on the occupier’s own VAT recovery position.
A serious occupation-cost model should therefore distinguish between the rent in the brochure, the economic rent after incentives and the full recurring cost of occupying the building.
Before occupation, there is the capital requirement
The annual cost is only one side of the decision. The other is how much cash the property absorbs before it begins generating any value for the business.
A landlord may require a rent deposit or another form of security. Guarantees can create contingent liabilities even where they do not consume cash immediately. Rent may be payable in advance. The business will also have its own legal, surveying and potentially project-management costs.
The RICS Code for leasing business premises is useful here because it treats these matters as part of the commercial deal that should be made clear in the heads of terms rather than discovered during drafting. Deposits, guarantees, rent payment, service charge, insurance, repairs, VAT and other principal obligations should be exposed early enough to negotiate them intelligently.
Fit-out can then dwarf several of those lines.
The relevant number is not a generic pounds-per-square-foot benchmark. It is the cost of turning this particular building in its present condition into space the business can actually occupy: mechanical and electrical work, partitions, data, furniture, meeting rooms, kitchens, access systems, branding, professional fees and whatever landlord approvals the lease requires.
Landlord contributions or rent-free periods may offset some of that burden, which is another reason a headline-rent comparison can be economically misleading.
Lease acquisition can also create a direct tax cost.
A new non-residential lease in England or Northern Ireland may attract Stamp Duty Land Tax, calculated where applicable on any premium and separately on the net present value of the rent. HMRC sets out the treatment of SDLT on non-residential property and leases.
Wales instead applies Land Transaction Tax to non-residential property and leases, while Scotland uses Land and Buildings Transaction Tax for lease transactions.
For a well-capitalised occupier these may simply be transaction lines. For a growing business, however, the distinction between a space requiring significant upfront capital and one converting more of its occupation cost into recurring expenditure can materially change which deal is affordable.
The liability that follows the lease to the exit
Repairing obligations are where a superficially attractive office deal can develop a long tail.
Full repairing and insuring terms remain familiar across conventional commercial leasing, but FRI describes an allocation of cost rather than one identical physical obligation in every building.
An occupier taking a whole building may assume extensive direct responsibility for repair. A tenant occupying one floor of a multi-let office may repair its demise while paying, through the service charge, towards the landlord’s repair of the structure, roof, plant and common parts.
Either way, the business can be carrying the economic burden.
The starting condition matters because a repairing covenant may require more than returning the space exactly as it was found. Depending on the drafting, an occupier can take on responsibility for putting existing disrepair right.
That makes the negotiation of repairing liability more important than the shorthand label attached to the lease.
Where liability is intended to be limited to the initial state of the premises, an appropriately prepared schedule of condition, properly reflected in the lease wording, can be crucial. The RICS leasing code specifically recognises schedules of condition where the agreed repair obligation is to be limited by reference to the property’s condition at the outset.
Then there is reinstatement.
Partitions, meeting rooms, specialist installations, cabling, signage and other improvements that cost money to install may have to be removed when the lease ends. A tenant therefore needs to understand not only what alterations the landlord will permit, but what the lease says happens to them later.
That is where dilapidations enter the economics of the deal.
A schedule of dilapidations identifies alleged breaches of lease obligations such as repair, reinstatement and redecoration. But the cost of every item appearing on a schedule is not automatically the amount the landlord ultimately recovers.
The formal Dilapidations Protocol for commercial property in England and Wales requires the monetary claim to reflect the landlord’s likely loss rather than simply assuming that every item in the schedule will be carried out and charged to the tenant.
There is a further statutory protection in relation to repairing covenants. Section 18 of the Landlord and Tenant Act 1927 limits damages for breach of a repairing covenant by reference to the reduction in value of the landlord’s reversion and can prevent repair damages where the relevant work would be superseded by demolition or structural alteration.
That does not make dilapidations harmless. It means a terminal claim should be analysed as a claim for recoverable loss, not treated automatically as an unquestionable contractor’s bill.
The commercial lesson is straightforward: exit liability should be priced when the lease is negotiated, not first considered when the office is being emptied.
The rent itself can change shape during the term
A business modelling a five- or ten-year occupation also needs to distinguish today’s rent from the rent it may actually pay over the term.
The lease may contain fixed or stepped increases, index-linked reviews, open-market rent reviews or another mechanism. Different structures allocate inflation and market risk differently between landlord and tenant.
That can materially alter comparisons between competing deals.
A stronger incentive package at commencement may compensate for a higher headline rent. An apparently attractive initial rent can become less attractive if the review structure transfers more upside risk to the occupier. Conversely, a landlord may accept particular incentive or review terms because they protect the property’s headline rental evidence or future investment value.
For the tenant, the sensible model is therefore not:
Year-one rent × lease length.
It is the expected cashflow under the actual lease terms, including incentives, reviews and reasonably foreseeable occupational costs.
That same whole-term thinking should be applied to break clauses and alienation.
A business whose headcount could double or halve during the term should attach real value to its ability to break, assign or sublet. A lower rent can be a poor bargain if the company becomes trapped in the wrong amount of space.
Likewise, a personal or company guarantee should not be treated as paperwork merely because it produces no invoice on day one. It is part of the risk capital supporting the lease and should be understood in exactly those terms.
“All-inclusive” solves one problem but creates a different comparison
Serviced and flexible offices approach the economics from the opposite direction.
Much of what appears as separate property expenditure under a conventional lease may be rolled into one recurring occupation charge: furniture, utilities, connectivity, reception, cleaning and, often, business rates and shared services.
For a growing business, that can do something economically important. It converts a significant element of upfront property capital expenditure and long-tail lease liability into a more predictable operating cost.
That flexibility has value.
It also has a price.
A stable occupier expecting to remain in substantial space for years may conclude that paying a continuing flexibility premium makes less sense than accepting the capital commitment and liabilities of a conventional lease. A rapidly changing company may reach precisely the opposite conclusion because avoiding fit-out capital, long commitments and surplus-space risk is worth considerably more to it than achieving the lowest theoretical occupancy cost.
“All-inclusive” still needs testing. Meeting rooms, parking, storage, enhanced connectivity, additional access, printing, catering or other services may fall outside the basic price. Notice provisions, deposits and damage or reinstatement obligations can exist too.
But the more interesting comparison is not simply whether the serviced-office invoice contains fewer line items.
It is which risk the business is paying somebody else to carry.
Two offices can have completely different economic profiles
That is why a conventional office quoted per square foot and a serviced office quoted per desk cannot sensibly be compared from the headline numbers alone.
The conventional lease might offer lower long-term unit cost and greater control of the premises, but demand capital upfront and leave the occupier carrying rates exposure, service-charge risk, repair, reinstatement and a longer contractual commitment.
The serviced suite might appear expensive on its monthly rate but remove much of the fit-out requirement, reduce contractual exposure to a long property commitment and give the business considerably more freedom to change its footprint.
Even two conventional leases at the same headline rent can be economically different once incentives, service charge, rates, repair condition, review structure, capex and exit liabilities are normalised.
The useful comparison is therefore whole-occupation cashflow and risk over the period the business realistically expects to use the space.
For sophisticated occupiers, that is the real decision metric.
What should be resolved before the heads of terms harden into the lease
Before committing to the commercial deal, a business should be able to answer:
- What is the headline rent, what incentives are being offered and what does that make the effective deal over the expected occupation period?
- What is the property’s current rateable value, and what business-rates cashflow should actually be modelled?
- What does the service-charge budget contain, what have previous years actually cost, are major works or reserve-fund contributions expected and is any cap meaningful?
- Is VAT chargeable, and what is the occupier’s recovery position?
- What deposit, guarantee or other security is required and when can it be released?
- What will fit-out cost after landlord contributions, and what part of that investment may later have to be removed?
- What repairing standard is being accepted, what is the existing condition and should liability be limited by a schedule of condition?
- How can rent change during the term?
- What flexibility does the occupier really have through break, assignment or subletting?
- What obligations survive into exit — including reinstatement, repair, dilapidations and outstanding service-charge adjustments?
- What transaction tax is payable on taking the lease?
None of this is a reason to be nervous about renting an office. Nor is it an argument that the lowest total-cost property is automatically the right one.
Location, recruitment, client access, brand, productivity, building quality and the ability to grow all have economic value too.
The mistake is simply evaluating those benefits against a rent figure that represents only one part of what the business is agreeing to pay and one part of the risk it is agreeing to carry.
The headline rent tells you where the negotiation starts.
The whole-occupation model tells you what the deal actually is.
This article provides general commercial property information and is not legal, tax, financial, surveying or other professional advice for individual circumstances. Lease terms, business rates, property taxes, service charges, incentives, repairing obligations and exit liabilities vary materially by property, transaction and jurisdiction. Businesses making a significant lease commitment should take advice from appropriately experienced commercial property, legal, tax and surveying professionals before entering into binding terms.

