

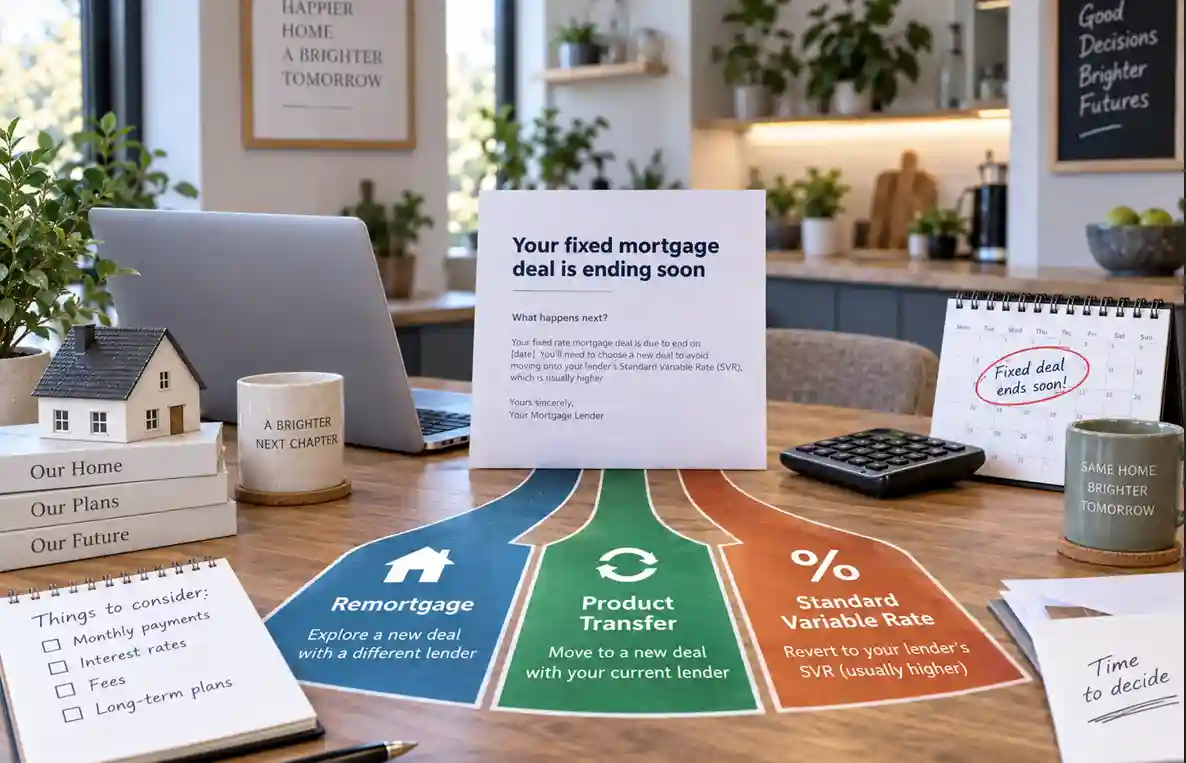
Around six months before a fixed-rate mortgage deal ends is when the real decisions start. It’s easy to think “deal with it later”, but that window is actually the most useful stretch of time a borrower gets in the entire life of their mortgage — long enough to compare the wider market properly, short enough that acting on it doesn’t require guessing where rates will be a year from now.
And a lot of borrowers are reaching that point. UK Finance expects around 1.8 million fixed-rate mortgages to come to an end during 2026, alongside growth in both external remortgaging and product transfers. UK Finance’s 2026 mortgage-market forecast
Left unattended, a fixed deal doesn’t simply expire quietly. It normally rolls onto the lender’s standard variable rate.
That can be expensive. On 7 September 2026, Moneyfacts put the average two-year fixed mortgage rate at 5.63% and the average standard variable rate at 7.13%. Moneyfacts’ September mortgage-rate analysis
On an illustrative £200,000 repayment mortgage with 25 years remaining, 7.13% works out at roughly £1,430 a month, compared with about £1,244 at 5.63% — a difference of around £186 every month. The rate actually available to an individual borrower may be very different from either average, but the example shows why drifting onto SVR accidentally can become expensive quite quickly.
Understanding the three routes available — product transfer, remortgage or deliberately accepting the SVR for a short period — is therefore worth doing properly before one of them happens by accident rather than by choice.
Route one: product transfer
A product transfer means staying with your existing lender and moving onto one of its other mortgage products.
It’s usually the path of least resistance. There may be no need for conveyancing or a new external valuation, and some straightforward switches with the existing lender can be completed without the full affordability assessment normally involved in applying to a new lender. The precise process depends on the lender and whether you’re changing the borrowing, term, repayment method or other important features.
That convenience is real, but it doesn’t automatically mean the deal is competitive.
Your existing lender only offers you its own range. There may be a lower rate, lower fee or more suitable product somewhere else.
The question worth asking isn’t “is this easy?”, because it usually is.
It’s “what am I paying for the convenience, if anything?”
There is another side to that question, though. For somebody whose circumstances have become less straightforward since they arranged their last mortgage, convenience can have genuine financial value rather than merely saving paperwork.
A borrower whose income has fallen, who has become self-employed, whose credit profile has changed or who would struggle with a new lender’s affordability assessment may find an existing-lender product transfer much easier to secure than a new mortgage elsewhere.
MoneyHelper specifically highlights the need to compare products from the existing lender where a borrower may struggle to meet another lender’s affordability assessment. MoneyHelper’s remortgaging guidance
In that situation, a product transfer isn’t simply the lazy option. It may be the most practical route available.
Route two: remortgaging to a new lender
Remortgaging means replacing the existing mortgage with one from another lender.
The obvious advantage is choice. Instead of selecting from one lender’s retention range, you can compare products across much more of the mortgage market.
That can become particularly valuable if your financial position has strengthened since you last borrowed, or if the amount you owe has fallen enough to put you into a better loan-to-value band.
The trade-off is process.
A new lender will normally assess affordability using your current income, expenditure and circumstances. There may be a new valuation and legal work. Product fees, cashback, free valuations and contributions towards legal costs can all affect whether the apparently cheaper mortgage genuinely costs less overall.
A remortgage can therefore produce a materially better outcome, but “I found a lower rate” isn’t the end of the comparison.
The real comparison is between the total cost and suitability of the product transfer you can actually obtain and the remortgage you can actually obtain.
Route three: doing nothing and landing on the Standard Variable Rate
If no replacement deal is arranged, a fixed-rate mortgage will normally move onto the lender’s standard variable rate when its fixed period ends.
An SVR is a lender-set variable rate. It doesn’t necessarily move directly or immediately with Bank Rate, and it can change in accordance with the mortgage terms.
Because SVRs commonly sit above competitive fixed and tracker products, remaining on one for months through inaction can be expensive.
But SVR isn’t automatically irrational in every circumstance.
Imagine you’re selling the property in six weeks.
Or you’re about to receive money that will allow you to repay most or all of the mortgage.
Or you’re between transactions and don’t want to pay a substantial product fee or commit to a mortgage carrying an early repayment charge that you expect to leave almost immediately.
In those situations, deliberately accepting a short spell on SVR can be different from simply forgetting to do anything.
The key word is deliberately.
For somebody with no imminent reason to leave the mortgage, drifting onto a substantially higher SVR through inaction is a very different decision.
The six-month remortgage runway
The practical value of starting early isn’t simply that it gives you longer to shop around. Different jobs become useful at different points in the six-month period.
| Before your fixed deal ends | What is worth doing |
|---|---|
| Around six months | Confirm the exact expiry date, outstanding balance and any early repayment charge. Check your lender’s product-transfer options, get a realistic sense of the property’s current value and start comparing the wider market. |
| Four to five months | Establish whether a new-lender remortgage is realistically available to you. Check whether income, credit or employment changes could affect affordability, and compare fees as well as rates. |
| Two to three months | Get the preferred route moving. If remortgaging externally, allow time for underwriting, valuation, legal work and any extra information the lender requests. |
| Final weeks | Confirm exactly when the new deal will take effect, when any existing ERC ends and what rate would apply if the new mortgage were delayed. |
This isn’t a rigid timetable. Lender windows differ, mortgage offers expire, and not every borrower will need the same amount of time.
The point is to use the six months as a runway rather than a countdown.
Secure a fallback — then keep watching
One of the most useful parts of the current Mortgage Charter is that securing a deal early doesn’t necessarily mean giving up every later improvement.
The FCA’s September 2026 data says 47 Mortgage Charter signatories represent around 90% of the mortgage market. Their commitments include allowing customers approaching the end of a fixed deal to lock in a new deal up to six months ahead and to request a better like-for-like deal with the same lender before the new one starts if one becomes available. FCA Mortgage Charter uptake data
In Q2 2026 alone, 381,364 mortgages were locked into new deals up to six months ahead of maturity.
That changes the familiar dilemma between “fix now” and “wait in case rates improve”.
For an eligible borrower, it may be possible to secure a fallback rate and continue watching the lender’s range. If a better like-for-like deal appears before the new term begins, the borrower can ask to move to it under the Charter commitment.
There are limits. Six months is the maximum Charter window rather than a promise that every lender will offer exactly six months, and rates must be finalised before the new term starts. The government’s current Charter also confirms that these commitments do not apply to buy-to-let mortgages. Government Mortgage Charter 2026
So the useful lesson isn’t “lock in immediately”.
It’s that arranging a sensible fallback and continuing to watch can be a more intelligent strategy than waiting until the final few weeks with nothing secured.
Make sure the dates actually join up
This is one of the least interesting parts of remortgaging until it goes wrong.
Your old fixed rate has an end date. Any early repayment charge has its own end point. Your new lender’s mortgage offer has an expiry date. The legal work and completion process have their own timetable.
Those dates need to meet.
If an external remortgage takes longer than expected and the old fix ends first, you may spend a period on the existing lender’s SVR before the new mortgage completes.
Sometimes that gap is only days and makes little practical difference. Sometimes delays drag on longer.
Equally, completing the new mortgage too early could mean triggering an early repayment charge on the existing deal.
That’s why “my new mortgage has been approved” isn’t quite the same thing as “the switch is sorted”.
Before the old deal ends, establish the expected completion date, when any ERC ceases to apply and what happens if completion slips.
The Mortgage Charter offers more than an early rate lock
The Charter also contains temporary support for borrowers who are up to date with their payments but need some breathing room.
Eligible customers can, on a one-off basis, switch temporarily to interest-only payments for six months or extend the mortgage term to reduce monthly payments, with the option to revert to the original term within six months, without a fresh affordability assessment in the circumstances covered by the Charter.
The latest FCA figures show around 22,400 mortgages reduced their monthly payments through one of those routes in Q2 2026. Between July 2023 and June 2026, around 354,000 mortgages had used temporary interest-only payments or a term extension.
Those options shouldn’t be mistaken for free savings.
Temporarily reducing capital repayments or extending the mortgage can increase the amount paid over the life of the loan, and monthly payments afterwards may be higher than they otherwise would have been. A permanent switch to interest-only, or some extensions beyond expected retirement, can also require further affordability assessment.
Anyone already worried about making their mortgage payments should contact the lender early rather than waiting for the fixed term to expire. Mortgage Charter measures are only part of the support lenders may be able to provide.
Staying put versus shopping around: the actual trade-off
This is worth stating plainly: convenience and the best available deal aren’t necessarily the same thing.
A product transfer with the existing lender might involve relatively little friction. A remortgage to a different lender can involve affordability checks, underwriting, valuation and legal work.
Sometimes that extra work buys a materially better mortgage. Sometimes the existing lender’s offer is competitive enough that switching saves little or nothing once fees are included.
The right comparison therefore isn’t “product transfer or remortgage?” in the abstract.
It is the actual product transfer you can get versus the actual remortgage you can get, at the same point in time, including the costs of each.
For borrowers with larger mortgage balances, relatively small differences in rate can add up to meaningful sums over two or five years.
For somebody with a much smaller balance remaining, the opposite problem can appear.
When the mortgage is small, the lowest rate can matter less
Suppose somebody has only £40,000 left on their mortgage.
Moving lender to save a few tenths of a percentage point sounds sensible in principle, but the cash saving on £40,000 may be relatively small. If the alternative mortgage carries a £999 or £1,499 product fee — or other switching costs — those costs can absorb much or all of the saving.
MoneyHelper specifically warns that where only a small mortgage balance remains, the savings from switching may be too low to make remortgaging worthwhile.
That doesn’t mean somebody with a small balance should simply accept the SVR.
It means the size of the balance changes what matters.
At £400,000, a modest rate difference can be worth a great deal. At £40,000, avoiding a large fee may matter more than shaving a small amount off the interest rate.
Compare fees, not just headline rates
The same principle applies more broadly.
A mortgage with a slightly lower rate but a £1,499 product fee isn’t automatically cheaper than one with a slightly higher rate and no fee.
A new-lender remortgage might include free valuation and legal work. Another might offer cashback. A product transfer may involve little administrative cost. Different borrowers can therefore get different answers from the same headline rates depending on how much they’re borrowing and how long they expect to keep the product.
The relevant number is the total cost over the period you’re actually comparing — not just the percentage printed most prominently on the mortgage advert.
This is where the decision overlaps with choosing between a two-year fix, five-year fix or tracker, but it shouldn’t be confused with it. First establish which routes are genuinely available to you; then compare the structures and overall costs of the products within those routes.
Loan-to-value may have moved in your favour
Many borrowers reach the end of a fixed deal in a better loan-to-value position than when they started, sometimes without realising it.
Part of the mortgage has been repaid. The property may also be worth more.
Suppose you owe £192,000.
If the property is worth £240,000, your LTV is 80%.
If a current valuation puts the same property at £256,000, the £192,000 mortgage represents 75% LTV.
You haven’t paid an extra lump sum towards the mortgage between those two calculations. The difference comes entirely from the valuation.
That can matter because mortgage pricing is often divided into LTV bands. Dropping from 80% to 75%, or from 75% to 60%, can open up different products and potentially better rates.
The important word is realistic. An optimistic online estimate doesn’t force either your existing lender or a new lender to accept the same valuation.
What if your circumstances have changed?
A borrower whose income has fallen, who has become self-employed, whose credit history has changed or whose household finances now look different may find moving lender more complicated than expected.
A new lender is assessing today’s borrower, not the person who successfully obtained the mortgage two or five years ago.
That’s one reason this comparison is worth starting early.
If moving lender looks difficult, discovering that five months before the current deal ends gives you time to understand the existing lender’s options. Discovering it five days before expiry gives you far less room to manoeuvre.
This is also where product transfer can change from being the convenient option to being the strategically useful one.
The same applies to borrowers with more complicated mortgages — including some interest-only arrangements or specialist lending situations — where the repayment strategy or lending criteria may need more attention than a straightforward rate comparison.
Before the letter becomes urgent
The practical takeaway isn’t that remortgaging is always better than a product transfer, or that every borrower must avoid SVR at all costs.
It’s that the end of a fixed deal creates a decision window, and wasting most of that window removes options.
Around six months out, establish what you owe, what the property is realistically worth, when the existing deal and any ERC end, what your lender will offer and whether moving elsewhere is genuinely possible.
Secure a sensible fallback where the lender’s rules allow it.
Then compare.
If the existing lender is competitive, staying put can be perfectly rational. If the wider market offers a meaningfully better outcome after costs, remortgaging may justify the extra process. And if the mortgage is about to be repaid or the property sold, a short deliberate period on SVR can sometimes make more sense than paying to enter another deal you’ll barely use.
What matters is that the route is chosen rather than inherited through inaction.
A fixed mortgage ending isn’t really one decision on one day.
It’s a six-month opportunity to make sure the mortgage you wake up with afterwards is one you intended to have.
This article provides general information about mortgage options and is not personalised mortgage, financial or investment advice. Mortgage rates, fees, early repayment charges, valuations, product availability and lender criteria can change and depend on individual circumstances. Worked examples are illustrative only. If you are approaching the end of a mortgage deal, check the terms of your existing mortgage and, where appropriate, seek advice from an FCA-authorised mortgage adviser before making a decision.

