

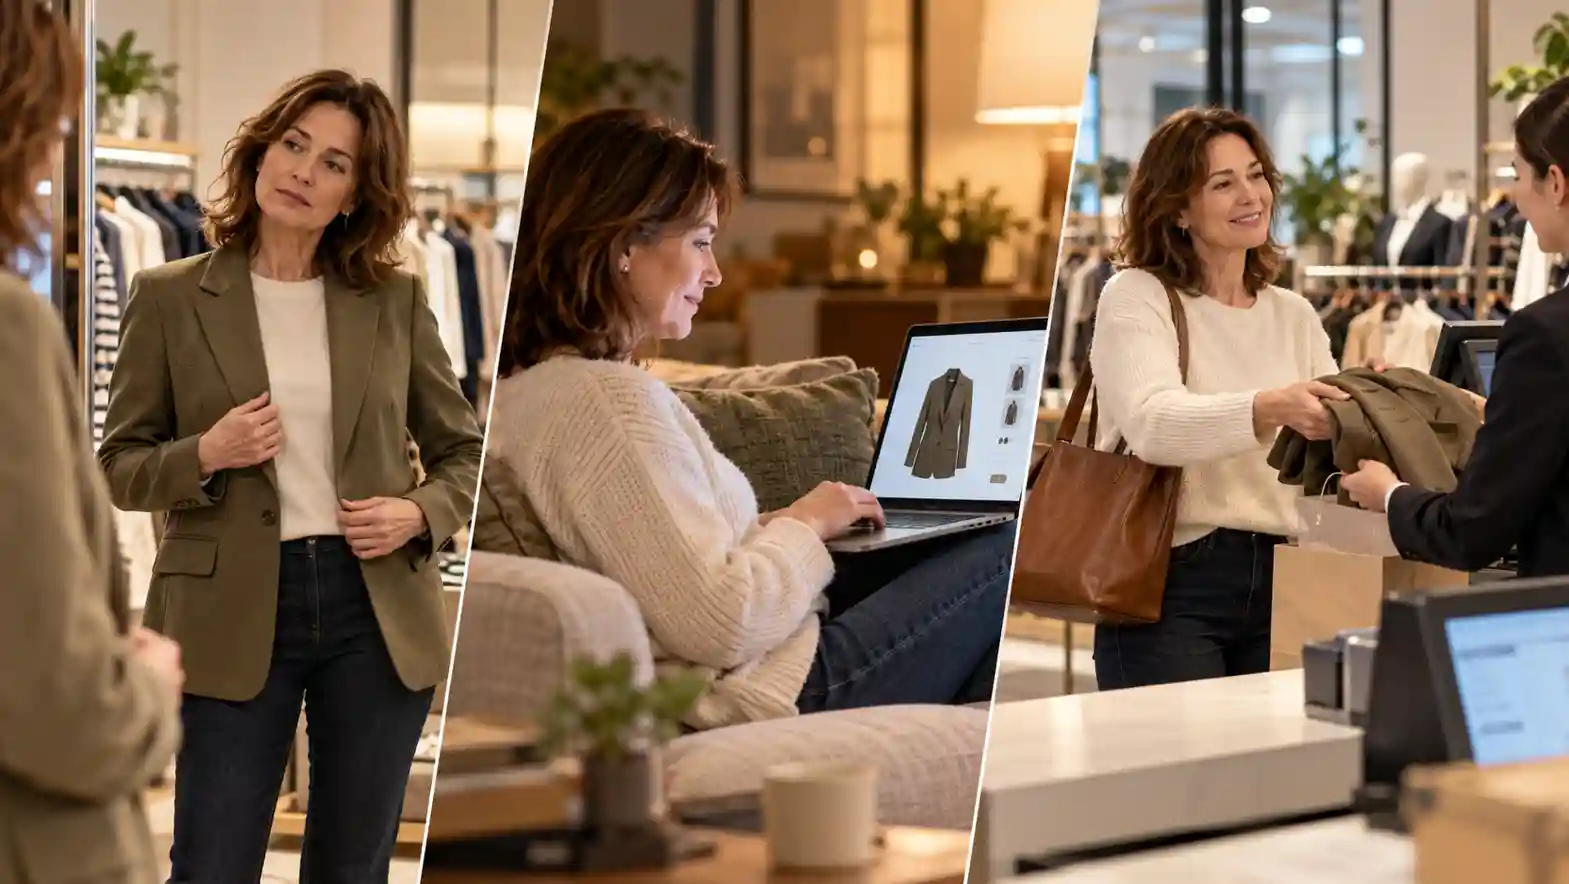
A customer walks into a store, tries on a jacket, decides against buying it there and then, and orders the same jacket online that evening from her sofa. Three days later she returns it — to the store. Somewhere in that sequence, a sale happened. Whether that sale counts towards the turnover rent the store’s landlord is owed depends on lease wording that may have been agreed before anyone contemplated a transaction behaving this way. The dispute reported in April 2026 between John Lewis and the current and former owners of Brent Cross shopping centre brings the problem into sharp focus. Hammerson and the former owner, Aberdeen, argue that click-and-collect orders fall within a lease dating from 1979; John Lewis argues that the relevant sales complete when goods are dispatched from its distribution network rather than collected at the store. Those are opposing positions concerning this particular agreement, not a ruling that determines how every online sale must be treated.
The case matters well beyond Brent Cross because a store can influence a sale, accept a return and serve as a collection or fulfilment point without recording the original payment at its tills. Turnover rent was designed to connect what a landlord receives with the business conducted from particular premises. Omnichannel retailing makes the meaning of “conducted from” increasingly difficult to agree, and an argument about the definition can affect not only rent due today but historic liabilities and the value of the income stream an investor believes it owns. The harder question is whether a physical store should share in sales it helped generate but never actually processed.
A lease clause built for a simpler transaction
Turnover rent is a straightforward idea in principle: the rent moves, at least partly, with the occupier’s sales. In practice there is no universal formula. Some are calculated entirely as a percentage of turnover; others combine a minimum rent with a turnover-based payment, which may be additional rent above a threshold or the greater of a minimum amount and a calculated percentage. The distinction matters because a tenant promised protection against weak trading may still carry a substantial fixed commitment before any variable element is considered. The Valuation Office Agency’s guidance on turnover leases describes the different structures and makes clear how important the contractual definition of turnover is to the calculation.
The formula was easier to administer when a transaction had an obvious home: a customer entered the shop, selected goods, paid at the till and left. Now a purchase may be researched in one branch, placed through an app, fulfilled from a warehouse, collected at another branch and refunded somewhere else entirely. In August 2026, online sales accounted for 28.8% of Great Britain’s retail sales by value on the Office for National Statistics’ seasonally adjusted measure. That figure measures the scale of online retailing, not how much turnover rent any particular store should generate, and it cannot be applied directly to hospitality or other sectors outside the survey’s scope. What it demonstrates is the size of a sales channel that older lease definitions were never designed to describe explicitly.
The attribution questions that do not have an obvious answer
A genuinely comprehensive turnover clause now has to confront a list of scenarios that would have seemed unusual to whoever drafted a traditional store lease. Does a sale researched or tried in-store but completed online later belong to that store, given that no payment passed through it? Does a click-and-collect order count where the goods arrive from a central warehouse, or only where they are picked and dispatched from stock held at the premises? What happens when a customer places an order through an in-store tablet for home delivery, or orders through an app but pays on collection? The practical problem is not merely deciding which transactions the landlord would like to include. It is agreeing categories that the retailer can identify consistently across point-of-sale, ecommerce, warehouse and returns systems.
Returns, concessions and gift cards make the problem less tidy still. If an online purchase is included in a store’s turnover and subsequently refunded through another branch, the agreement needs a method of reversing the original amount without deducting it twice. Gift cards should not generate rent both when purchased and when redeemed unless that unusual outcome is genuinely what the parties have agreed; concession sales may be generated by a business legally distinct from the tenant named on the lease. Restaurant orders placed through delivery platforms raise the additional question of whether turnover means the full amount paid by the customer or the revenue recognised by the operator, including how discounts, delivery fees and platform commissions are treated. VAT, cancelled orders and stock transfers introduce further complications. The definitions must work as a coherent accounting arrangement rather than a collection of individually plausible exceptions.
That is the deeper significance of the Brent Cross dispute. According to DWF’s legal examination of the proceedings, the historic lease includes provisions dealing with mail, telephone and similar orders received or fulfilled through the premises. The landlords contend that modern collection arrangements fall within the contractual language, while John Lewis disputes that interpretation on the basis of where the transaction is completed. The case illustrates why a historic clause does not necessarily become irrelevant simply because it predates the technology now being used: the legal question is what the agreement means when properly interpreted as a whole. A retailer’s internal classification of an online sale, or the point at which its accounts recognise revenue, does not automatically determine the separate contractual obligation to pay turnover rent.
What this demands from a landlord
A landlord relying on turnover rent as a meaningful part of its income can no longer treat the arrangement as a percentage bolted onto a conventional lease. It requires a more operationally involved relationship with the tenant than a fixed-rent structure normally does. The definition must identify which omnichannel transactions are included, which are excluded and how a sale is allocated when several branches or sales channels have been involved. Reporting provisions must then translate those rules into usable information: the frequency of turnover certificates, treatment of refunds and adjustments, supporting records, retention periods and a workable process for challenging discrepancies. Audit rights have limited value if exercising them produces data that cannot be reconciled to the agreed categories.
That does not justify unrestricted access to the retailer’s customer information or commercially sensitive channel performance. Independent verification, agreed confidentiality protections and clearly defined access rights can allow the landlord to test the rental calculation without demanding more information than is necessary. The cost of administering the arrangement belongs in the investment appraisal too, because a theoretical entitlement is only commercially useful if it can be measured and collected at proportionate expense. For an investor buying a shopping centre, uncertainty about those numbers is also uncertainty about the income being acquired, not simply an issue for the property manager to resolve after completion. Historic amounts potentially recoverable through a disputed interpretation need to be considered separately from the recurring income likely to be received under the lease in future.
The Brent Cross proceedings also demonstrate why landlords need to consider more than the current year’s turnover certificate. The claimants are reported to be seeking backdated rent, with the disagreement extending to collection charges and the information used to calculate what may be owed. Similar issues can arise during the acquisition of an income-producing retail asset if the purchaser discovers that historic rental calculations rely on an interpretation the tenant does not accept. Reviewing the relevant lease definitions, reporting records and any existing disagreements is therefore part of understanding the quality of the income being purchased, not merely an administrative task to undertake after completion.
What this demands from a tenant
An occupier accepting turnover-linked rent may gain a lower fixed commitment and some protection when trading disappoints, although the extent of that protection depends on the minimum rent and the agreed formula. The price is a continuing disclosure obligation and, potentially, less control over commercially sensitive sales information. A retailer needs to know whether its point-of-sale, ecommerce, fulfilment and returns systems can produce what the lease requires before agreeing detailed quarterly or annual reconciliations. If they cannot, an arrangement that looks financially attractive in the heads of terms may require substantial systems work or leave the tenant exposed to repeated challenges over figures it cannot readily explain.
There is a further economic complication: turnover is not profit. A retailer can generate additional sales while earning less profit on each transaction because of delivery charges, fulfilment costs, returns, discounts or a change in product mix. An omnichannel sale attributed to a physical store may carry substantial costs elsewhere in the retailer’s distribution operation, even when the lease treats the gross transaction value as store turnover. A rent formula that captures the sale without recognising those costs can therefore increase the landlord’s income while doing little to improve the retailer’s profitability. That does not make the arrangement unfair by definition — percentages and thresholds are negotiated with the occupier’s business model in mind — but it makes the agreed share of turnover considerably more important than the headline sales figure alone.
The agreement can also interfere with how a retailer ought to operate. A business may want to fulfil an order from whichever branch or warehouse has available stock, offer customers convenient collection points and accept returns wherever they are easiest. If rental liability changes materially according to which location processes the transaction, the agreement can create an incentive to route sales for accounting reasons rather than operational efficiency. With stores under different landlords, inconsistent definitions also create a risk that more than one location claims the same transaction. Retailers should be particularly cautious about provisions that cannot distinguish an identifiable sale allocated to a store from a return, a transfer of stock or revenue already counted elsewhere.
Does the physical store deserve a share of value it merely influenced
The genuinely difficult professional question underneath all of this is not really about drafting technique — it is about economic attribution. If a customer tries a product in a store, takes advice from staff and buys online later, the premises may have contributed to a sale its tills never recorded. A landlord has a reasonable argument that the store performed genuine commercial work and that its location, customer service and the wider shopping destination helped generate demand. The tenant has an equally reasonable argument that the retailer’s advertising, digital platform, stockholding and fulfilment network also contributed, and that the store’s precise share cannot reliably be measured. There is no universally correct method of allocating that contribution to every individual transaction.
The distinction matters because capturing a store’s wider influence is not the same as defining transactions actually fulfilled or collected there. The RICS discussion of Investment Property Forum research on turnover leases recognises the wider effect a physical shop can have on sales beyond the premises, sometimes called the halo effect, and explains why turnover-linked income also changes how shopping-centre investments may need to be valued. A lease can use agreed indicators of the premises’ involvement — collection, in-store ordering, fulfilment or another measurable activity — without claiming that the indicator is a scientific measure of which location generated the sale. The more clearly both parties understand that distinction, the less likely they are to mistake a negotiated allocation of revenue for an objective rule about who created it.
Structuring around the ambiguity, rather than resolving it
Where a definitive attribution answer cannot be reached through drafting alone, landlords and tenants can reduce the amount riding on borderline transactions. A higher guaranteed rent with a more narrowly defined turnover top-up may trade some of the landlord’s potential upside for income that is easier to forecast and verify. A percentage confined to identifiable categories, with agreed treatment of collections, returns and delivery charges, may be more robust than an ambitious definition claiming every sale influenced by the store. Caps, minimum payments or an agreed range can limit the financial exposure, although they do not cure an ambiguous definition and may shift more trading risk back to the occupier. These arrangements need judging against the particular asset and business rather than presented as a universal solution.
The amounts involved can become significant. If, purely by illustration, £2 million of annual sales is disputed and the applicable marginal turnover-rent rate on those sales is 3%, the difference is £60,000 for one year, assuming the relevant thresholds have already been met. Over five identical years, that would amount to £300,000 before interest or other costs. These figures are hypothetical and are not an estimate of the Brent Cross claim or its contractual rates. For a landlord, the disputed amount represents potential income; for a tenant, it can become a retrospective financial exposure that only emerges after several years of reporting on a different interpretation. Both parties therefore have an interest in agreeing a calculation that produces the same answer from the same underlying transactions, year after year.
The investment consequence extends beyond any single rental dispute. A fixed minimum rent may be more predictable than a variable payment dependent on contested sales definitions, the accuracy of reported turnover and future occupier performance. RICS has noted that valuers may need to use more explicit cashflow modelling when turnover-linked income becomes a material part of a shopping centre’s rent roll, rather than assuming that every element of contractual income has the same certainty. Historic rent potentially recoverable through a disputed interpretation is not necessarily the same thing as sustainable rental income on which to value an investment. A landlord can negotiate a larger theoretical share of turnover yet be left with income that a buyer or funder is less confident of receiving. Reducing definitional disputes may therefore protect the wider investment case, even where it appears to surrender some possible rental upside.
A closer relationship, not automatically an aligned one
A landlord exposed to occupier turnover naturally becomes more invested in the things that drive trading — tenant mix, marketing, events, dwell time, opening hours and the experience of the shopping destination. A successful centre can generate better sales for retailers and higher turnover-linked income for the owner, giving both sides a genuine reason to collaborate. But a landlord seeking the broadest defensible definition of turnover and a retailer seeking to operate one integrated business do not have identical commercial interests. The landlord wants income it can verify and collect; the tenant wants flexibility to serve its customers efficiently without disclosing more information or paying more rent than the lease requires. That tension remains even when both parties benefit from the destination trading well.
Turnover rent can still be an effective structure, particularly where the landlord contributes meaningfully to the environment in which the occupier trades and both sides accept a degree of shared risk. It becomes much harder to defend when neither party can say with confidence which sales count, how the relevant figures are produced or whether the same revenue has been attributed more than once. The Brent Cross dispute illustrates what happens when retailing evolves faster than the language used to divide the financial value it creates. For landlords, retailers and their advisers, the objective is not to write a clause capable of predicting every future development in commerce. It is to agree an allocation that can be understood, verified and lived with when those developments arrive.
This article provides general information and commercial property analysis only and does not constitute legal, tax, accounting, valuation, financial or investment advice. Turnover-rent obligations depend on the terms of each lease, the relevant facts and applicable law. The outcome of any reported legal proceedings should not be assumed unless confirmed by an authoritative source. Obtain appropriate specialist advice before agreeing, varying or disputing turnover-rent provisions.

