

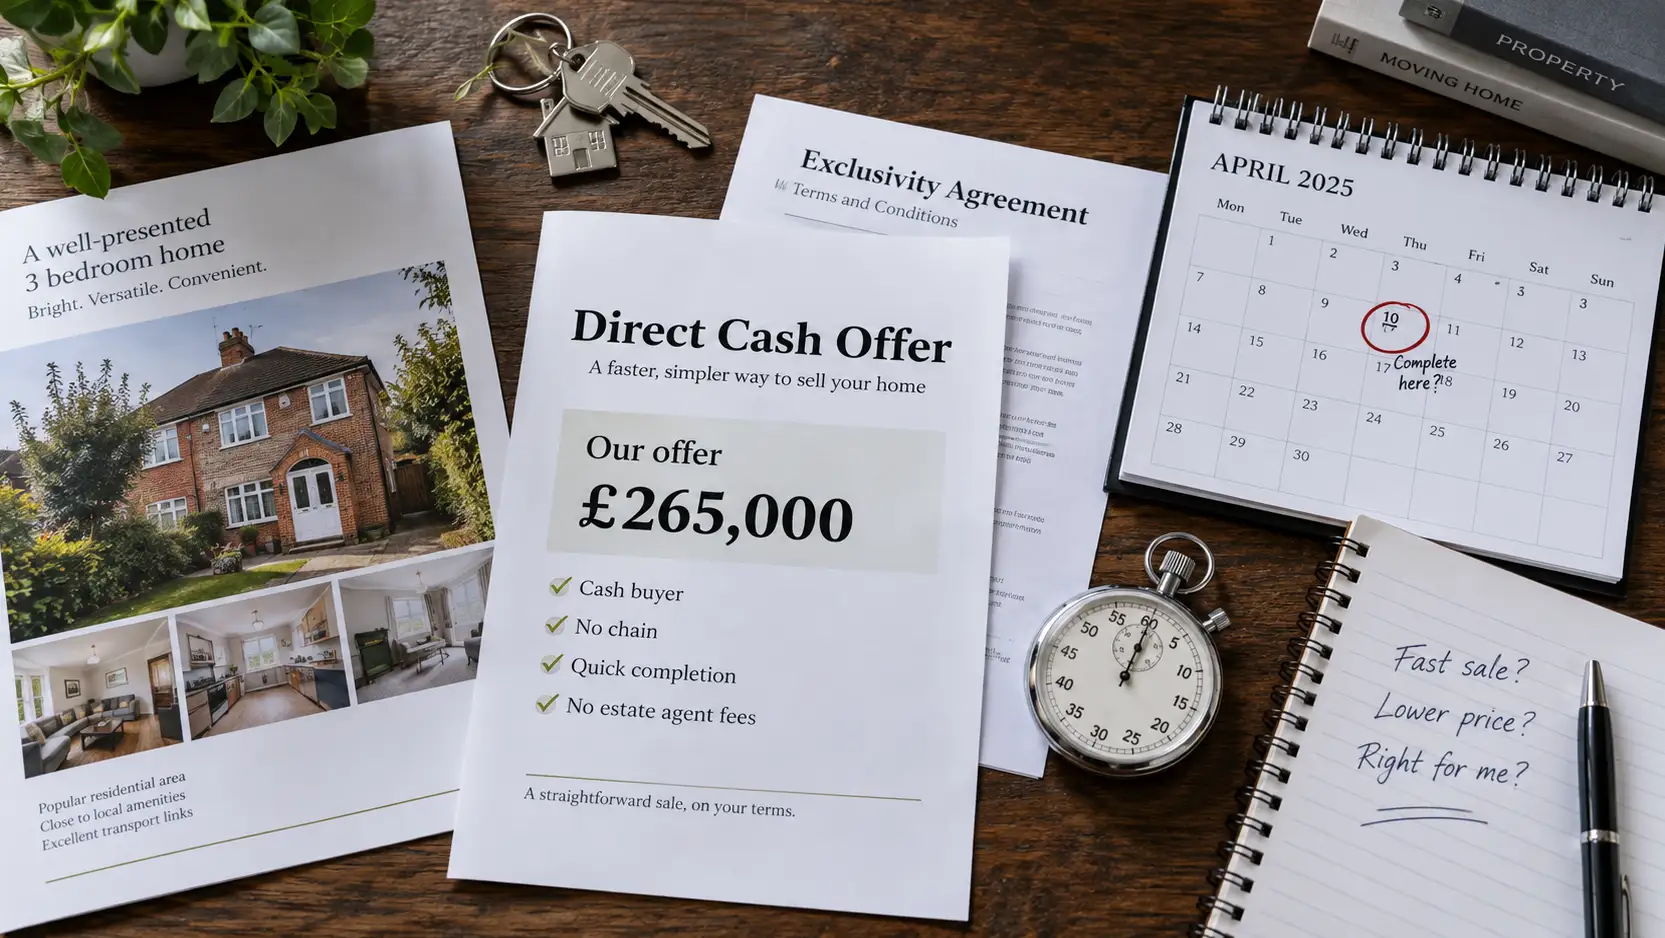
The adverts promise a cash offer within 24 hours and completion in as little as a week. For a homeowner facing a genuine deadline — a chain that’s collapsed, a relationship that’s ended, a repossession clock running down, or simply a property that’s proved stubbornly hard to sell the ordinary way — that promise can look like the answer to everything.
Sometimes it can be the right decision for the circumstances. The trade-off is real, though, and it’s worth understanding precisely what’s being given up before signing anything.
The important question isn’t whether quick house sale companies are inherently good or bad. It is whether the price you are sacrificing buys you enough additional speed and certainty to make that sacrifice worthwhile — and whether the company you’re dealing with can actually deliver the certainty it is selling.
What you’re actually trading
The basic exchange is straightforward: a seller accepts less than they might reasonably achieve through an ordinary open-market sale in return for a potentially much faster transaction with fewer moving parts.
Government guidance explicitly recognises that trade-off. Its guide to selling a home says companies offering instant cash purchases may provide a quick sale but can pay well below market price.
The difficult part is deciding what “below market price” means for your particular property. Do not compare a quick-sale offer with an optimistic asking price. Compare it with a realistic estimate of what the property would probably complete for on the open market.
It is sensible to get several credible local valuations and ask the agents to explain the evidence behind them. MoneyHelper’s dedicated guidance on quick house sales likewise recommends obtaining several valuations and shopping around rather than accepting the first quick-sale offer you receive.
Then compare the net outcomes, not just the headline prices.
Suppose three credible local agents suggest that a property would realistically sell for around £300,000, while a direct buyer offers £255,000. That offer is 15% lower, which means giving up £45,000 of the potential selling price.
The actual financial gap may be smaller once estate-agent fees, any legal costs the quick-sale company agrees to cover, mortgage payments and other costs of holding the property for longer are taken into account. But those savings need to be calculated rather than assumed. A £45,000 headline discount does not become inexpensive simply because the faster route avoids an estate-agent fee.
For someone who genuinely needs completion by a particular date, avoiding another broken chain may be worth a great deal. For somebody with no pressing deadline and a readily saleable property, the same discount may buy very little that they actually need.
Are they actually buying the property?
This is one of the most important distinctions to establish before going further. Some businesses genuinely intend to purchase the property themselves. Others operate as brokers, introducers or lead generators and will try to find another investor or buyer after the seller makes contact.
Those are materially different propositions because a direct purchaser can remove the conventional property chain and, if committed funds are already available, remove the buyer’s need to obtain an ordinary residential mortgage. But even then, “cash buyer” should not be treated as another way of saying guaranteed sale. Legal due diligence still has to take place, title problems can still emerge, and an offer may still be subject to valuation, survey or other conditions.
Ask who will actually appear as the purchaser on the contract, how the purchase is being funded and whether completion depends on the company finding another purchaser after you have agreed to proceed. Proof of funds should be capable of being verified through the professionals handling the transaction rather than resting solely on an advertising claim.
The National Association of Property Buyers says its membership is restricted to companies that buy properties directly rather than acting simply as brokers or introducers, so its current members register provides one useful independent check. Membership should be verified there rather than inferred from a logo on the buying company’s website.
Check who you’re dealing with before you commit
A polished website proves very little, and sellers should not assume that every company advertising itself as a professional cash property buyer is subject to the same compulsory regulatory and redress arrangements as an estate agent.
There is no dedicated statutory licensing regime for quick house sale companies. General consumer, property and contract law still applies, but voluntary industry membership and independent redress can provide useful additional safeguards. Government guidance recommends considering a firm belonging to the National Association of Property Buyers, whose members are required by the association to register with The Property Ombudsman.
You can verify the relevant redress arrangements through The Property Ombudsman’s consumer service rather than relying solely on logos or claims made by the company itself. Membership does not tell you whether a particular offer represents good value or guarantee that a transaction will complete; it tells you something narrower but still useful about the standards and complaints process the business has agreed to follow.
You should also establish the company’s full legal name and check it through the official Companies House service. That can show its registered details, officers, filing history, previous names, charges and insolvency information.
Companies House registration is not government approval of the company, and a recently incorporated business is not automatically an unreliable one. The purpose is to check that the legal entity matches what you have been told and to identify anything that deserves further explanation.
Look carefully at the contractual paperwork too. A website may say “we buy houses” while the documents reveal that another company or investor will ultimately acquire the property. What the agreement actually says matters more than the marketing language surrounding it.
The moment the price can change
The first number you hear may not be the final offer. Some businesses provide an initial estimate based on information supplied online or over the telephone and only reach a firm figure after viewing the property, checking the title or carrying out further due diligence.
There is nothing inherently improper about a price changing because genuinely new information has emerged. An undisclosed structural problem, a defective title or something materially different from the original description can alter the economics of a purchase.
The concern is different where an attractive initial figure gets a seller committed, competing buyers or estate agents are dismissed, an exclusivity agreement is signed, and the price then falls close to completion without a convincing new reason.
Before proceeding, ask whether the number you’ve been given is an estimate, a provisional offer or a final offer, and establish what precisely can still cause it to change.
That question goes to the heart of the certainty you are supposedly buying. An advertised seven-day completion means little if the offer remains provisional until day six. An attractive “cash offer” means less if the company still needs to find another investor before it can proceed. “No fees” is of limited comfort if the purchase price itself can be reduced substantially at a late stage.
The better measure of certainty is therefore not the headline completion promise. It is how many things are still capable of changing between the figure you are offered today and the amount transferred on completion.
Before you sign, get six answers in writing
For this kind of transaction, a short checklist genuinely earns its place. Establish:
- Who is actually buying the property? Get the legal name of the intended purchaser and establish whether the business you’re speaking to will be the buyer or is introducing somebody else.
- How is the purchase being funded? Find out whether it depends on external finance or another buyer and how the availability of funds will be verified.
- Is the price firm? Establish whether it remains subject to inspection, valuation, survey, legal checks or any other condition, and what could cause it to change.
- What will you pay? Check fees, legal costs, survey costs, withdrawal charges and anything payable if the transaction does not complete.
- Are you restricting your ability to sell elsewhere? Understand any exclusivity, lock-in, option or other agreement before signing it, including how long it lasts and how you can get out of it.
- Exactly when can they complete? Ask what has to happen before the advertised completion timetable becomes realistic and what could delay it.
A company unwilling to answer straightforward commercial questions in writing is giving the seller useful information, even if it isn’t the information they hoped to receive.
If the property is already being marketed by an estate agent, check your existing agency agreement before accepting a direct offer. Ending the advertising does not necessarily end the agent’s entitlement to commission. Sole-agency or sole-selling-rights clauses, notice periods and previous introductions can all matter, and in some circumstances a seller can become liable for fees even where the eventual buyer arrives through another route. GOV.UK’s guidance on estate-agent agreements explains why those terms need checking before changing how the property is sold.
You should also have your own independent conveyancer or solicitor review anything that restricts your ability to sell elsewhere, gives somebody an option over the property or otherwise goes beyond an ordinary straightforward sale contract. A buying company may offer to cover legal costs or suggest a firm accustomed to fast transactions, but the person advising you about the agreement should be acting for you.
If the company offers to pay your legal bill, establish whether that remains available if you choose your own lawyer and whether any money becomes payable if the transaction fails to complete.
What else is on the table?
A quick house sale company is not the only route when time matters.
A property priced deliberately to attract a proceedable open-market buyer may sell substantially faster than local averages, particularly if the seller prioritises a chain-free or financially qualified purchaser rather than simply accepting the highest offer.
Auction is another established route. An unconditional traditional auction can create a legally binding contract when the hammer falls if the reserve is met, giving a much clearer timetable than an ordinary private-treaty sale. Other auction models work differently and can involve reservation arrangements, longer completion periods and different fee structures, so “auction” should not be treated as one single product.
There are also situations where the real problem is not the method of sale. If repossession is driving the urgency, talking to the lender early may provide enough time for a normal voluntary sale. If an agreed transaction has just collapsed, approaching previous interested buyers may preserve considerably more equity than accepting a heavily discounted direct offer. If a property has simply sat unsold for months, pricing or marketing may be the underlying problem.
The quickest route is therefore not automatically the route branded as a quick sale.
The honest calculation
Before proceeding, put two numbers side by side.
The first is the realistic net amount you would expect to retain from an ordinary sale after likely estate-agent and legal costs and the additional costs of owning the property until completion.
The second is the net amount the quick-sale transaction would put in your hands after every fee, deduction and condition has been accounted for.
If the property is mortgaged, obtain an up-to-date redemption figure first and include any other borrowing secured against the property. A substantial quick-sale discount can consume remaining equity surprisingly quickly. If the proposed selling price will not clear the mortgage and other secured debts, that needs resolving with the relevant lender and conveyancer rather than assuming the transaction can simply complete in the usual way.
Once you have the two realistic net figures, look at the difference.
That number is effectively what you are paying for speed, convenience and reduced transaction risk.
Once expressed that way, the decision often becomes clearer. A seller might knowingly give up £10,000 or £20,000 because missing a deadline would cost them even more, because an onward transaction matters enormously, or simply because certainty has exceptional personal value at that point. Another seller may discover they are preparing to surrender tens of thousands of pounds to solve a problem that a realistic asking price and a few extra weeks could solve instead.
Neither decision is automatically irrational.
The mistake is making it without knowing what the certainty actually costs.
A reputable quick-sale company should be able to explain what it is buying, how it has reached its figure, what could still change that figure and what the seller is committing to in return. The seller’s job is to make sure the price of convenience is visible before convenience becomes difficult to walk away from.
Important: This article provides general consumer information and does not recommend or endorse any particular property buying company. The commercial principles apply broadly across the UK, but property law and conveyancing procedures differ between England and Wales, Scotland and Northern Ireland. Obtain independent legal advice before signing an exclusivity agreement, option, restriction or other contractual document affecting the sale of your property. If financial difficulty or threatened repossession is driving the decision, consider obtaining independent debt or legal advice before accepting a substantially discounted sale.

