

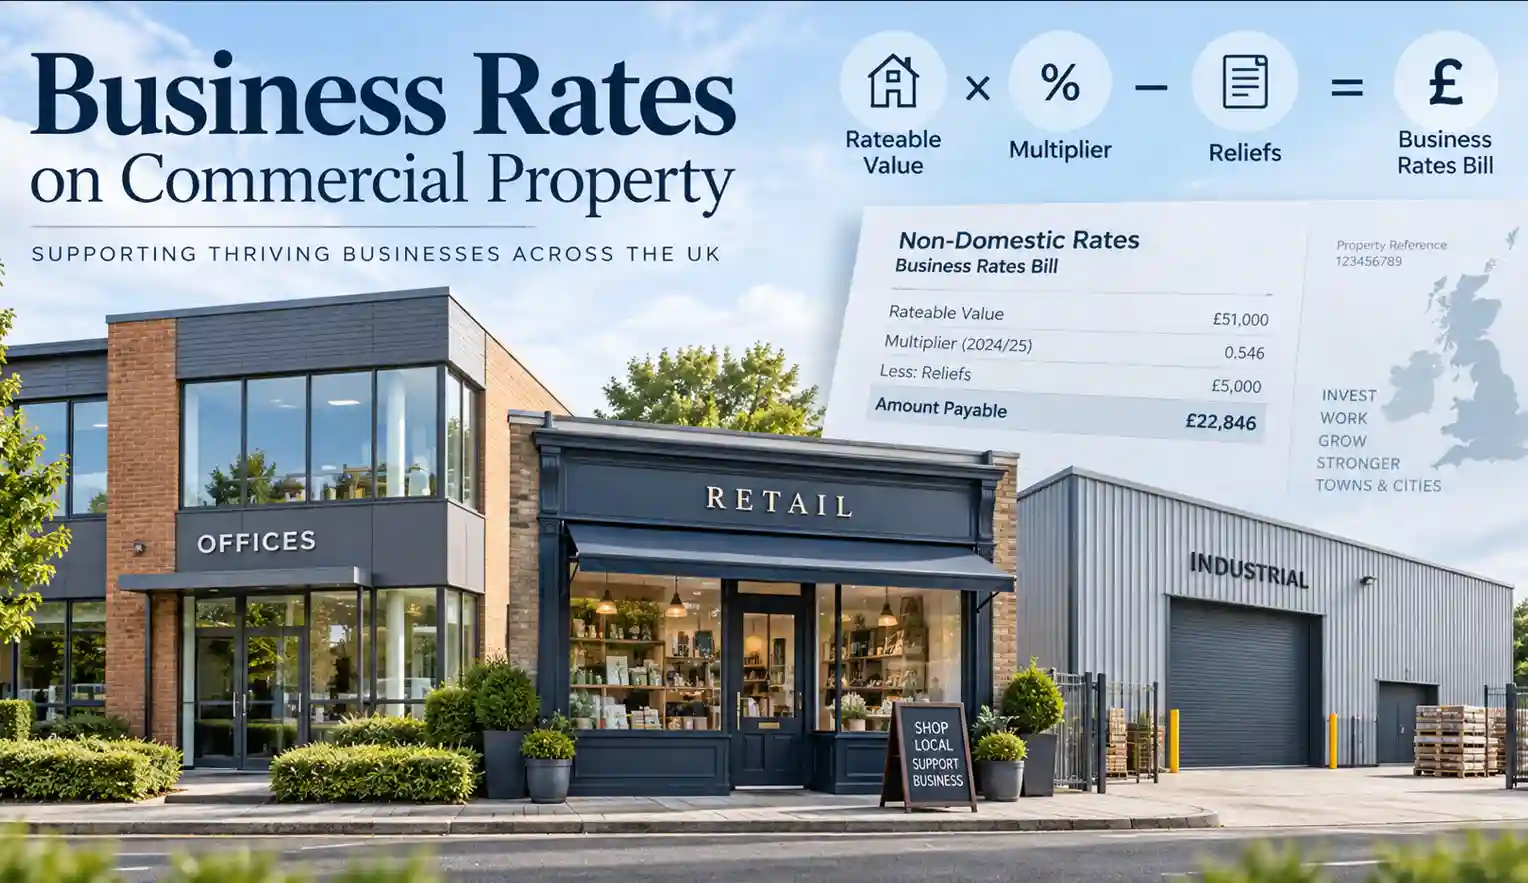
A business rates bill lands and it is higher than last year’s. The instinctive question is often: “Why has my property gone up in value?”
That may be the wrong question.
The final bill is the result of several different parts of the rating system interacting. The property’s rateable value may have changed. The multiplier applied to that value may have changed. A relief may have been gained or lost. Transitional protection may be limiting an increase following revaluation. The property itself may have moved into a different multiplier category.
A rateable value can rise without the bill increasing by the same percentage. A business occupying two identically valued properties can potentially receive different bills because their use, relief position or transitional treatment differs.
Understanding a bill therefore means working backwards through the calculation rather than judging the final number in isolation. That became particularly important on 1 April 2026, when new rateable values took effect across England and Wales and England simultaneously moved to a substantially different multiplier structure.
The detailed billing rules below distinguish between England and Wales where they differ. Scotland and Northern Ireland operate separate non-domestic rating systems.
Start by separating the rateable value from the amount actually payable
Rateable value is not the business rates bill, and it is not intended to be a live estimate of what the property would sell for.
For the 2026 rating list, the Valuation Office assessed non-domestic properties in England and Wales by reference to their rental value at a fixed date: 1 April 2024. Those new values came into effect on 1 April 2026 and form the basis of the current list. The government’s 2026 revaluation guidance makes the distinction explicitly: the rateable value provides the valuation base from which local authorities calculate the bill; it is not itself the amount payable.
That two-year gap matters. A property being let for £80,000 today does not automatically require a rateable value of £80,000, just as a tenant paying £100,000 under a lease agreed several years ago has not proved that a £75,000 rateable value is wrong. The rating assessment is based on a statutory valuation date and valuation assumptions rather than simply copying the rent payable under the occupier’s particular lease.
The calculation can therefore be understood as four connected stages. Rateable value establishes the tax base. The appropriate multiplier converts that value into a headline liability. Reliefs, transitional arrangements and any other relevant adjustments alter that result. The council’s bill is the final output.
More than one stage can change at the same revaluation. An occupier might see its rateable value rise while the multiplier falls. Another business might experience only a modest valuation movement but lose a relief or move into a different multiplier category. A large movement in the bill does not, by itself, identify which part of the calculation caused it.
How the 2026 rateable value was actually arrived at
Most ordinary commercial properties are valued by analysing rental evidence from comparable premises, but the method depends on the property.
Offices are generally assessed using rental comparison, commonly on a rate per square metre of net internal area. Factories, workshops and warehouses are also usually rental-comparison properties, although they are typically measured on gross internal area and characteristics such as size, age, location, eaves height, heating, land and other physical features can influence the analysis.
Shops are heavily influenced by the rental tone of their particular trading location and the configuration of the space. Some properties for which straightforward rental evidence is less suitable can be approached differently. Trading potential is relevant to the assessment of a number of hospitality and leisure properties, while specialist properties can require other recognised valuation methods.
The Valuation Office’s current guidance on how non-domestic property is valued explains the three main approaches: rental comparison, receipts and expenditure, and contractor’s basis.
For an occupier checking its own assessment, the important point is not to become a rating valuer. It is to identify what evidence the assessment is actually based upon and ask whether the property has been compared with the right market.
An office occupier should be looking at how its floor area, specification, parking and location compare with the valuation scheme and relevant nearby offices. An industrial occupier might find differences in eaves height, yard provision, heating, land or building age explain why superficially similar warehouses carry different assessments.
The Valuation Office’s online services allow ratepayers to view how their property has been assessed and compare its rateable value with similar properties. That is a much stronger starting point than deciding that the number “looks high” because it differs from the contractual rent.
In England, the multiplier system changed significantly in April 2026
England moved from two principal national multipliers to five for the 2026–27 financial year. The change matters because two properties with the same rateable value can now have different headline liabilities according to their use.
The current England multipliers are:
| Property | 2026–27 multiplier |
|---|---|
| Qualifying retail, hospitality or leisure property below £51,000 RV | 38.2p |
| Other property below £51,000 RV | 43.2p |
| Qualifying retail, hospitality or leisure property from £51,000 to £499,999 RV | 43.0p |
| Other property from £51,000 to £499,999 RV | 48.0p |
| Any property with RV of £500,000 or more | 50.8p |
These are not simply five different relief percentages. The two lower retail, hospitality and leisure rates are part of the multiplier structure itself. The government’s 2026–27 business rates multiplier guidance confirms both the five headline multipliers and the wider 2026 revaluation support package.
There is an additional temporary complication for 2026–27 only. Ratepayers who do not receive Transitional Relief or Supporting Small Business Relief generally have a 1p Transitional Relief Supplement added to the relevant multiplier. It was introduced to help fund the transitional scheme and applies for one year from 1 April 2026. A property whose headline multiplier is 38.2p can therefore be calculated using 39.2p where the supplement applies; one on 43.2p can effectively use 44.2p. Ratepayers receiving Transitional Relief or Supporting Small Business Relief do not pay that supplement.
That distinction is important when checking an actual bill. The headline multiplier shown in national tables is not necessarily the complete rate used in the final 2026–27 calculation.
Classification also matters. A £40,000 qualifying shop and a £40,000 office have identical rateable values but start from different multipliers.
Reliefs then sit on top of that structure where the ratepayer qualifies.
Small Business Rate Relief in England, for example, is a separate scheme. A qualifying business occupying one property with a rateable value of £12,000 or less can receive 100% relief, tapering between £12,001 and £15,000. A property with a £40,000 rateable value does not qualify for Small Business Rate Relief merely because it uses the small-business multiplier.
Transitional Relief is different again. Following the 2026 revaluation, England limits how quickly certain bills can increase as a result of the new valuation. For 2026–27, the permitted increase depends on the property’s rateable-value band, and the protection is applied automatically by the council where the criteria are met. It phases an increase rather than proving that the underlying rateable value is wrong.
Empty property rules create another layer of liability rather than changing the valuation itself. In England, most empty commercial properties receive three months without business rates before full liability normally resumes; qualifying industrial premises such as warehouses receive a further three months. Other exemptions can apply in particular circumstances.
So “my property is empty”, “my valuation is too high” and “my bill has risen too quickly” are three different questions within the same tax system.
Checking the valuation still means Check, Challenge and potentially Appeal
The Check stage has not been abolished for the 2026 rating list.
Current Valuation Office guidance for England and Wales continues to use the Check, Challenge, Appeal process. A ratepayer who wants to dispute the valuation must normally first raise a Check case to confirm or correct the property information held by the Valuation Office. Once the Check process has reached the appropriate stage, the ratepayer can submit a Challenge against the valuation. If the Challenge does not resolve the dispute, the matter can potentially proceed to the independent Valuation Tribunal.
The Valuation Office’s current challenge guidance confirms that a Check must normally be raised and decided before a Challenge can be submitted.
That sequence matters because there is a fundamental difference between incorrect property facts and disagreement over valuation. If the Valuation Office has recorded the wrong floor area, omitted a material characteristic, treated two properties as one or failed to reflect a relevant physical change, the factual basis may need correcting. If the factual record is right but the rate per square metre or other valuation input appears excessive compared with genuine evidence, the dispute moves into valuation territory.
The strongest challenge is therefore not “our rates are too expensive”. It is a case supported by evidence showing what is wrong with the assessment: inaccurate property details, inappropriate comparables, a valuation methodology issue, an incorrect effective date, a split or merger issue or another recognised ground.
Ratepayers should also be cautious about firms promising guaranteed reductions purely because a bill has increased after the 2026 revaluation. A national revaluation is specifically intended to redistribute liability according to changes in rental values across markets and sectors. A higher assessment may be inconvenient and still be correct.
Property changes matter — but the new duty to notify is not yet mandatory
The other major correction to make to the original draft concerns the new statutory duty to notify the Valuation Office.
The original draft treated that duty as having gone live on 1 April 2026. Current government guidance says otherwise.
HMRC’s August 2026 business rates duty-to-notify guidance says the new duty will not become mandatory before 2029. The planned online service and implementation timetable are under review, and the government’s current instruction is that businesses do not need to take preparatory action yet.
That should not be confused with the broader need to keep property and billing information accurate under the existing system.
Physical changes can still affect a rating assessment. Extending a building, creating a mezzanine, splitting one unit into several, merging premises, substantially altering the accommodation or changing the characteristics relevant to valuation can all affect how the property should appear in the rating list.
There can also be situations in which a temporary change in the locality or physical circumstances affects rental value and may support a request to alter the assessment.
The practical discipline remains sensible: if the premises have changed materially, compare the current Valuation Office record with the property that actually exists and establish whether the assessment remains correct. But businesses should not be told they are already breaching the new 2023 Act duty merely because the future mandatory notification regime has not yet been complied with.
That regime is still to come.
England and Wales share the 2026 revaluation, but they do not share the same bill calculation
This distinction is particularly important for a UK-wide property publication.
The Valuation Office undertakes the rating valuation work for properties in both England and Wales, and both nations moved onto the 2026 list on 1 April 2026 using the 1 April 2024 valuation date.
The billing systems then diverge.
England has the five-multiplier structure described above, together with its own relief and transitional arrangements.
Wales introduced its own three-multiplier system for 2026–27. Welsh Government guidance sets a 0.350 retail multiplier for qualifying smaller retail properties, a 0.502 standard multiplier for most properties and a 0.515 higher multiplier for higher-value properties. The eligibility boundaries and relief arrangements are Welsh rules rather than extensions of England’s RHL system. The current rates are set out in Business Wales’ non-domestic rates multiplier guidance.
That means an occupier should not read that an English café qualifies for the 38.2p RHL multiplier and assume a Welsh property is treated identically.
Scotland goes further in its divergence. Non-domestic rates operate under the Scottish system, with valuations handled through Scottish Assessors and bills calculated using Scottish poundage and relief schemes.
Northern Ireland has another separate regime, administered by Land & Property Services.
For a multi-site business, “business rates” should therefore be treated as a family of related property taxes rather than one UK-wide calculation.
A worked England example: the rateable value is only the starting point
Take a qualifying retail shop in England with a 2026 rateable value of £40,000.
Its headline small-business RHL multiplier is 38.2p, producing:
£40,000 × 0.382 = £15,280
That is the calculation using the published headline multiplier, not necessarily the amount that will appear before other adjustments on the 2026–27 bill.
Assume, for illustration, that the shop receives neither Transitional Relief nor Supporting Small Business Relief. The temporary 1p Transitional Relief Supplement then applies, taking the effective rate for this part of the calculation from 38.2p to 39.2p:
£40,000 × 0.392 = £15,680
Further eligible reliefs or adjustments would then affect the final amount payable.
The shop does not qualify for Small Business Rate Relief simply because its rateable value is below £51,000. That relief ends at £15,000 RV; the £51,000 threshold determines which multiplier applies, not eligibility for Small Business Rate Relief.
Now compare an otherwise equivalent non-RHL office with exactly the same £40,000 rateable value. Its headline multiplier is 43.2p:
£40,000 × 0.432 = £17,280
On the same assumption that neither Transitional Relief nor Supporting Small Business Relief applies, the 1p supplement takes the effective rate to 44.2p:
£40,000 × 0.442 = £17,680
The two properties have exactly the same rateable value, and the temporary supplement adds £400 to each example. Yet the office’s starting liability remains £2,000 higher because the underlying multiplier category is different.
That is the mechanism worth understanding. Rateable value answers one question: what valuation sits in the rating list? The multiplier and supplement translate that value into a tax charge, while reliefs and transitional measures can then alter what is actually payable.
Work backwards from the bill before deciding something is wrong
When a bill changes, the most useful first step is not immediately to challenge it. It is to identify which part of the calculation moved.
Has the rateable value changed between the 2023 and 2026 lists? If so, does the Valuation Office’s evidence and property description make sense?
Has the applicable multiplier changed because of the property’s value or use? Is the temporary 2026–27 Transitional Relief Supplement included?
Is Transitional Relief limiting an increase?
Has another relief been gained or lost?
Is the property empty, partly altered, subdivided or otherwise materially different from the assessment on record?
Only after those questions have been separated does it become clear whether the problem is the valuation, the multiplier calculation, transitional treatment, relief eligibility or simply a genuine consequence of the 2026 system.
The practical approach is therefore to read the bill backwards.
A high rateable value supported by the evidence is not corrected by arguing that the resulting bill is unaffordable. Equally, a bill correctly calculated from an inaccurate rateable value should not be accepted merely because the council’s arithmetic is right.
The useful question is not simply “why are my business rates higher?”
It is which number changed, why it changed and whether that particular part of the calculation is actually correct.
This article provides general commercial-property and taxation information and does not constitute legal, rating, valuation, surveying, tax or accountancy advice. Non-domestic rating rules differ between England, Wales, Scotland and Northern Ireland and can change between rating years. Rateable values, multipliers, supplements, reliefs, transitional arrangements and challenge procedures should be checked against current official guidance and the circumstances of the individual property.

