

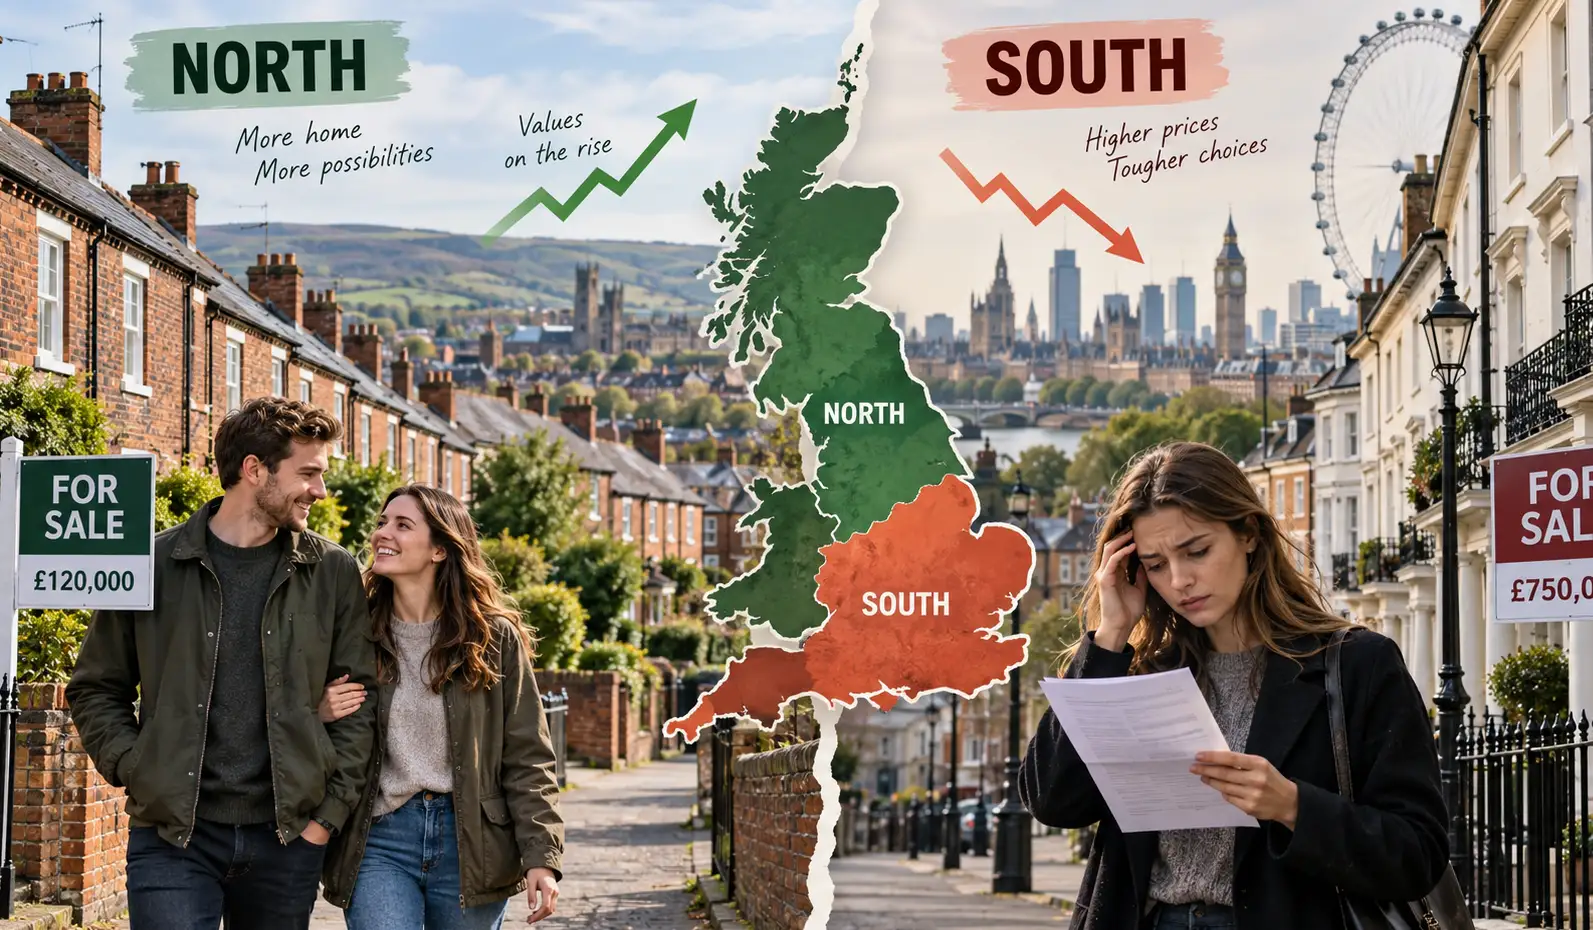
Through 2026, the gap between different parts of the UK housing market has become too wide to dismiss as statistical noise.
The official UK House Price Index for June had Northern Ireland up 9.2% on the year, the North West of England up 4.7% and the North East up 4.3%. London, meanwhile, was down 2.5%. The official UK House Price Index is a completed-transaction measure, so it is deliberately slower than portal and lender data, but it gives the clearest broad view of how differently the regions are moving.
Zoopla’s July achieved-price data told the same story through a different lens: UK growth of 0.9%, against 3.1% in the North West, while London was down 1.0% and the South East down 0.3%. Its August 2026 House Price Index also showed that buyers still had 5% more homes to choose from than a year earlier.
Different datasets. Different exact numbers. The same underlying pattern.
The instinctive response to a spread that wide is to ask which figure is “right”. The more useful response is to accept that several can be right at once, because there is no single UK housing market. There are dozens of overlapping regional and local markets responding to different levels of affordability, supply, buyer demand, property type and local economic conditions — occasionally in almost opposite directions at the same time.
A tale of two markets, at the same time
The North East and London illustrate the point unusually clearly.
The official June figures put the average North East home at about £166,000, against roughly £554,000 in London. The North East was up 4.3% on the year; London was down 2.5%.
Rightmove’s asking-price data sharpened the contrast further by August. London asking prices were 3.1% lower than a year earlier and homes were taking an average of 73 days to secure a buyer. In the North East, asking prices were 1.7% higher and the average time to secure a buyer was 52 days. The current Rightmove House Price Index also showed the total number of homes for sale at a 12-year high for the time of year.
Those aren’t directly comparable measures — the UK HPI records completed prices while Rightmove records newly marketed asking prices — but both point towards the same broad divergence.
Part of the explanation is simply the size of the mortgage involved.
Zoopla estimated that the rise in average five-year fixed mortgage rates from around 4% at the beginning of 2026 to about 4.8% by August reduced a typical buyer’s borrowing power by roughly 9%. On its assumptions, maintaining the same monthly payment would require around £10,200 more deposit in the North East, compared with about £35,500 in London.
The percentage shock is similar. The cash consequence isn’t.
That helps explain why higher-priced markets can weaken more sharply when borrowing becomes more expensive, while lower-priced regions retain more room for demand. It doesn’t mean every inexpensive area must rise or every expensive area must fall. It means the national mortgage market lands on very different local starting points.
Affordability is doing more work than sentiment
The clearest thread running through 2026’s regional data is that relatively affordable markets have generally proved more resilient than the most expensive parts of southern England.
This isn’t because buyers in one region are inherently more optimistic than buyers somewhere else. Much of it is arithmetic. The larger the mortgage required, the greater the cash effect of a given change in interest rates. Where prices already sit high relative to local incomes, there is less room for buyers simply to absorb another increase in monthly repayments.
That doesn’t make affordability a universal law. A cheap housing market can still weaken if employment deteriorates, population falls, too much similar stock reaches the market or buyers simply don’t want the homes available. Equally, an expensive area can remain strong where incomes, wealth and demand are unusually deep.
But during a period in which borrowing costs are constraining buyers, the starting price matters.
Local jobs and incomes shape the depth of demand
Beneath the mortgage-rate story sits a slower-moving question: how many households in an area have the income, security and reason to buy there?
Large employment centres, expanding industries, universities, hospitals and good access to well-paid jobs can support a deeper pool of potential buyers. Areas dependent on a narrower employment base may have less underlying demand, even when headline property prices appear relatively affordable.
The relationship is rarely immediate. A new employer arriving doesn’t automatically add a fixed percentage to local house prices, and an improving local economy doesn’t mean every neighbourhood benefits equally. Wages, commuting patterns, housing supply and the type of stock available all influence how stronger employment eventually feeds through.
The useful point is narrower: property demand ultimately has to be supported by people who can and want to live in the area. National mortgage rates affect those buyers, but they don’t create the local economy underneath them.
Supply doesn’t move at the same pace everywhere
Housing supply is local in a way national averages struggle to show.
By August, Zoopla was recording 5% more homes for sale than a year earlier, while Rightmove said stock was at a 12-year high for that point in the year. The effect of that extra choice is not uniform, however. Rightmove’s data showed substantially longer times to secure a buyer in London than in the North East.
That doesn’t prove every London seller is struggling or every North East seller has buyers queueing at the door. It does show how the balance between available stock and active buyers can differ meaningfully by region.
Supply can diverge inside one town too. A large pipeline of newly completed flats may put pressure on resale flats without doing much to the price of family houses nearby. An area with very little suitable family stock can remain competitive even while its wider local authority appears subdued.
This is why the number of homes for sale only becomes useful when you ask: homes of what type, at what price, competing for which buyers?
Demographics move the goalposts locally
Who is actually buying in an area shapes its market as much as how many properties are listed.
An area attracting downsizers from a more expensive region can receive demand from purchasers bringing substantial existing equity. A university town may have a different balance of first-time buyers, landlords, students and parents buying accommodation. Places with strong retiree demand can see bungalows and smaller houses behave differently from larger family homes.
None of those groups responds to affordability in exactly the same way.
A first-time buyer relying on a 90% mortgage is highly exposed to mortgage rates and lender affordability. A downsizer selling an expensive mortgage-free home may be far less sensitive to borrowing costs. A cash investor is making a different calculation again.
Put enough of one buyer type into a local market and its behaviour can start to differ noticeably from the national picture.
Investor and landlord demand affects some sectors more than others
Landlord demand isn’t spread evenly across the housing market. It tends to matter more in particular price bands, property types and locations where rental demand and yields make the numbers workable.
That means a change in investor appetite can have a visible effect on one part of a local market without saying much about another. A city-centre flat market with a large investor presence may react differently from suburban family houses largely bought by owner-occupiers.
It is easy to overstate this effect, however. A weak flat market isn’t automatically evidence that landlords have withdrawn, just as rising prices don’t prove investors are driving them. Mortgage costs, service charges, lease terms, first-time-buyer demand and the supply of competing flats can all be moving at the same time.
The sensible approach is to treat investor demand as one possible local force, not the default explanation for every price movement.
Leasehold and service charges have become a genuine price factor
Flats provide one of the clearest examples of property type cutting across regional averages.
The England component of the June UK HPI showed flats and maisonettes down 2.3% annually while semi-detached homes were up 3.2%. In London, flats and maisonettes were weaker still.
Zoopla’s June research found the gap between house and flat prices had widened to the largest in its 30-year series. Its analysis of the house-to-flat price gap pointed to lease length, service charges and ground-rent terms as factors buyers have to weigh, while noting that the equivalent gap had moved much less in Scotland, where the long-leasehold system does not operate in the same way.
That doesn’t establish leasehold as the sole reason flats have underperformed. Affordability, buyer preference, investor activity and the supply of flats also matter.
But tenure and ongoing building costs are now a genuine part of the pricing discussion in England and Wales. The government was still progressing reforms to service-charge transparency and wider leasehold protections during summer 2026, set out in its July update on stronger leasehold protections.
For a buyer, that makes tenure and building costs part of the local price story rather than a technical detail to think about only after agreeing a purchase.
Transport and infrastructure: real, but not automatic
It’s tempting to reach for “a new station means house prices rise” as a rule of thumb, but the effect is far less mechanical than the cliché suggests.
Infrastructure can support demand where it materially improves access to employment, schools, shops or other places people actually need to reach. But the value of that improvement depends on what transport existed before, how reliable the new connection is, whether buyers had already priced the scheme in during years of planning and construction, and whether the surrounding area contains the homes and amenities people want.
The same caution applies to regeneration announcements. A proposal isn’t the same thing as a completed improvement, and a completed improvement isn’t a guarantee of higher property prices.
Infrastructure is best treated as one component of local demand, not a shortcut to predicting the market.
Even a single postcode isn’t one market
Zoom in far enough and the same divergence that separates London from the North East can appear across a surprisingly short distance.
School catchments, flood exposure, road noise, parking, tenure, housing condition, plot size and even which side of a busy road a home sits on can divide buyers’ willingness to pay.
Lloyds illustrated how large those micro-market differences can sometimes become in 2026 by comparing the most expensive postcode in each region with the cheapest neighbouring postcode sharing its boundary. Across those deliberately selected examples, the neighbouring postcode was 28% cheaper on average, with the largest gap reaching 47%. Its postcode price-gap research is an extreme-case exercise rather than a typical-price guide, but it makes the broader point well.
Geographical proximity isn’t the same thing as market equivalence.
For an individual buyer or seller, recent evidence for genuinely comparable homes remains more useful than a regional average — and can be more useful than a postcode average too.
Sometimes the “price rise” is partly about what sold
There is another trap when reading very local house-price data: the mix of properties sold can change.
Imagine a small area where ten transactions complete in one month and most are two-bedroom terraces. The following month, ten homes sell again, but this time several are large detached houses.
The simple average sale price could rise sharply even if the underlying value of a typical terrace or detached house had barely changed.
The reverse can make an area appear to have suffered a sudden price fall.
This is one reason a proper house-price index does more than average whatever happened to sell. The official UK HPI uses mix adjustment and hedonic regression to account for characteristics including location, property type, floor area, number of rooms and whether a home is new or existing. The government’s UK HPI quality and methodology guide explains why this adjustment is needed.
This matters particularly when somebody sees a dramatic percentage change attached to a small town, postcode or local authority and assumes that every home there has moved by roughly the same amount.
At very local level, transaction numbers can be small and the official methodology itself warns that low sales volumes can make local figures volatile. A sharp one-month movement therefore deserves a second question: did comparable homes genuinely change value, or did a different mix of properties happen to sell?
That one question can prevent a surprising amount of bad market analysis.
Reading regional divergence without overreacting to it
The throughline across all of this is that “the housing market” is shorthand for a large number of local markets, each shaped by its own mix of affordability, employment, supply, demographics, property type and buyer profile.
Mortgage rates can then amplify the differences. When borrowing becomes more expensive, areas already stretched on affordability tend to feel more pressure; where prices and required mortgages are lower, buyers may have more room to absorb the change.
But no single factor explains every local movement.
Strong employment doesn’t guarantee rising prices if supply is increasing even faster. Limited supply doesn’t guarantee growth if buyers can’t afford what is being sold. A new railway doesn’t override an unattractive property. A national rate cut doesn’t instantly turn every weak local market into a strong one.
And a regional statistic can still tell you very little about the particular home you’re considering.
The most useful approach is therefore to work downwards: national conditions for context, regional data for direction, local supply and demand for the market you’re actually in, and recent genuinely comparable transactions for the property itself.
A UK-wide house-price figure sitting close to zero can be entirely consistent with one area rising strongly and another falling at the same time. That isn’t evidence that the statistics have failed.
It is what a housing market made up of thousands of different places looks like when those places stop moving together.
This article provides general property-market information and is not financial, mortgage, valuation or investment advice. House-price data can be revised and local market conditions may differ substantially from regional or national averages. Property values depend on the characteristics and circumstances of individual homes, so recent comparable evidence and appropriate professional advice should be considered where a specific valuation or purchase decision is required.

