

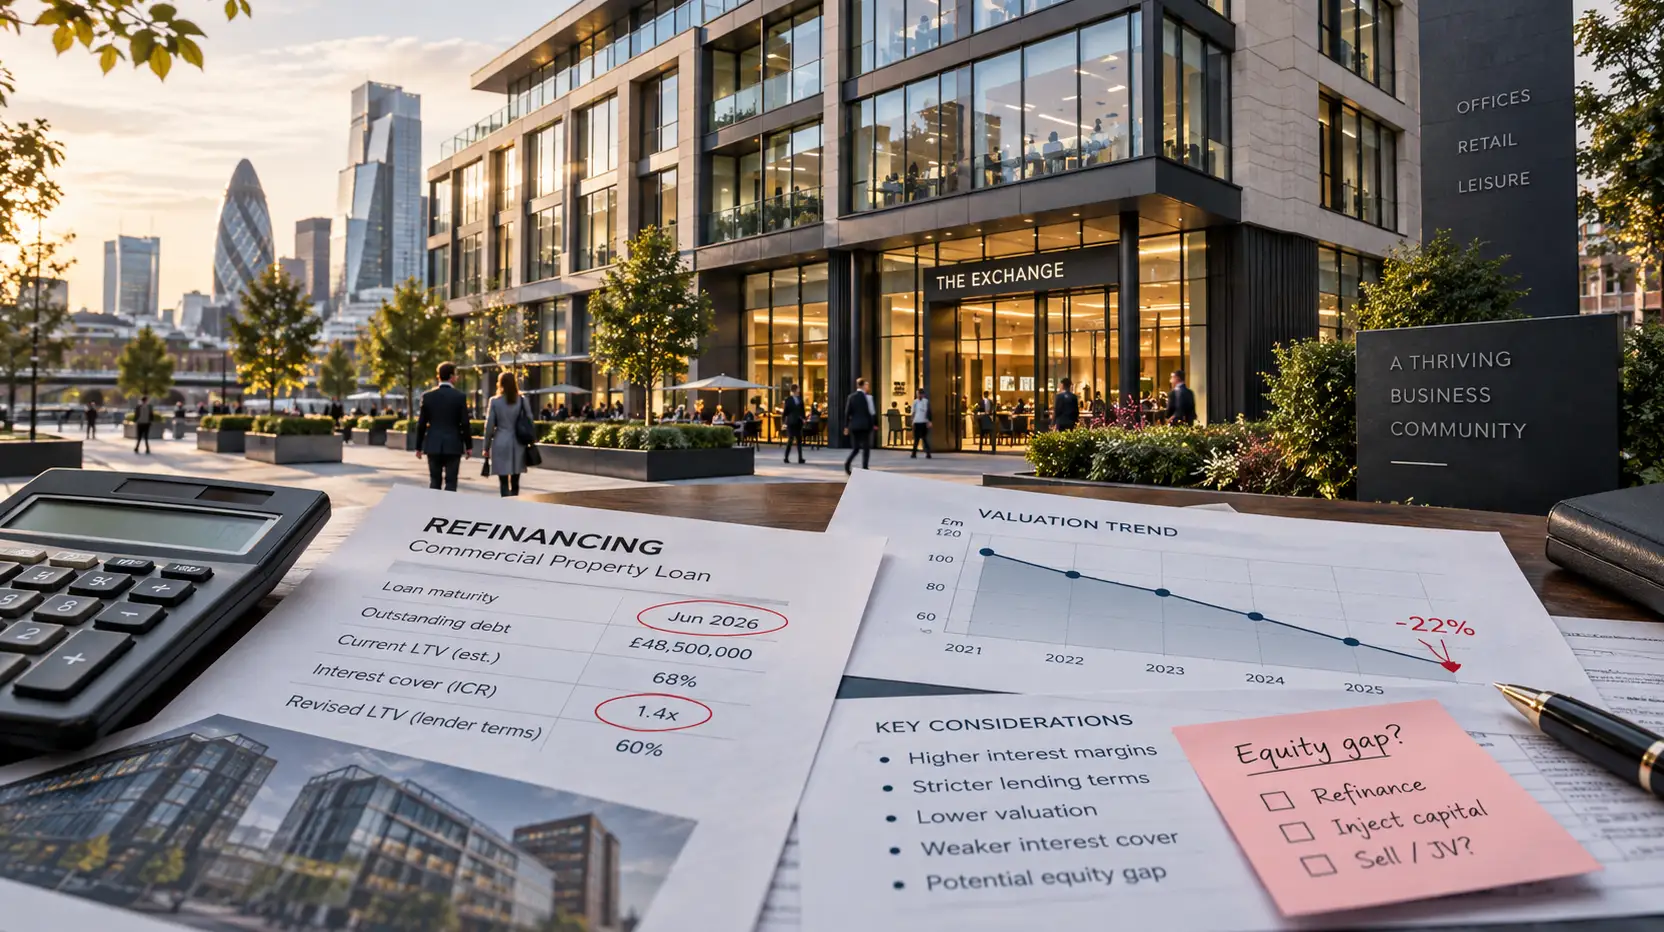
A borrower can pay every instalment on time, keep a building fully let and watch rent arrive exactly as forecast, yet still reach loan maturity to find that a new lender will advance substantially less than is needed to repay the existing facility. Nothing about the property’s operating performance has necessarily failed. The debt has, in effect, become difficult to replace on its original terms — because refinancing is not a reward for good payment history. It is a new lending decision, made against today’s valuation, today’s income tests, today’s borrowing costs and today’s appetite for the asset. Those conditions can move a long way without the landlord missing a single payment.
This is refinancing risk, and it sits apart from the operational and market risks investors spend most of their time monitoring. It can emerge in a fully occupied building with a strong tenant and years of clean payments — precisely the property that looks reassuring in a monthly management report. The risk becomes unmistakable when the borrower discovers how much debt the same asset can support at the end of its existing loan term. Because that liability falls due on a fixed date, the borrower cannot necessarily wait for market conditions to improve.
Why a healthy loan can still fail to refinance
Start with the maturity itself. Many commercial investment-property loans are interest-only, with the principal falling due at the end; others amortise during the term but still leave a substantial final balance. An asset can service its debt comfortably for years without generating the surplus cash needed to repay that balance. The expectation is often that the borrower will refinance, sell or contribute further capital, which makes the outcome depend on conditions in the lending and investment markets at a particular moment. Those conditions may bear little resemblance to the market in which the original loan was agreed.
Valuation is the most direct pressure. If investment yields have moved out — investors now require a higher return for the same income — the building can be worth less even when its rent is unchanged. The refinancing lender applies its loan-to-value limit to the valuation it accepts today, not the price paid or a valuation obtained five years earlier. Its permitted LTV may have fallen as well, particularly where the property is in a less favoured sector or location. A lower valuation and a tighter lending limit can therefore reinforce each other without any deterioration in rent collection.
Interest cover can be more restrictive still. Lenders test whether sustainable income supports the proposed debt at an assumed or stressed interest rate, not necessarily the rate the existing borrower has been paying. Some use debt yield as an additional safeguard, comparing net operating income directly with the loan amount. Just as importantly, the income a lender accepts may not be the rent shown on the latest tenancy schedule. Atom bank’s published investment-lending criteria use the lower of passing rent and 90% of the valuer’s gross market rental figure when assessing serviceability, with cover and stress requirements varying according to the product and circumstances. That is one lender’s policy rather than a market-wide rule, but it illustrates why an entirely current rent roll does not guarantee that every pound will count towards a new advance. The maximum new loan is governed by whichever applicable underwriting test produces the lowest acceptable figure.
Hedging and lease timing can make that calculation more uncomfortable. An interest-rate cap or swap may have protected cashflow during the loan term, but replacement protection can cost more, while terminating or restructuring an existing hedge may itself have a cost. Meanwhile, a single-let office building that had fifteen years of secure income at acquisition may have only five years left on the lease when the loan matures, perhaps with a break option sooner. The tenant may still be paying every invoice, yet the lender has far less contracted income beyond the refinancing date. Its view of tenant covenant, reletting costs, required works and future market rent may be more consequential than the historic payment record.
Lender appetite adds uncertainty that is harder to model. A bank may have reached its exposure limit for offices, changed its preferred loan sizes or withdrawn from a particular type of security. Debt funds and insurers may take a different view, but also demand different pricing, fees, structures or protections. A competitive debt market does not mean every property will qualify for the amount its owner needs.
A worked illustration
Take a hypothetical office asset valued at £20 million when a lender advanced £12 million against it — an opening loan-to-value ratio of 60%. The five-year loan is interest-only. Assume the building generates £900,000 of net operating income annually and the initial interest rate is 4%, making the annual interest bill £480,000. Income covers interest 1.875 times, and the borrower meets every payment throughout the term. At maturity, the rent and net operating income are unchanged, but yields have moved out and the valuation has fallen to £17 million. The refinancing lender is now willing to advance only 55% LTV, placing a ceiling of £9.35 million on the new loan and leaving £2.65 million to find against the outstanding £12 million.
That is only the valuation constraint. Suppose the prospective lender also requires income to cover interest 1.5 times at a 7% assumed rate. On £900,000 of accepted annual income, that test supports a loan of approximately £8.57 million: £900,000 divided by 1.5 and then by 7%. The interest-cover limit is lower than the £9.35 million LTV limit, so it controls the proposed advance. Instead of £2.65 million, the borrower now needs approximately £3.43 million of fresh capital to repay the original debt, before lender fees, valuation and legal costs or any hedge expenses. These are illustrative assumptions, not quoted market terms; actual lenders may use different income definitions, repayment profiles and tests.
The calculation shows why shopping for a higher LTV is not always enough. Even if another lender were prepared to lend against a greater percentage of the £17 million valuation, the income test could still prevent it advancing more than £8.57 million. Conversely, improving financeable income might raise the interest-cover ceiling without solving a binding LTV problem. The borrower needs to establish which constraint is actually creating the gap before spending time and money trying to overcome the wrong one. The building, throughout, has not missed its rent forecast or a loan payment; the refinancing market has simply changed the amount of debt it can support.
What lenders can do about a shortfall, and what it costs
A cash-in refinancing, with investors contributing enough equity to repay the old facility using a smaller new one, is the cleanest solution on paper. But it asks investors to commit further capital to an asset that may now be worth less, at a point when they could have other uses for that money. Selling another property to fund a paydown depends on portfolio liquidity and, potentially, the consent of lenders holding security over other assets. Bringing in a new equity partner can resolve the gap while diluting existing owners. Mezzanine or other subordinated finance may help in some cases, but costs more, requires an acceptable structure and does not make inadequate property income disappear. A proposal that increases total leverage may simply fail a different debt-service test.
An amend-and-extend agreement with the existing lender offers another route. The lender may agree to more time in return for a partial repayment, a higher margin, additional security, tighter covenants or restrictions on distributions. That can be commercially rational for both sides if a forced sale would destroy value and there is a credible plan to reduce the debt; it is not necessarily a favour, and the lender has no general obligation to agree. Crucially, a looming maturity shortfall is not the same as an existing covenant breach or payment default. What a lender can demand before maturity depends on the facility documents. Bayes Business School’s 2026 lending research estimated that 15–20% of commercial real estate loans lacked covenants allowing lender intervention before default. The absence of such provisions does not relieve the borrower of the obligation to repay when the facility falls due.
The better options tend to be available before that date is close. A tenant lease regear might extend contracted income, although any rent-free period or incentive granted in return needs to be included in the calculation. Planned works may protect the property’s lettability but require cash that could otherwise reduce debt. Retaining surplus rent for a partial paydown, resolving an approaching break, improving operating costs or agreeing a realistic extension timetable may all strengthen the financing case. None is automatically worth pursuing: the benefit depends on whether it changes the valuation, the lender’s accepted income, the debt balance or the risk that actually limits the new loan. The valuable exercise is to test those possibilities early, not simply ask more lenders for the same amount at the last minute.
Where this differs from the initial leverage decision
Choosing how much debt to take on at acquisition is a forward-looking capital-structure decision made when the investor has some control over the assumptions. Refinancing risk is what happens when that decision meets a market that has moved, at a date the borrower often cannot choose. An apparently conservative starting LTV may still produce a material shortfall if yields rise, interest cover tightens and the tenant’s remaining lease term runs down together. Nor does high starting leverage guarantee trouble where amortisation, rental growth or a stronger valuation have improved the position. The question at maturity is not whether the original gearing seemed prudent. It is whether the outstanding balance still fits the borrowing capacity of the asset — and, if it does not, who can provide the difference on acceptable terms.
The current UK picture
This is not an abstract risk in the UK market. The same Bayes Business School lending survey, published in May 2026, recorded £52.7 billion of new commercial real estate lending during 2025, up 29% on 2024, with around 60% of new lending involving refinancing. Nearly one-third of commercial real estate loans were refinanced during 2025. The same research estimated that approximately £33 billion, or 19% of the outstanding loan book measured, was scheduled to mature during 2026. Interest cover was below 1x for 13% of the loans tested, compared with 1% in 2016. That is material evidence of pressure beneath a market in which new loan volumes and competition for the strongest borrowers were improving.
The picture is not uniformly difficult, and presenting it that way would be misleading. Bayes found lenders reducing margins on prime assets and debt funds increasing their reported market share from 12% to 28%. CBRE’s mid-2026 capital-markets assessment described debt markets as liquid, with refinancing still expected to drive much of lenders’ activity. Savills Investment Management’s August 2026 debt assessment offered the perspective of a debt investor: property values have already repriced, while some older loans are maturing into a substantially higher cost of debt. From a new lender’s standpoint, a smaller loan against a rebased valuation can offer attractive security and returns; for the existing owner, the same transaction may demand an unwelcome equity cheque. There is no contradiction between abundant competition for prime debt and a refinancing problem elsewhere in the market. The terms attractive to today’s lender are not necessarily enough to repay yesterday’s loan.
Debt risk lives at maturity, not just at drawdown
The uncomfortable truth for any borrower is that a loan can perform perfectly for its term and still create a capital event when it ends. Monitoring rent, occupancy and arrears tells an investor how the property is operating. It does not tell them what a replacement lender will advance, because that calculation also depends on the valuation, the income it will recognise, lease duration, financing rates and the lender’s appetite for the sector. Even an apparently healthy asset can have too little room between its maturing debt and the amount the market will now lend.
The practical response is to model that room before maturity is imminent. Test realistic changes in value, accepted income, interest-cover requirements and LTV, then compare the lowest supportable refinancing amount with the debt that will actually fall due, including transaction costs. If there is a shortfall, identify which condition creates it and what changing that condition would cost. By the time the first binding refinancing offer exposes a gap, the opportunities to regear a lease, retain cash, arrange new equity or agree terms with the incumbent lender may already have narrowed. A good building and a clean payment record are worth having, but neither is a substitute for knowing how the debt ends.
This article provides general information and market analysis only and does not constitute property, investment, lending, legal or financial advice. Commercial lending terms and valuations depend on individual circumstances and market conditions. Obtain appropriate professional advice before making significant financing or investment decisions.

