

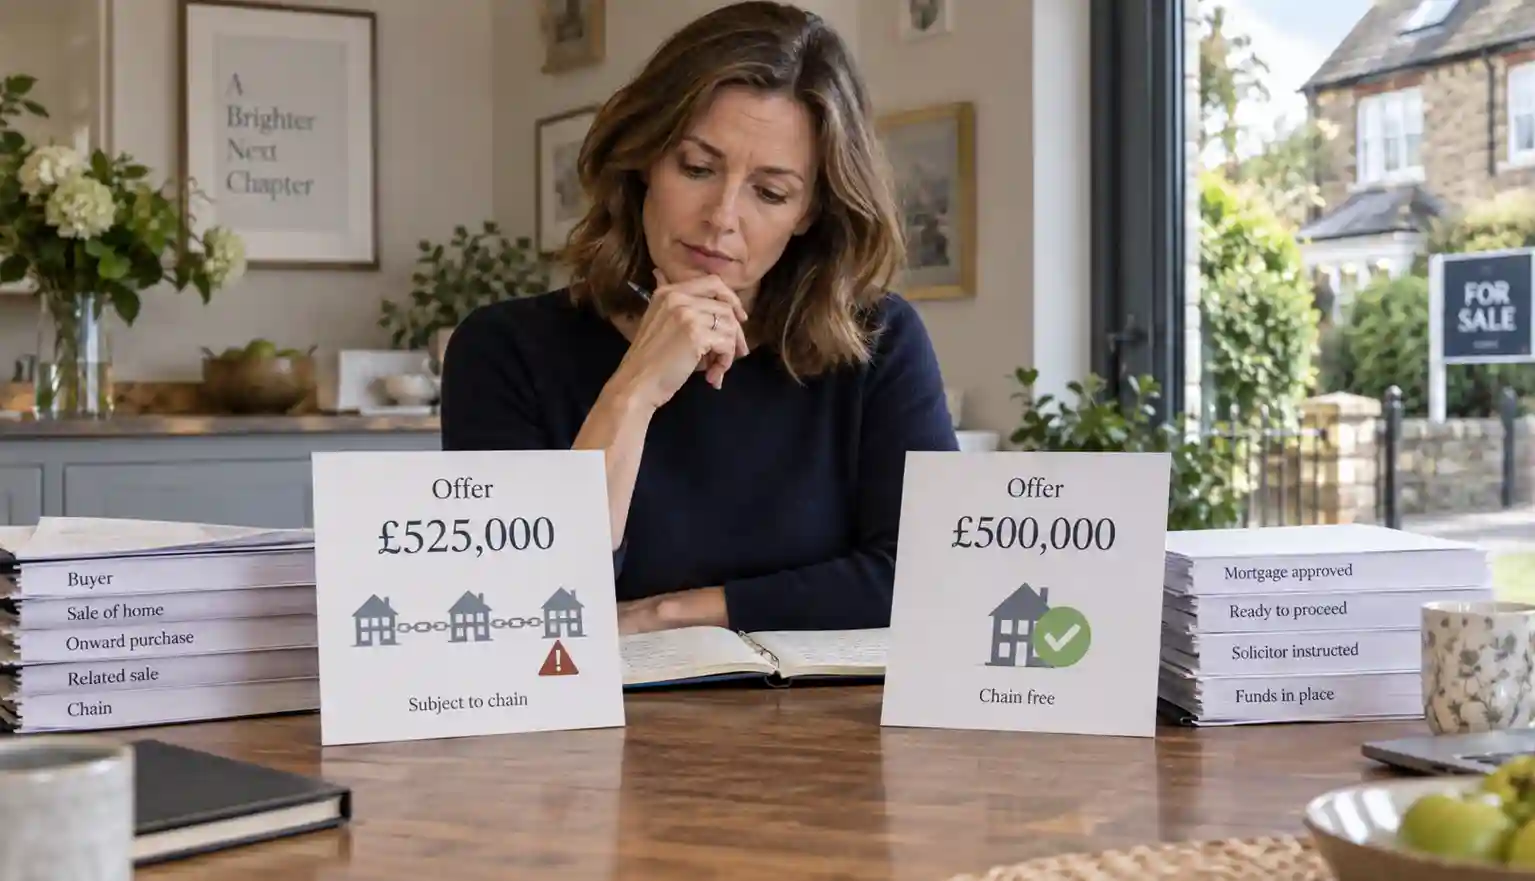
A seller with two offers on the table often assumes the decision is already made — take the higher number. Sometimes that’s exactly right. But the figure a buyer offers is only one part of what they’re actually proposing, and a seller who looks only at the headline price can end up choosing the offer more likely to unravel months into the transaction over one with a clearer route to completion.
The useful question isn’t simply who is offering the most. It’s what sits behind each offer, and how well that fits what the seller actually needs from the sale.
What an offer is really made of
Every offer carries at least four dimensions worth weighing separately: the price itself, the buyer’s chain position, how proceedable they genuinely are, and the timing or conditions attached.
A higher offer from a buyer who still needs to sell their own home carries different uncertainty from a slightly lower offer from someone who is chain-free and already has their finances in motion. Neither is automatically the wrong choice. The seller isn’t choosing only between two prices; they’re choosing between two routes to completion.
Consider a realistic hypothetical situation. A seller receives £310,000 from a buyer who is under offer on their own property but hasn’t yet exchanged, and £300,000 from a chain-free first-time buyer with a mortgage agreement in principle.
The £310,000 may still be the better offer if the seller has time, the chain is short and progressing well, and the extra £10,000 matters. But where the seller is already committed elsewhere and values certainty highly, the lower offer deserves more serious consideration than the headline figures alone suggest.
Even that apparently stronger buyer comes with a qualification. A mortgage agreement in principle is useful evidence, but it isn’t a mortgage offer. MoneyHelper describes it as an indication of what a lender might be prepared to lend following preliminary checks. The buyer still needs to make the full application, satisfy the lender and have the property accepted as suitable security.
A cash buyer isn’t automatically preferable either. The important question is whether the money is genuinely available when required. Someone who calls themselves a cash buyer because they won’t need a mortgage once another property has sold is in a different position from somebody whose purchase funds already exist.
The labels are useful shorthand. The evidence behind them matters more.
What to actually ask about a buyer before deciding
Is the buyer genuinely proceedable now, or does something important still need to happen first?
They may need their own property to sell, a mortgage application approved, investments converted into cash or money provided by somebody else. None automatically makes an offer weak, but the seller should understand which parts of the purchase are already in place and which are still dependencies.
What does their chain actually look like? “We’re under offer” doesn’t tell you very much on its own.
How many transactions sit below the buyer? Is their buyer proceedable? Have solicitors been instructed? Is the chain newly formed or already well advanced?
A buyer with a chain isn’t inherently a weak buyer. A short chain already progressing through conveyancing can present a very different risk from somebody whose own property isn’t yet on the market.
What evidence is there of the financial position?
For a mortgage buyer, an agreement in principle is useful but only one stage of the process. For a cash purchase, the agent should take reasonable steps to establish that the money genuinely exists and is available.
The seller doesn’t need access to somebody else’s private financial affairs. They do need enough verified information to understand how credible the purchase is.
What timescale does the buyer want, and does it fit the seller?
A buyer promising an unusually fast completion isn’t automatically stronger if the seller’s onward purchase won’t be ready. Equally, flexibility over dates can be particularly valuable where two transactions need to line up.
Sometimes the strongest offer is the one whose timetable works.
What else is attached to the offer?
A buyer may want particular fixtures included, specify a completion date or depend on selling their own property. And in England and Wales, even an apparently straightforward offer can still change before exchange if a survey, lender valuation or legal enquiry alters the buyer’s view of the transaction.
It is therefore more useful to think in terms of dependencies than to divide buyers into supposedly strong and weak categories.
A first-time buyer can still have mortgage difficulties. A cash buyer can still change their mind. A buyer in a chain can be highly proceedable.
The purpose is to understand this buyer, making this offer, rather than deciding from the label attached to them.
What a seller should expect their agent to establish
An estate agent should give the seller more than a list of offer amounts.
Under The Property Ombudsman’s Codes of Practice, member agents are expected to take reasonable steps while an offer is being considered to establish the source and availability of the buyer’s funds and tell the seller whether the buyer has a property to sell, requires a mortgage, claims to be a cash buyer or relies on a combination of these.
That investigation should put context around an offer. It should not decide which offers the seller is allowed to hear.
Agents must still pass offers to their seller client. Government guidance on offers and negotiations makes clear that an estate agent must inform the seller of offers received, and in England and Wales the seller remains free to accept or negotiate while the transaction is not yet legally binding.
Nor should a buyer gain an advantage because they agree to use the estate agency’s mortgage adviser, conveyancer or another linked service. Financial qualification should establish whether the buyer is realistically able to proceed, not determine whose offer receives the most favourable treatment.
The agent’s useful role is to explain what sits behind the numbers.
£315,000 from somebody whose own house isn’t yet on the market means something different from £312,000 from a buyer who has already sold and is well advanced. The seller may still prefer £315,000. But it should be an informed decision.
Buyer strength also shouldn’t be assessed once and then forgotten.
After accepting an offer, watch what actually happens. Does the buyer instruct their solicitor promptly? Does the mortgage application move forward? Is the survey booked? Does their chain continue progressing?
A buyer who looked exceptionally strong when the offer arrived but has made very little progress several weeks later no longer presents quite the same proposition. Conversely, a chain that initially looked uncertain can strengthen considerably as the transactions below it advance.
An accepted offer starts the sale. It doesn’t remove the need to monitor it.
Accepting an offer isn’t the same as being legally committed — and this varies across the UK
This is one of the more important points in the decision because the position genuinely differs depending on where the property is being sold.
In England and Wales, accepting an offer is not normally legally binding. The property is typically regarded as sold subject to contract, and either side can withdraw before written contracts are exchanged.
During that period the buyer may still have a mortgage valuation, survey, searches and legal enquiries to complete. GOV.UK guidance confirms that an accepted offer does not make the sale legally binding; that happens at exchange of contracts.
Northern Ireland follows a broadly similar sequence, with survey, mortgage and legal work taking place after an offer is accepted and the transaction becoming binding at exchange of contracts. nidirect’s home-buying guide sets out that process.
That gap between accepted offer and binding contract is one reason the buyer’s ability to keep progressing matters.
Scotland works differently.
Offers are normally made formally through solicitors and can include conditions covering matters such as the entry date and items included in the sale. Where several buyers are interested, the seller may set a closing date and does not have to accept the highest bid if another offer has terms they prefer. Scottish Government guidance on closing dates and offers makes that clear.
After an offer is accepted in principle, the solicitors negotiate the detailed terms through missives. The sale becomes legally binding once those missives are concluded. Scottish Government guidance on missives explains that this concluding missive creates the binding contract.
So a seller moving between jurisdictions shouldn’t assume that “offer accepted” carries exactly the same practical or legal meaning everywhere.
The strongest offer, for this seller, in this situation
None of this produces a universal ranking where cash always beats a mortgage, chain-free always beats a chain, or certainty always beats price.
The difference between the offers matters as much as the buyers behind them.
A seller choosing between £400,000 and £399,000 may place considerable weight on which buyer presents the cleaner route to completion. A seller choosing between £400,000 and £430,000 faces a very different trade-off.
There is no fixed percentage at which certainty suddenly becomes worth more than price.
A seller under real time pressure — perhaps because their onward move depends on completing within a particular window — may reasonably prefer a slightly lower buyer with fewer dependencies. A seller with no chain, no deadline and more tolerance for delay may reasonably accept additional risk for a materially higher figure.
The important thing is to understand what the extra money is buying you and what additional uncertainty comes with it.
Price only matters if the transaction reaches completion. Buyer strength only matters if the evidence behind it is real. And neither can be judged properly without considering what this particular seller needs.
The right decision is therefore the one that weighs the actual evidence around each buyer against the difference in price, the likely route to completion and the seller’s own circumstances — not a rule that the biggest number always wins, and not a rule that certainty always should.
Important: This article provides general information about residential property offers and sale processes, not legal, mortgage or financial advice for a particular transaction. The point at which a property sale becomes legally binding and the procedures around offers differ across the UK. Sellers should take advice from their estate agent and legal representative on the facts of their own sale before making decisions with significant financial or contractual consequences.

