

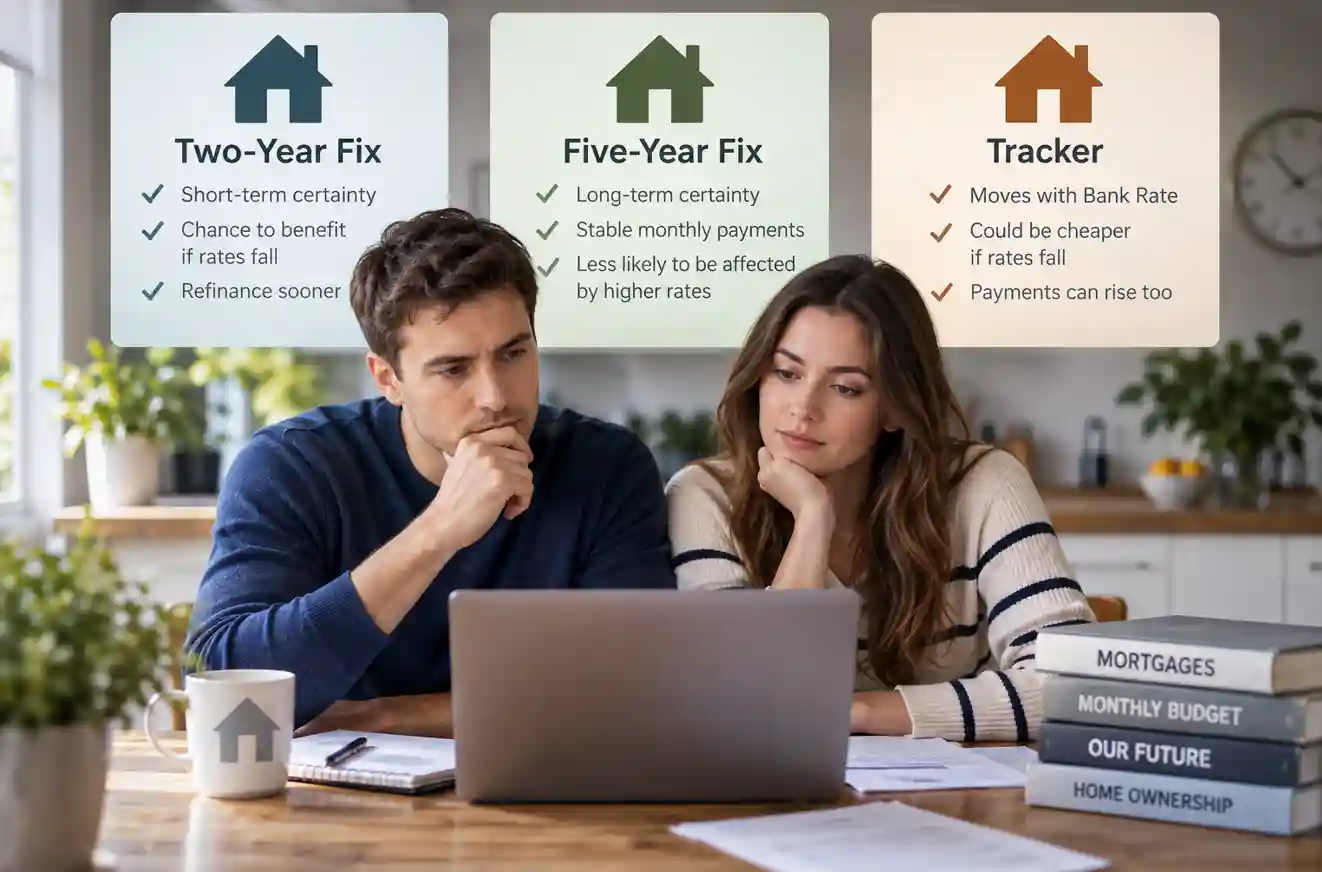
Two households, both borrowing £250,000 in September 2026, could reasonably make opposite decisions and both be right.
The first has a large cash buffer, two secure incomes and a mortgage that represents a modest share of what they earn. The second is stretching to a high loan-to-value, has one income that may dip in the next couple of years around a planned career break, and holds little in savings once the deposit and moving costs are accounted for.
Offered the same three broad choices — a two-year fix, a five-year fix and a tracker — these households aren’t really facing the same decision at all, even though the product descriptions look identical.
That’s the part most rate comparisons miss. The question isn’t simply “which is cheapest?” Nobody, including the lender setting today’s price, knows with certainty where mortgage rates will be in two or five years.
The more useful question is: how much uncertainty can your household actually absorb if your choice turns out to be wrong?
What each option actually commits you to
A two-year fix keeps the interest rate and monthly payment unchanged for two years. When the deal ends, you’ll normally need either another product with the same lender, a remortgage elsewhere, or to accept the lender’s standard variable rate — which is often more expensive than a competitive new deal.
Its attraction is straightforward. If mortgage rates are substantially lower two years from now, you’re back in the market relatively quickly and can potentially benefit. The trade-off is that you’re also exposed sooner if rates have risen, your circumstances have changed or mortgage products have become less favourable.
A five-year fix buys substantially more certainty. Your interest rate is protected for five years, making household budgeting much easier and removing the need to worry about refinancing after only 24 months.
But certainty has its own price. If market rates fall sharply, you don’t automatically benefit. Leaving the deal early may involve an early repayment charge, and five years is long enough for circumstances that currently look settled — work, relationships, family plans or the property itself — to change.
A tracker mortgage moves in line with another interest rate, usually Bank Rate, plus a margin set by the lender. With Bank Rate at 3.75% in mid-September 2026, an illustrative tracker priced at Bank Rate plus 0.60 percentage points would currently charge 4.35%.
If Bank Rate fell by half a percentage point, that illustrative mortgage rate would normally fall to 3.85% under the product terms. If Bank Rate rose by half a point, it would become 4.85%.
That creates both the attraction and the risk: you don’t need to wait until a fixed period ends to benefit from lower rates, but you also have no fixed-payment protection if rates move upwards.
MoneyHelper’s guide to fixed and variable mortgage rates explains the basic structures, but the important detail is that trackers aren’t interchangeable. The margin, any minimum-rate floor, early repayment charge and length of the tracker period can vary meaningfully between products.
A useful way to think about the three choices is this:
| Mortgage structure | What you gain | What you give up | Often deserves closer consideration when… |
|---|---|---|---|
| Two-year fix | Short-term payment certainty and an earlier chance to refinance | You face the mortgage market again relatively soon | You want certainty now without locking today’s rate in for five years |
| Five-year fix | Long period of predictable payments | Less ability to benefit from falling rates and potentially longer ERC exposure | Budget certainty matters more than trying to capture a future rate fall |
| Tracker | Immediate benefit if the underlying rate falls | Payments can rise as well as fall | Your finances can comfortably absorb rate movements and you value flexibility |
That isn’t a recommendation table. It’s a way of identifying what you’re actually buying with each structure: certainty, flexibility or exposure to future rates.
Today’s rates make loan-to-value matter almost as much as deal length
There is another reason statements such as “the average two-year fix is 5.6%” aren’t particularly useful on their own.
Mortgage pricing changes substantially according to loan-to-value — how much you’re borrowing compared with what the property is worth.
Rightmove’s mortgage-rate tracker on 12 September 2026 showed average homebuyer rates of about 4.72% for a two-year fix and 4.76% for a five-year fix at 60% loan-to-value.
At 90% LTV, the equivalent averages were roughly 5.33% and 5.31%. At 95% LTV, they were around 5.78% and 5.75%.
The striking thing isn’t simply the level of rates. It’s that the difference between the two-year and five-year products at the same LTV was tiny compared with the difference created by the borrower’s deposit.
Someone comparing a two-year fix with a five-year fix therefore shouldn’t begin by asking which term has the lower national average. The first questions are what rates they can actually qualify for at their LTV, and what fees and restrictions come with those particular products.
Why the household matters more than the forecast
Go back to the two households at the start.
For the first — strong savings, two secure incomes and a mortgage comfortably inside the household budget — a tracker can be a perfectly rational option. If Bank Rate rises, they may be able to absorb the increase without hardship. If it falls, they benefit without having to wait for a fixed period to finish.
For the second household — high LTV, little spare cash and an expected temporary reduction in income — the exact same tracker carries much more risk.
Take an illustrative £250,000 repayment mortgage over 25 years. At 4.35%, the monthly repayment is approximately £1,368.
If the rate rose by half a percentage point to 4.85%, the payment would be around £1,440 — roughly £72 more every month.
At 5.35%, one percentage point above the starting rate, it would be approximately £1,513, around £145 more each month.
For one household, that might be irritating but entirely manageable. For another, £145 could be the difference between maintaining a healthy monthly buffer and having virtually none.
That’s the honest version of the fixed-versus-tracker decision. The financial significance of exactly the same rate movement depends on the household carrying it.
A fixed rate is partly a decision about what certainty is worth to you
There is a useful way of reframing the fixed-rate decision that avoids obsessing over whether you’ll eventually “beat” the market.
Suppose you fix at a rate you can comfortably afford and, two years later, equivalent mortgage rates are considerably lower. It is very easy with hindsight to calculate what you could have saved and conclude that fixing was a mistake.
But that isn’t necessarily what happened.
During those two years you knew what your mortgage would cost. You protected your household from the opposite outcome — rates rising rather than falling — and you were able to budget without carrying that uncertainty.
Economically, part of what you’re accepting with a fixed rate is the possibility of giving up a future saving in exchange for certainty today.
A tracker borrower makes the opposite choice. They retain more of the interest-rate uncertainty themselves. If their finances are strong enough to absorb adverse movements, that can be entirely rational too.
The better question is therefore not simply which option is expected to be cheapest.
It is who is best placed to carry the risk that nobody knows today’s answer to?
Don’t choose a tracker simply because you think rates will fall
Trackers become particularly tempting when newspapers, economists or financial markets expect Bank Rate to fall.
But the Bank of England’s own recent decisions show why mortgage choices shouldn’t depend entirely on that expectation. At its July 2026 meeting, the Monetary Policy Committee voted 6–3 to keep Bank Rate at 3.75%, with three members preferring an increase to 4%. The July Monetary Policy decision reflected continued uncertainty around inflation and energy prices.
That doesn’t mean rates will rise. Nor does it mean they will stay where they are.
It means the outcome is uncertain enough that the people actually responsible for setting Bank Rate can disagree about the appropriate direction.
A tracker therefore makes more sense when you can tolerate the risk of being wrong than when your household budget only works if the forecast turns out to be right.
The same logic works in reverse for a five-year fix. Fixing for five years because you’re certain rates will rise is still a forecast. Fixing because five years of predictable payments is genuinely valuable to your household is a much stronger reason.
If your current fixed deal is ending, the decision is slightly different
For existing homeowners approaching the end of a fixed deal, this isn’t an edge case. UK Finance expected around 1.8 million fixed-rate mortgages to reach the end of their deal during 2026, making refinancing one of the biggest mortgage decisions facing households this year. Its current mortgage-market forecasts also expected both external remortgaging and product transfers with existing lenders to increase.
A homeowner whose current fix is ending has two broad routes: take another product from the existing lender — usually called a product transfer — or remortgage to a different lender.
Those routes aren’t always equivalent.
Moving to another lender normally means satisfying that lender’s affordability and underwriting requirements. By contrast, an existing lender may be able to offer a straightforward product transfer without a fresh affordability assessment where the borrowing isn’t being increased. MoneyHelper’s guide to remortgaging explains the distinction.
There is also more room to plan ahead than many borrowers realise.
The Government’s Mortgage Charter commitments allow customers of participating lenders to lock in a new deal up to six months before their current fixed rate ends, and to ask for a better like-for-like deal if one becomes available before the new rate starts. The FCA’s September 2026 Mortgage Charter data says the 47 participating lenders represent around 90% of the mortgage market; more than 381,000 mortgages were locked into new deals up to six months ahead during the second quarter of 2026 alone.
That changes the familiar “should I fix now or wait?” dilemma.
For an eligible borrower, the choice may not always be between locking today’s rate and losing all chance of improvement, or waiting until the last moment and taking whatever is available then. Depending on the lender’s rules, there may be an opportunity to secure a fallback rate early and still move to a better like-for-like deal before it takes effect.
The exact process varies, so check your lender’s terms rather than assuming the Charter arrangement applies identically everywhere.
Life plans deserve a seat at the table — without overthinking them
A five-year fix fits more naturally with someone who expects to remain in their current home, or at least retain the same borrowing, for most or all of the fixed period.
Anyone who thinks they may move, repay a substantial amount, need to release equity or materially restructure their mortgage within two or three years needs to give the exit terms more weight.
This doesn’t require predicting your life with precision.
A possible move “at some point” isn’t the same thing as knowing your job is likely to relocate in eighteen months. A vague possibility of having children isn’t the same as a planned period of parental leave that will temporarily reduce household income.
The more concrete the expected change, the more weight it deserves in the mortgage decision.
There is also an asymmetry here worth noticing. A borrower with plenty of spare monthly income can often cope with a variable payment more easily than somebody with a highly predictable life but no financial buffer.
Financial resilience and life predictability aren’t the same thing.
The headline rate isn’t the full cost
Comparing mortgages on interest rate alone is one of the easiest ways to choose a deal that looks cheap but isn’t.
A lower-rate mortgage may carry a product fee of £999, £1,499 or considerably more. Another product may have no fee but a slightly higher rate. Cashback, valuation incentives and contributions towards legal costs can alter the calculation again.
MoneyHelper’s guide to mortgage fees and buying costs says arrangement or product fees commonly run to £1,000–£2,000 or more.
The effect of that fee depends heavily on how much you’re borrowing.
Consider two illustrative two-year fixes on a 25-year repayment mortgage. One charges 4.69% plus a £1,499 product fee paid upfront; the other charges 4.89% with no product fee.
On a £150,000 mortgage, the lower interest rate saves only about £596 of interest during the first two years. That doesn’t come close to recovering the £1,499 fee, so the apparently more expensive rate is cheaper over that period on these assumptions.
On a £500,000 mortgage, the lower rate saves roughly £1,987 of interest over the same two years. That is enough to outweigh the £1,499 fee by roughly £488.
The break-even mortgage balance in that particular example is somewhere around £377,000.
Those figures are illustrative and would change with the mortgage term, fee treatment, repayment structure and actual products involved. If the fee is added to the mortgage rather than paid upfront, interest will also be charged on it.
But the principle is extremely useful: the same product fee can make one deal poor value for a smaller mortgage and worthwhile for a larger one.
“Which rate is lower?” is therefore the wrong comparison.
The useful question is: which deal costs less over the period I realistically expect to keep it?
A two-year fix can mean paying for the decision twice
There is another cost to a shorter fix that is easy to overlook.
If you take a two-year mortgage and refinance when it ends, you may face another product fee, valuation costs or other remortgaging expenses relatively soon. Some deals cover some of those costs, and staying with the same lender through a product transfer can be simpler, but those costs shouldn’t simply be assumed away.
A five-year fix may therefore cost more or less than a two-year fix for reasons the interest-rate difference alone doesn’t reveal.
If two deals are almost identical in rate but the two-year mortgage carries a substantial product fee, it matters whether you’re potentially paying another comparable fee two years later.
That doesn’t automatically make the five-year product better. It simply means “I’ll fix for two years and get a cheaper mortgage afterwards” isn’t a complete calculation unless the cost of getting that later mortgage is included too.
Early repayment charges matter most when your plans change
Fixed-rate mortgages frequently carry early repayment charges during the fixed period. Trackers can carry them too, although some tracker products offer greater exit flexibility.
An ERC is normally calculated as a percentage of the remaining mortgage balance, and the percentage may reduce as the deal gets closer to its end. The exact structure depends entirely on the mortgage.
This is where percentages can hide surprisingly large cash numbers.
A 3% early repayment charge on £240,000 outstanding is £7,200.
That doesn’t mean every borrower leaving a deal would pay that amount. The applicable percentage could be different, the mortgage may be portable, an allowed overpayment could reduce the balance, or particular product conditions may apply.
It does show why the ERC schedule deserves more attention than it often receives when somebody is considering a long fix.
Many mortgages also allow limited penalty-free overpayments, often up to a specified percentage each year. But the amount, calculation method and conditions vary, so anyone expecting a bonus, inheritance or other lump sum should check the actual product terms rather than assuming they’ll be able to reduce the balance freely.
Portability isn’t a blank cheque
Many mortgages are described as portable, which sounds reassuring if there’s any possibility you’ll move during the deal.
But “portable” doesn’t mean the lender has promised to transfer your mortgage to any future property regardless of your circumstances.
Porting normally involves a new mortgage application. The lender can reassess affordability, the new property must satisfy its lending criteria and any additional borrowing may need to be taken on a separate product at whatever rate is available at the time.
Imagine somebody with £200,000 left on a five-year fix who moves to a more expensive home and needs a £300,000 mortgage.
Even if the existing £200,000 can be ported on its old rate, the additional £100,000 may be borrowed on a new rate. The borrower can end up with two mortgage parts running on different products and potentially ending at different times.
Portability is genuinely useful. It just isn’t insurance against every consequence of moving during a fixed term.
Don’t forget what happens when the deal ends
A fixed mortgage protects the payment only for the fixed period.
If the borrower reaches the end of the two or five years and does nothing, the mortgage will normally revert to the lender’s standard variable rate. That rate can be considerably higher than competitive new mortgage deals.
This makes the end date part of the product decision from the beginning.
A two-year fix means needing to engage with the mortgage market again relatively soon. For some borrowers that’s an advantage. For others — particularly someone who values simplicity or whose circumstances may become harder to evidence for a fresh mortgage application — it is a meaningful downside.
Likewise, fixing for five years doesn’t make the future refinancing problem disappear. It simply pushes it further away.
The useful stress test is different for each option
Rather than asking which mortgage you think will prove cheapest, ask what happens if the particular risk you accepted actually materialises.
If you’re considering a tracker, calculate the payment at today’s rate, then calculate it again at half a percentage point and one percentage point higher. If either result would create genuine difficulty rather than mild irritation, you’re learning something important about whether your household should be carrying that rate risk.
If you’re considering a two-year fix, don’t test it against the assumption that rates will be lower when it ends. Ask what happens if they are one percentage point higher when you have to refinance — particularly if your income, childcare costs or other commitments may also have changed.
If you’re considering a five-year fix, test the opposite regret. Imagine equivalent mortgage rates are materially lower in three years but your ERC makes leaving uneconomic. Would you still regard the payment certainty you bought as worthwhile, or would being locked in cause genuine financial difficulty?
The point isn’t to find the scenario that makes each product look worst.
It’s to identify which wrong outcome your household is least able to tolerate.
That distinction is more useful than trying to predict which product will eventually win a five-year hindsight comparison.
A framework for the actual decision
Once those risks are understood, the decision becomes less about forecasting and more about priorities.
How much would it genuinely matter if your payment rose by £100, £200 or £300 a month? Is that money currently genuine spare capacity, or would the increase have to come from savings, pension contributions or ordinary household spending?
How likely are you to move, repay a substantial lump sum or need different borrowing within the next two to five years?
Would a two-year fix still look attractive after allowing for another round of product fees and refinancing costs?
If a five-year fix turned out to be more expensive than the market in three years’ time, would you regard the difference as money wasted — or as the price you knowingly paid for certainty?
And if you’re considering a tracker, is it affordable at today’s rate, or only attractive because you’re assuming Bank Rate will fall?
None of this is a substitute for regulated mortgage advice tailored to your income, deposit, credit history, property and wider circumstances. An FCA-authorised mortgage adviser can assess the products available to you and explain the particular fees, early repayment charges, lending criteria and risks attached to them.
But the framework gives you a better question to take into that conversation.
Not: “Which mortgage will turn out to have been cheapest?”
Nobody can know that today.
The better question is: “Which mortgage leaves my household in an acceptable position if rates don’t do what I hope?”
For many borrowers, that is the difference between choosing a mortgage by prediction and choosing one by resilience.
This article provides general information about mortgage products and is not personalised mortgage, financial or investment advice. Mortgage rates, fees, early repayment charges and product availability can change frequently and depend on individual circumstances, loan-to-value, credit profile, property and lender criteria. Worked examples are illustrative only and exclude some potential costs. Before choosing or changing a mortgage, check the full product terms and, where appropriate, seek advice from an FCA-authorised mortgage adviser.

