

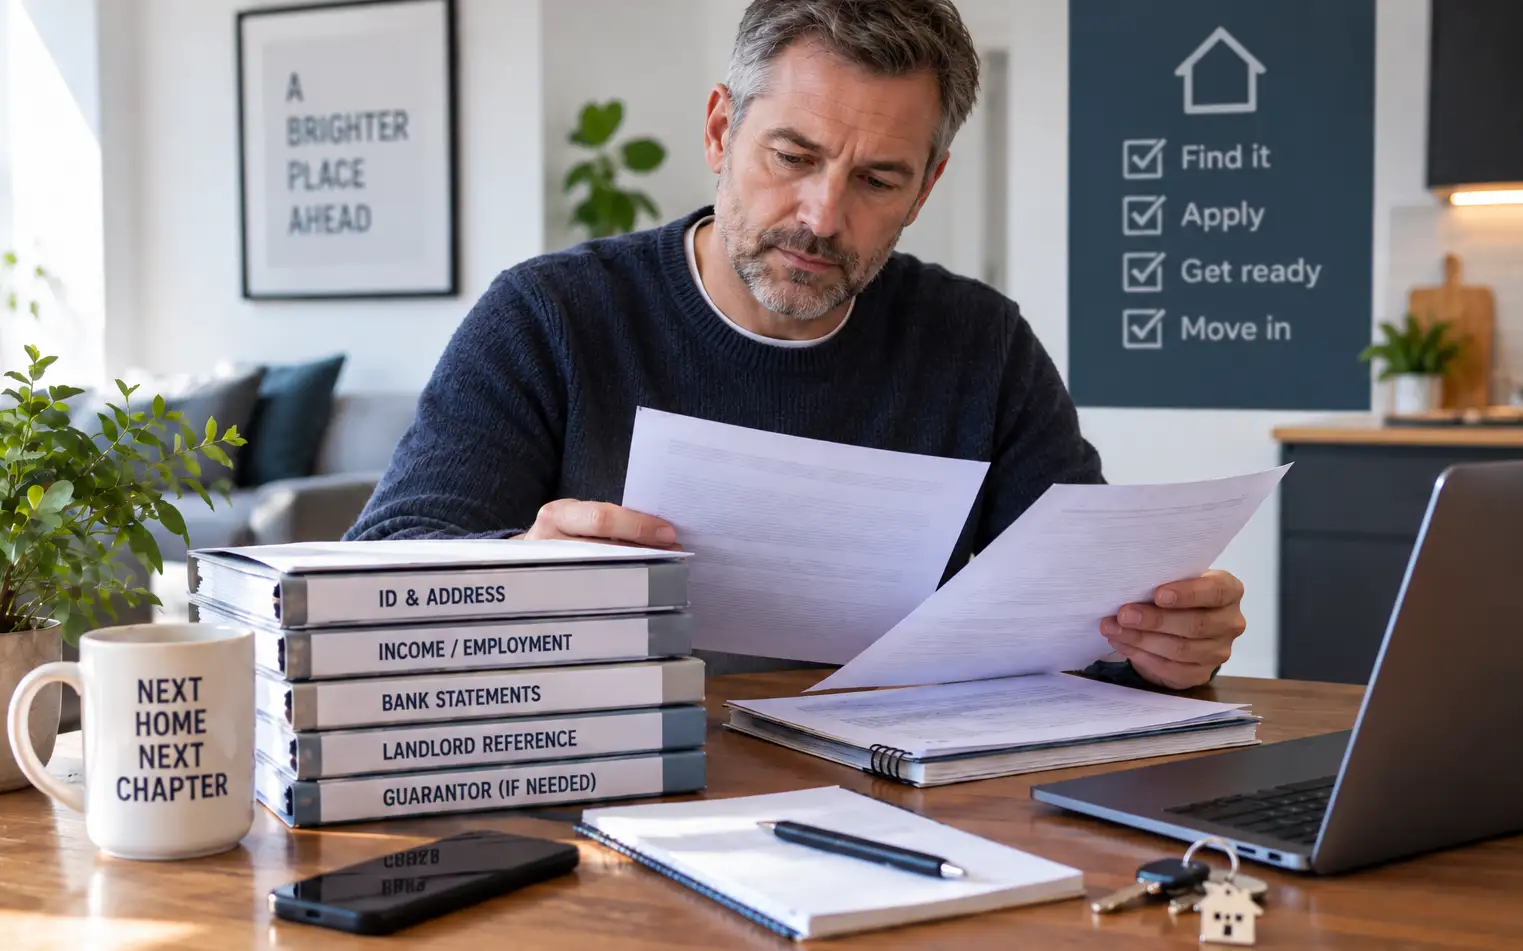
The property that’s right for you won’t wait. In a competitive rental market, a well-priced, well-located home can attract several applicants within days, sometimes hours, of being listed. The renters who move fastest aren’t necessarily the most desirable tenants on paper — they’re simply the ones who were ready to apply the moment the right place appeared.
Being transaction-ready isn’t about outcompeting other applicants through some clever tactic. It’s about not losing a home you’d have got anyway, purely because your paperwork wasn’t in order when it mattered.
What referencing actually asks for
Referencing requirements vary between landlords, agents and referencing providers, but most UK applications draw on a similar pool of evidence: proof of identity, proof of your current address, evidence of employment and income (typically recent payslips or an employment contract), a previous landlord reference where you have one, and a credit check. Depending on the provider and your circumstances, you may also be asked for bank statements, evidence of savings, or a guarantor.
Not every landlord or agent asks for everything on this list — a smaller private landlord letting directly may take a lighter-touch approach than a large agency using a formal referencing company. But having the fuller set ready means you’re never the reason an application stalls.
If you don’t have a rental history yet
First-time renters, people moving out of a family home, and anyone early in a new job can find referencing awkward, simply because the standard evidence — a previous landlord reference, a settled employment history — doesn’t exist yet. This is a common situation, not automatically a disqualifying one. Referencing providers are used to it, and the process may lean more heavily on other evidence: a guarantor, a longer look at savings, or a written character reference, rather than treating the gap as a red flag in itself.
If this applies to you, it’s worth anticipating the question rather than being caught out by it. Have an explanation ready, and know in advance who might act as a guarantor if one’s needed.
Self-employed and irregular income
Self-employed applicants are usually asked for a different evidence set than employees — this may include recent accounts or tax returns, business bank statements, or a reference from an accountant. If you’ve only been self-employed a short time, expect the process to ask for more, not less, and consider having a guarantor lined up in advance rather than discovering the requirement mid-application. Requirements vary meaningfully between providers, so don’t assume one agency’s list is universal.
Guarantors: what they’re actually agreeing to
A guarantor is typically requested where a tenant’s income, credit history or employment status doesn’t independently meet a landlord’s threshold. Guarantors are usually expected to meet a higher income bar than the tenant would have needed alone, precisely because they’re underwriting the full rent on top of their own financial commitments — reflecting the fact that a guarantor is taking on a real financial obligation, not offering a character reference.
If you’re asking someone to be a guarantor, or being asked to act as one, it’s worth being clear-eyed about what’s actually being agreed: the guarantor can be pursued for unpaid rent, and on a joint tenancy, may be liable for the whole tenancy’s rent, not just one tenant’s share, depending on how the agreement is worded. Read what you’re signing before you sign it.
Holding deposits: the point where money changes hands
Once you’ve applied and been provisionally accepted, you may be asked for a holding deposit to take the property off the market while checks are completed. In England and Wales, this is capped by law at one week’s rent, and there are statutory rules about how long it can be held and when it must be returned. The rules differ elsewhere in the UK: Scotland does not permit a separate holding fee, while Northern Ireland operates different rules. The detail of holding deposits, tenancy deposits and permitted fees deserves its own space — you’ll find the full picture in our Rent, Deposits & Fees section. For now, the point worth knowing is simply that this stage may involve a real payment, so it shouldn’t come as a surprise partway through an application.
Right to rent checks — an England-specific requirement
For most private rentals in England, the landlord or agent must check that each adult occupier has the right to rent, regardless of nationality. How you prove it depends on your status. British and Irish citizens will normally use an accepted identity document or a registered digital identity check; many other applicants with digital immigration status will use a Home Office share code. The government’s right-to-rent guidance explains the accepted routes.
This is worth knowing in advance simply so the request doesn’t feel unexpected: it’s a standard step in England, carrying penalties for landlords who skip it, not a judgement on you personally. It’s also worth being clear that right to rent checks apply only in England — there is no equivalent requirement for tenancies in Scotland, Wales or Northern Ireland.
Discrimination based on benefits or children is now unlawful
Blanket “no DSS” style policies, or refusing applicants because they have children, are now unlawful under rental-discrimination rules introduced by the Renters’ Rights Act 2025. The rules have applied in England and Scotland since 1 May 2026 and in Wales since 1 June 2026. These specific provisions do not extend to Northern Ireland. They go beyond outright refusals — deliberately disregarding benefit income when assessing affordability can breach the rules. Landlords can still apply affordability criteria, but they should treat all forms of income equally. If you believe you’ve been turned away purely because you receive benefits or have children, that’s worth taking further, and the detail of how to challenge it sits within our Renters’ Rights section.
Rent in advance: what’s changed
It used to be common for renters without a strong UK credit history — international students, recent arrivals, or anyone without a guarantor — to be asked for several months’, or even a year’s, rent upfront to secure a tenancy. Under the Renters’ Rights Act, that’s no longer lawful for most private assured tenancies agreed from 1 May 2026 in England: rent cannot be asked for, encouraged or accepted before the tenancy agreement is signed, and once it is signed a landlord can usually ask for no more than one month’s rent for a monthly tenancy, or up to 28 days’ rent where rent is paid more frequently, before the tenancy starts. The government’s rent-in-advance guidance for tenants explains the new limits. If you’re asked to offer several months upfront as a workaround, don’t rely on it — a landlord asking for it, encouraging it or accepting it may be breaching the rules.
Handling your documents sensibly
You’ll likely be sending payslips, bank statements, identity documents and other sensitive material to agents and landlords during this process. Basic caution is worth applying here — send documents to verified agency or landlord contacts rather than an unverified personal email or a stranger you’ve only met through an online listing, and be wary of anyone asking for money or documents before you’ve seen the property or verified who they actually are.
What you should have ready
By the time the right property appears, aim to have: proof of ID and address, recent payslips or income evidence appropriate to your employment status, contact details for a previous landlord if you have one, a guarantor identified and willing if you think you might need one, and a realistic sense of what any holding deposit, tenancy deposit and first rent payment will actually cost you in cash. None of this guarantees you the property. It does mean that when the right one appears, you’re not the reason it slips away.
This article has deliberately stayed away from deposit protection disputes, tenancy contract terms, rent arrears and eviction — each of those belongs elsewhere in our Renting & Landlords coverage, and you’ll find them addressed in full there.
This article provides general property information, not legal or financial advice for your individual circumstances. Referencing requirements vary between landlords, agents and providers. If you believe you’ve experienced unlawful discrimination in a rental application, you may wish to seek advice from a housing advice service or solicitor.

